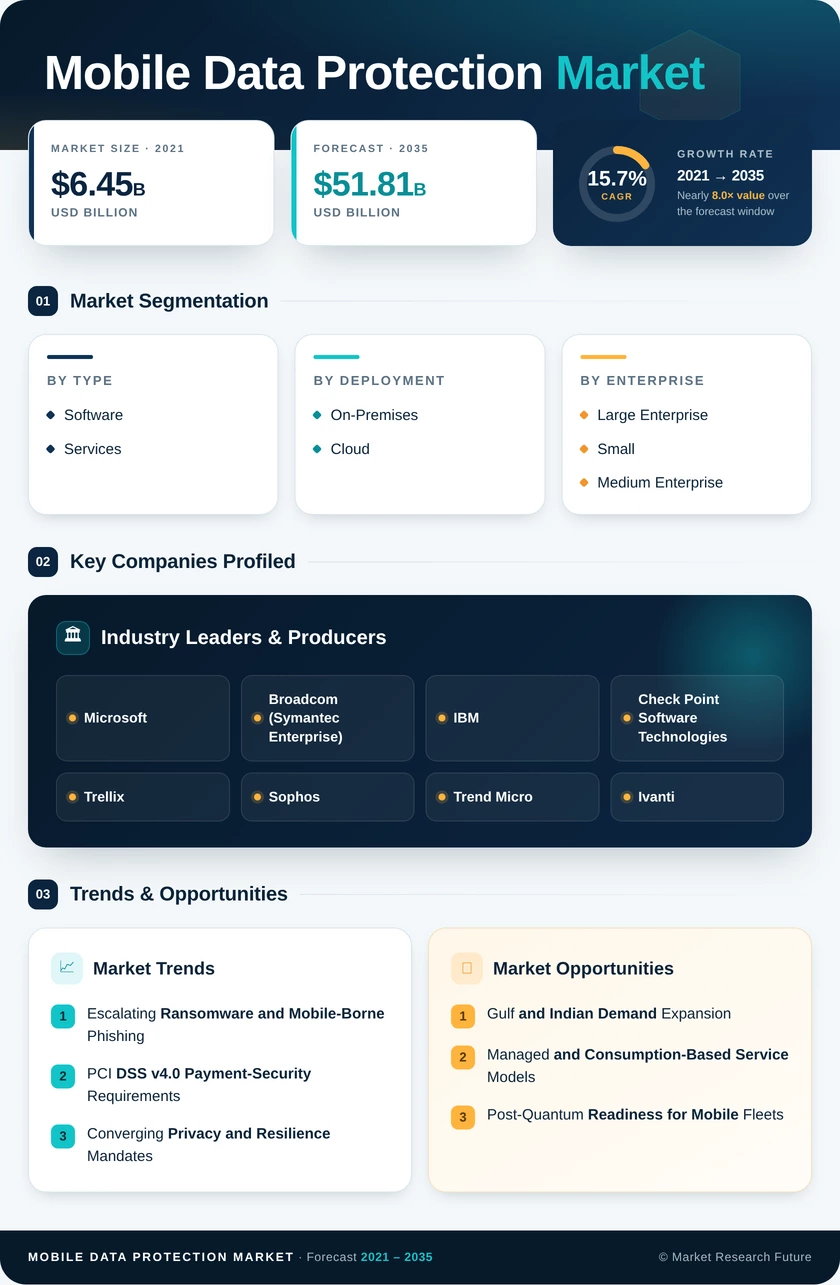
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Type | Software, Services | Software (63.1% share) | Services (17.1% CAGR) |
| By Deployment | On-Premises, Cloud | On-Premises (54.6% share) | Cloud (17.6% CAGR) |
| By Enterprise | Large Enterprise, Small and Medium Enterprise | Large Enterprise (66.6% share) | Small and Medium Enterprise (17.0% CAGR) |
| By End-User Industry | BFSI, Healthcare, Retail, Hospitality, Transport | BFSI (36.1% share) | Healthcare (17.6% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East and Africa | North America (43.3% share) | Middle East and Africa (17.7% CAGR) |
Market Segmentation Overview
By Type
| Sub-Segment | Key Trend |
|---|---|
| Software | Encryption, data-loss, and detection modules converging into unified suites. |
| Services | Outsourced incident response, integration, and partner training expanding rapidly |
Software leads with 63.1% of 2025 revenue because regulated buyers keep licensed encryption and policy engines inside their own estates. Services grows fastest at a 17.1% CAGR as forensic and compliance skills remain scarce and suite migrations require integration work. The gap narrows through 2035 as more buyers purchase outcomes rather than tools.
By Deployment
| Sub-Segment | Key Trend |
|---|---|
| On-Premises | Sustained by air-gap rules and in-country hosting mandates |
| Cloud | Favored for subscription pricing, instant patching, and zero-trust policy engines |
On-Premises holds 54.6% of 2025 revenue, protecting defense, government, and banking environments that cannot send keys or logs offsite. Cloud grows fastest at a 17.6% CAGR because zero-trust frameworks reward cloud-native policy engines and buyers want to avoid patching their own servers. Hybrid models keep sensitive keys local while running analytics in the cloud.
By Enterprise
| Sub-Segment | Key Trend |
|---|---|
| Large Enterprise | Extending controls to contractors and supply-chain partners |
| Small and Medium Enterprise | Buying to meet insurer requirements under per-user monthly pricing |
Large Enterprise buyers account for 66.6% of 2025 spending, driven by supply-chain exposure and suite licensing that covers employees and contractors alike. Small and Medium Enterprise demand grows fastest at a 17.0% CAGR because insurers now require endpoint detection before issuing cyber policies. Consumption pricing removes the upfront cost that previously kept smaller firms out.
By End-User Industry
| Sub-Segment | Key Trend |
|---|---|
| BFSI | Payment-security and resilience rules applied to apps and staff devices |
| Healthcare | Clinical mobility meeting stricter encryption and breach penalties |
| Retail | Mobile point-of-sale and associate handhelds widening exposure |
| Hospitality | Guest tablets and payment terminals added to managed fleets. |
| Transport | Driver tablets and connected-vehicle systems requiring offline controls |
BFSI leads with a 36.1% share because PCI DSS v4.0 and DORA apply directly to banking apps and employee devices. Healthcare grows fastest at a 17.6% CAGR as clinicians depend on mobile record access and the proposed HIPAA update would make encryption mandatory. Retail, Hospitality, and Transport add steady demand as payment and fleet devices join managed environments.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA