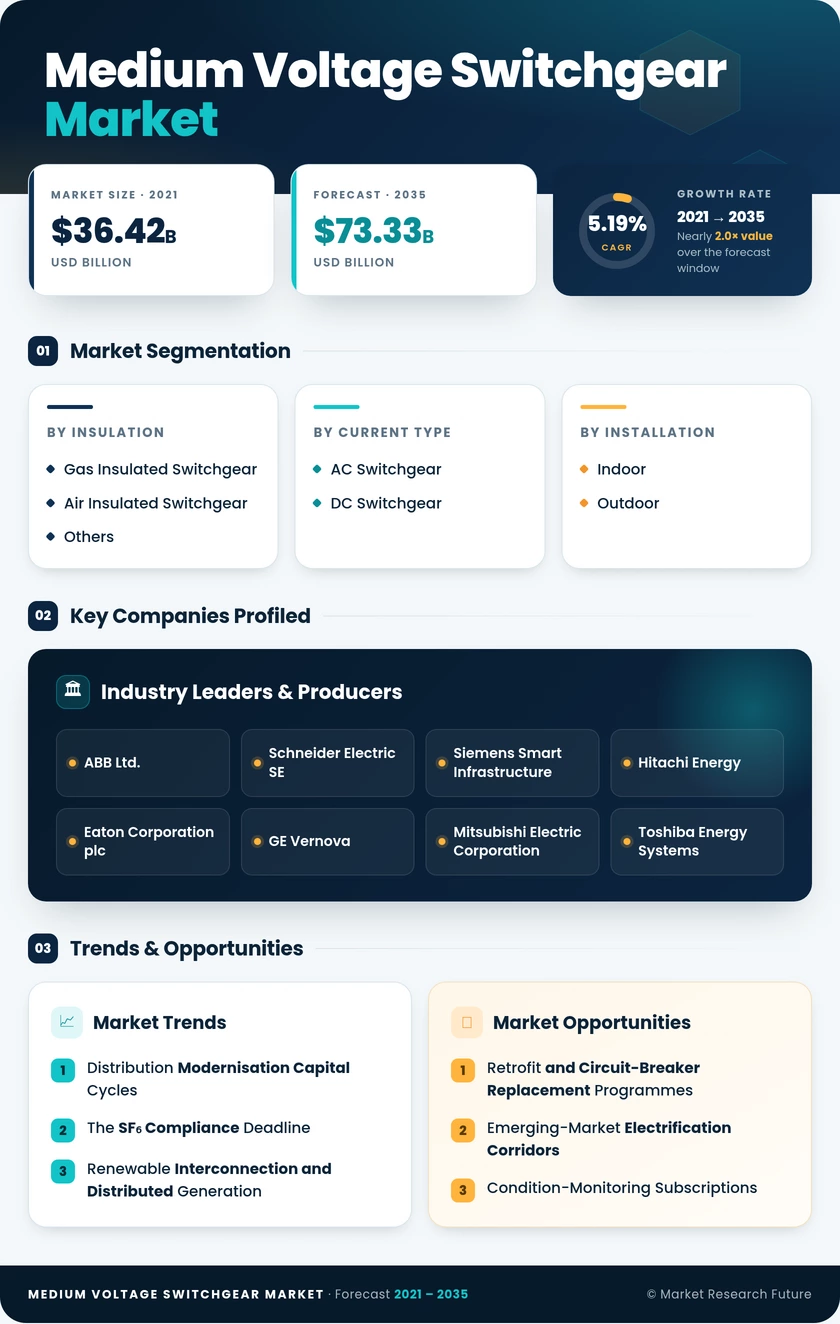
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Insulation | Gas Insulated Switchgear, Air Insulated Switchgear, Others | Gas Insulated Switchgear | Others (solid-dielectric / clean-air) |
| By Current Type | AC Switchgear, DC Switchgear | AC Switchgear | DC Switchgear |
| By Installation | Indoor, Outdoor | Indoor | Indoor |
| By End-User | Utilities, Residential, Commercial, Industrial | Utilities | Residential |
| By Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific | Asia-Pacific |
Market Segmentation Overview
By Insulation
| Sub-Segment | Key Trend |
| Gas Insulated Switchgear | Migration from SF₆ to fluoronitrile and dry-air dielectrics within the same compact envelope |
| Air Insulated Switchgear | Steady demand in rural feeders and cost-sensitive emerging grids, with gradual share erosion |
| Others | Solid-dielectric and clean-air designs scaling rapidly under European and North American regulation |
Insulation is now the segmentation dimension with the highest regulatory beta. Compliance deadlines rather than end-user preference determine adoption curves, which makes the alternative-insulation category unusually forecastable relative to the rest of this industry.
By Current Type
| Sub-Segment | Key Trend |
| AC Switchgear | Remains the default architecture across every utility distribution network globally |
| DC Switchgear | Emerging demand from hyperscale computing, rail traction and shipboard electrification |
Alternating-current equipment will continue to define volume economics through 2035. Direct-current variants matter strategically because they carry higher engineering content and face far less commoditisation pressure.
By Installation
| Sub-Segment | Key Trend |
| Indoor | Preferred in urban and coastal environments for pollution and vandalism protection |
| Outdoor | Sustained in North American and Australian overhead distribution networks |
Land economics decide this segmentation more than any technical factor. As distribution assets concentrate in dense urban corridors, indoor and compact-substation formats absorb a rising share of new installations.
By End-User
| Sub-Segment | Key Trend |
| Utilities | Framework-contract purchasing that sets pricing benchmarks industry-wide |
| Residential | Fastest expansion as rooftop solar, storage and neighbourhood microgrids proliferate. |
| Commercial | Data centres, hospitals and campuses driving premium redundancy specifications |
| Industrial | Process electrification and arc-flash safety upgrades in heavy manufacturing |
Buyer diversification is the structural story here. Utilities still anchor volume, but commercial and residential-adjacent demand grows faster, and rewards different capabilities — schedule certainty, standardised packaging and service attach rather than lowest installed cost.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA