Medium Voltage Switchgear Market (2026 - 2035)

Medium Voltage Switchgear Market Research Report By Insulation (Gas Insulated Switchgear, Air Insulated Switchgear, Others), By Current Type (AC Switchgear, DC Switchgear), By Installation (Indoor, Outdoor), By End-User (Utilities, Residential, Commercial, Industrial) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast to 2035
ID: MRFR/EnP/21292-HCR 100 Pages Chitranshi Jaiswal Last Updated: August 28, 2026
Medium Voltage Switchgear Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.19%
2025 Market SizeUSD 44.53 Billion
2035 Market SizeUSD 73.33 Billion
Key Players
ABB Ltd.
Schneider Electric SE
Siemens Smart Infrastructure
Hitachi Energy
Eaton Corporation plc
GE Vernova
Opportunities
  • No data available

Medium Voltage Switchgear Market Summary

The Medium Voltage Switchgear Market closed 2025 at USD 44.53 billion and opens the forecast window at USD 46.51 billion in 2026, climbing to USD 73.33 billion by 2035 at a 5.19% CAGR. Two catalysts anchor that trajectory. Global grid investment crossed USD 400 billion annually for the first time in 2024, with distribution networks absorbing roughly two-thirds of it [2]. Alongside that, the U.S. Department of Energy's Grid Resilience and Innovation Partnerships programme committed USD 10.5 billion to distribution hardening and reconductoring projects that pull medium-voltage assemblies into scope [4].

The oil-filled and early-generation SF₆ equipment that was installed in the 1980s and 1990s is being retired by utilities. It is being replaced with vacuum-interrupter and clean-air designs that contain embedded protection intelligence. Europe's F-Gas Regulation (EU) 2024/573 establishes staged prohibitions on new SF₆ equipment below 24 kV beginning in 2026. The compliance clock is already reshaping order books throughout the Medium Voltage Switchgear Market [6]. According to the International Energy Agency (IEA), in order to satisfy national energy objectives by 2040, 80 million kilometers of grid must be constructed or renewed [1].

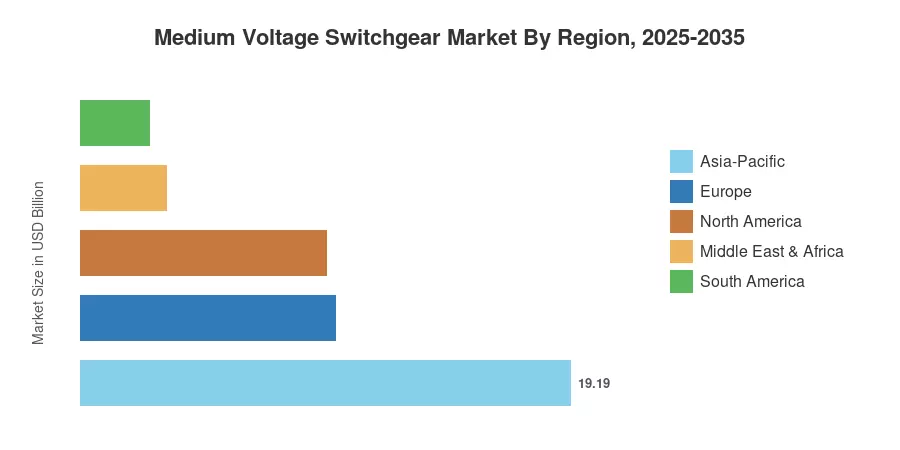
The Medium Voltage Switchgear Market is anchored by Asia-Pacific, which is expected to generate 43.1% of 2025 revenue and experience the quickest growth at a compound annual growth rate (CAGR) of 7.3%. This growth is primarily due to China's ultra-high-voltage build-out and India's Revamped Distribution Sector Scheme [9][11]. The replacement tempo in Europe is determined by regulatory phase-outs rather than volume growth, with a rate of 22.4%. The data center interconnection delays are the driving force behind North America's third-place ranking. Suppliers who are capable of reducing lead times, rather than merely lowering unit prices, will be rewarded in the upcoming decade.


Key Report Takeaways

• By Insulation

  • Gas-insulated designs held 42.8% of Medium Voltage Switchgear Market revenue in 2025, sustained by urban substation footprint limits.
  • Solid-dielectric and clean-air alternatives are advancing at an 11.2% CAGR through 2035 as fluorinated-gas rules tighten.
  • DC-rated assemblies remain niche but post a 6.7% CAGR on hyperscale computing demand.

• By End user

  • Utilities accounted for 41.8% of 2025 Medium Voltage Switchgear Market spending.
  • Industrial buyers contributed USD 12.31 billion in 2025, concentrated in mining, petrochemicals and semiconductor fabs.
  • Residential and distributed-generation applications grow fastest at 7.7% CAGR.

• By Region

  • Asia-Pacific captured 43.1% of the Medium Voltage Switchgear Market in 2025
  • North America generated USD 9.62 billion in 2025 revenue
  • Middle East & Africa expands at a 6.5% CAGR on Gulf grid diversification programmes


Market Size and Forecast (2021–2035)

Estimates blend supplier revenue disclosures, utility capital expenditure filings, customs-level trade flows for HS 8537 assemblies, and regulator-published network investment plans. Historical years reflect audited or reported data; forecast years apply bottom-up installed-base modelling cross-checked against announced grid programme budgets.
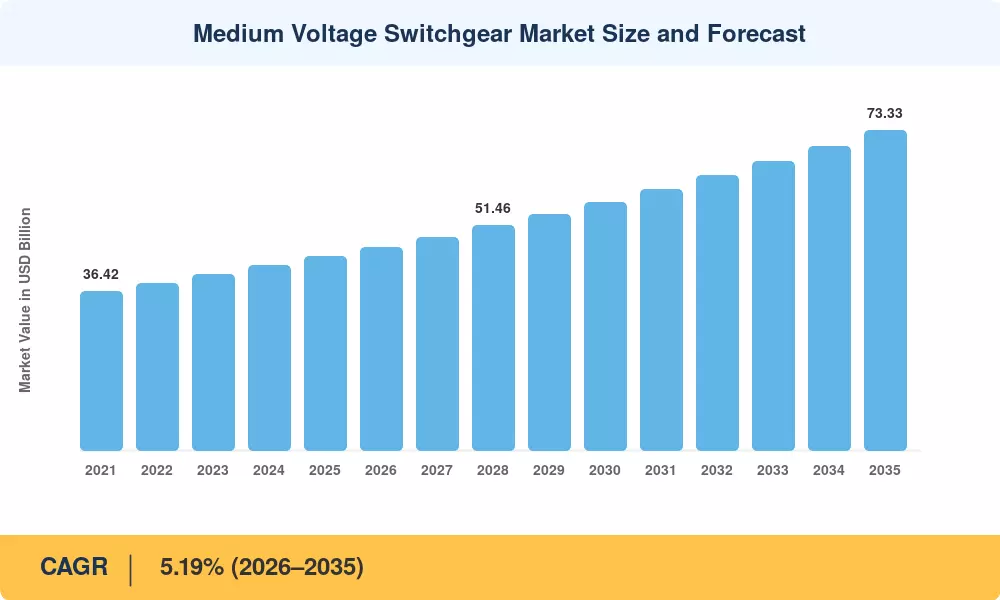
Medium Voltage Switchgear Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Distribution network modernisation programmes ~1.35% Global Long-term (≥4 yr)
Fluorinated-gas phase-down regulation ~0.95% Europe, North America Medium-term (2–4 yr)
Renewable interconnection at distribution level ~0.85% Global Long-term (≥4 yr)
Data centre and hyperscale campus build-out ~0.75% North America, Asia-Pacific Short-term (≤2 yr)
Urbanisation and compact substation demand ~0.60% Asia-Pacific, MEA Long-term (≥4 yr)
Grid resilience mandates after extreme weather ~0.50% North America, Europe Medium-term (2–4 yr)
Digital protection and asset-monitoring adoption ~0.45% Global Medium-term (2–4 yr)


Distribution Modernisation Capital Cycles

Ageing feeders are the binding constraint on electrification, and regulators have started funding accordingly. Ofgem's price control frameworks allocate substantial capital investment to network operators for the 2026–2031 period, with automation and switchgear replacement named as priority workstreams. India's Revamped Distribution Sector Scheme carries a multi-trillion outlay, of which loss-reduction works and feeder segregation directly consume ring main unit MV distribution equipment. These are multi-year committed budgets, not aspirational targets, which is why they underwrite the steadiest slice of demand in the Medium Voltage Switchgear Market.


The SF₆ Compliance Deadline

Europe set a hard schedule. Regulation (EU) 2024/573 bars new SF₆-containing equipment rated up to 24 kV from January 2026, extending to 52 kV in 2030 [6]. Utilities that had been trialling alternatives now face procurement decisions on live tenders. Vacuum switching with dry-air or fluoronitrile insulation has emerged as the mainstream answer, and the capital premium has narrowed from around 25% in 2021 to roughly 12–15% today [15].

Renewable Interconnection and Distributed Generation

Solar and storage assets connect at medium voltage far more often than at transmission level. IRENA recorded 585 GW of renewable capacity additions in 2024, the majority of it distribution-connected [3]. Each interconnection requires switching, protection and metering assemblies specified for bidirectional flow and fault-current contribution profiles that legacy panels were never designed to handle.

Hyperscale Computing Load Growth

Data centres have moved from marginal to material. Uptime Institute survey data indicates average design capacity per new facility roughly doubled between 2020 and 2025, pushing campuses into dedicated 33 kV intake substations [25]. Operators buy for schedule certainty and redundancy topology, which favours pre-engineered modular assemblies over site-built solutions.


Restraints Impact Analysis

Restraint weightings reflect estimated drag on realised growth relative to unconstrained demand. They are directional analyst judgements rather than deterministic subtractions from the headline CAGR.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Component and raw-material lead times ~-0.65% Global Short-term (≤2 yr)
Capital budget constraints at utilities ~-0.45% South America, Africa Medium-term (2–4 yr)
Skilled commissioning workforce shortage ~-0.35% North America, Europe Medium-term (2–4 yr)
Standards fragmentation across jurisdictions ~-0.25% Global Long-term (≥4 yr)
Retrofit complexity in brownfield substations ~-0.20% Europe, North America Short-term (≤2 yr)


Supply Chain Bottlenecks

Vacuum interrupter tubes, grain-oriented electrical steel and epoxy insulating resin all sit on constrained supply curves. Analysis places typical utility-grade panel lead times between 60 and 90 weeks in 2025, roughly triple pre-2020 norms [13]. Capacity expansions announced by major suppliers will not fully land until 2027, so schedule risk stays elevated through the near forecast years.

Funding Gaps in Emerging Grids

World Bank assessments identify a persistent shortfall in distribution investment across Sub-Saharan Africa and parts of South America, where tariff structures fail to recover replacement capital [23]. Projects get specified, tendered, then deferred. Concessional finance helps at the margin, but it rarely covers the operating expenditure needed to maintain digital equipment once installed.

Commissioning Talent Scarcity

Protection engineers capable of configuring and testing digital MV switchgear IEC 61850 architectures remain scarce. EPRI workforce studies flag retirement rates exceeding new-entrant training throughput across North American utilities, which pushes commissioning windows out and occasionally forces buyers back toward simpler electromechanical specifications [21].


Medium Voltage Switchgear Market Future Outlook

Autonomous Fault Management

Self-healing feeder schemes that isolate and restore supply without operator intervention move from pilot to standard specification during this decade. Utilities deploying automated reconfiguration report outage duration reductions of 30–45% on treated circuits [21]. Every automated node needs switching hardware with communications-capable actuators, which lifts content value per feeder well above simple unit replacement.

Electrification Supercycle

Transport and heat electrification changes the load shape that distribution assets were sized for. The IEA projects electricity demand growth outpacing total energy demand growth by roughly three to one through 2035 [1]. Feeders designed for 1990s diversity factors will need reconductoring and switchgear uprating well before their nominal end of life.

Service Revenue Displacing Product Margin

Vendors increasingly compete on installed-base economics. Annual reports from leading suppliers show service and software lines growing at roughly double the rate of new equipment sales, with materially higher margin profiles [16][17]. Expect portfolio decisions across the Medium Voltage Switchgear Market to be judged on aftermarket attach rates rather than unit volume alone.

Sustainability Disclosure Pressure

Corporate reporting regimes now require disclosure of fugitive fluorinated-gas emissions, which puts switchgear inventories directly into scope for utility and industrial ESG statements [6]. That reporting burden gives finance departments a reason to accelerate replacement schedules that engineering departments had already recommended, a rare alignment of incentives across the Medium Voltage Switchgear Market.


Medium Voltage Switchgear Market Segmentation

By Insulation

Insulation choice determines footprint, maintenance regime and regulatory exposure across the Medium Voltage Switchgear Market.

Segment Metric Primary Demand Driver
Gas Insulated Switchgear 42.8% share (2025) Urban substation footprint constraints
Air Insulated Switchgear 40.1% share (2025) Lower capital cost in space-tolerant sites
Others (solid-dielectric, clean-air) 11.2% CAGR (2026–2035) Fluorinated-gas prohibition compliance


Gas-insulated equipment retains its lead because square metres cost more than switchgear in dense cities. Air-insulated designs still dominate rural feeder applications and industrial sites where land is available, though their share erodes gradually as urbanisation shifts the installation mix. The alternative-insulation category is the one to watch: it compounds faster than any other technology segment, and its growth is regulation-locked rather than demand-elastic.

By Current Type

Current type segmentation within the Medium Voltage Switchgear Market reflects a market still overwhelmingly alternating-current, with a small but structurally interesting direct-current niche.

Segment Metric Primary Demand Driver
AC Switchgear 92.8% share (2025) Universal utility distribution architecture
DC Switchgear 6.7% CAGR (2026–2035) Hyperscale computing and traction power systems


The AC Switchgear segment dominates the market, capturing a significant 92.8% share in 2025, driven by universal utility distribution architectures. Meanwhile, the DC Switchgear segment is identified as the fastest-growing component, registering a 6.7% CAGR (2026–2035) fueled by hyperscale computing and traction power systems. Relevant regulatory policies include regional modernization frameworks like Ofgem's RIIO-3 and India's RDSS.


By Installation

Segment Metric Primary Demand Driver
Indoor USD 25.47 Billion (2025) Urban land scarcity and environmental protection
Outdoor 42.8% share (2025) Rural feeders and industrial yard installations


The Indoor installation segment commands substantial value, valued at USD 25.47 Billion in 2025, primarily driven by urban land scarcity and environmental protection needs. Conversely, the Outdoor segment captures a dominating 42.8% share in 2025, propelled by rural feeders and industrial yard installations. Policy frameworks supporting these grid upgrades include international distribution schemes and climate mandates.


By End-User

End-user mix in the Medium Voltage Switchgear Market is shifting from a utility monoculture toward a broader buyer base.

Segment Metric Primary Demand Driver
Utilities 41.8% share (2025) Network modernisation and reliability mandates
Industrial USD 12.31 Billion (2025) Process plant expansion and electrification of heat
Commercial 17.3% share (2025) Data centres, hospitals and campus infrastructure
Residential 7.7% CAGR (2026–2035) Rooftop solar, storage and neighbourhood microgrids


Based on the provided end-user table, the Utilities segment dominates the market with a 41.8% share in 2025, driven by network modernization and reliability mandates. Meanwhile, the Residential segment emerges as the fastest-growing sector, registering a 7.7% CAGR (2026–2035) fueled by rooftop solar, storage, and neighborhood microgrids. Relevant policy frameworks supporting these investments include distribution modernization schemes and renewable integration rules.


Regional Market Share Analysis

Region Metric (2025 unless noted) Primary Investment Themes
North America USD 9.62 Billion Data centre interconnection, resilience hardening, IRA-linked upgrades
Europe 22.4% share F-Gas compliance replacement, offshore wind onshore infrastructure
Asia-Pacific 43.1% share Distribution loss reduction, urban substations, manufacturing capacity
South America 6.1% CAGR (2026–2035) Renewable interconnection, transmission auctions
Middle East & Africa USD 3.38 Billion Grid diversification, desalination, industrial cities
Total USD 44.53 Billion

Regional demand in the Medium Voltage Switchgear Market splits along two lines: replacement-driven mature grids and capacity-driven emerging grids. The former buys on compliance and reliability metrics, the latter on cost and availability.


North America

Country Metric Key Driver
US 74.6% of regional revenue Hyperscale campus interconnection and GRIP-funded hardening
Canada USD 1.21 Billion Hydro utility asset renewal in Quebec and British Columbia
Mexico 6.4% CAGR (2026–2035) Nearshoring industrial parks and CFE distribution upgrades


FERC Order No. 1920 obliges transmission providers to conduct long-term regional planning on a 20-year horizon, and the downstream distribution reinforcement that follows lands squarely on medium-voltage equipment budgets [22]. Utility integrated resource plans filed across PJM and ERCOT territories in 2025 collectively identify substation capacity as the leading interconnection constraint.

Europe

Country Metric Key Driver
Germany 21.8% of regional revenue Netzausbau distribution reinforcement and heat-pump load growth
UK USD 1.42 Billion RIIO-3 allowances and offshore wind onshore connections
France 12.9% of regional revenue Enedis feeder renewal and nuclear-adjacent distribution works
Italy 5.4% CAGR (2026–2035) Rooftop solar interconnection under Superbonus successor schemes
Spain USD 0.81 Billion Iberian solar corridor and electrolyser projects
Nordic Countries 6.6% CAGR (2026–2035) Data centre siting and industrial electrification
Russia 5.9% of regional revenue Domestic substitution of imported equipment
Rest of Europe USD 1.16 Billion Central and Eastern European network modernisation


Brussels published its EU Action Plan for Grids in late 2023, identifying EUR 584 billion of network investment need through 2030 [7]. Compliance deadlines rather than load growth set the replacement pace here, which produces unusually predictable order flow for suppliers with certified alternative-insulation portfolios.

Asia-Pacific

Country Metric Key Driver
China 46.2% of regional revenue State Grid distribution capex and industrial park build-out
India 8.4% CAGR (2026–2035) Revamped Distribution Sector Scheme loss-reduction works
Japan USD 2.11 Billion Post-liberalisation network renewal and resilience upgrades
South Korea 7.9% of regional revenue Semiconductor fab clusters and offshore wind landings
ASEAN 7.6% CAGR (2026–2035) Electrification of secondary cities and manufacturing relocation
Rest of Asia-Pacific USD 1.34 Billion Australian distributed energy integration


China's National Energy Administration reported grid investment above CNY 600 billion in 2025, with distribution networks receiving the larger share for the first time in a decade [11]. India's National Electricity Plan for transmission complements that at the state level, and both programmes specify domestic manufacturing content that reshapes supplier competitive positioning [9].

South America

Country Metric Key Driver
Brazil 58.3% of regional revenue ANEEL distribution concession obligations and solar interconnection
Argentina 6.9% CAGR (2026–2035) Vaca Muerta industrial load and grid stabilisation
Rest of South America USD 0.61 Billion Chilean and Colombian renewable connection queues


Brazilian distribution concessions carry contractual quality-of-supply penalties, which convert reliability investment from discretionary to mandatory. Auction-based transmission procurement has also created a competitive engineering-procurement-construction contractor base that buys equipment on price-sensitive terms.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 28.7% of regional revenue Giga-project substations and SEC network expansion
UAE USD 0.62 Billion Data centre corridors and desalination plant loads
South Africa 6.2% CAGR (2026–2035) Eskom distribution refurbishment and private wheeling
Egypt 9.4% of regional revenue New administrative capital and interconnector projects
Rest of MEA USD 0.94 Billion Sub-Saharan electrification programmes


Saudi Electricity Company's capital programme prioritises network capacity ahead of NEOM and Red Sea development milestones [24]. Elsewhere in the region, funding availability rather than demand determines execution speed, and multilateral development finance remains the deciding variable.


Medium Voltage Switchgear Market By Region, 2025-2035

Competitive Benchmarking

Concentration sits in the moderate band. The top five suppliers account for an estimated 46–52% of global revenue, producing an approximate HHI in the 750–900 range. A long tail of regional panel builders serves local content requirements in India, China, Brazil and the Gulf, which keeps the aggregate structure fragmented even as the premium tier consolidates around a handful of vertically integrated groups.

Company Est. Revenue Share Range Key Offerings for Medium Voltage Switchgear Market Strategic Positioning
ABB Ltd. ~11–14% Primary and secondary distribution panels, retrofit kits Broadest installed base; early alternative-gas portfolio
Schneider Electric SE ~10–13% Compact secondary units, shielded solid-insulation systems Digital services depth and channel reach
Siemens Smart Infrastructure ~9–12% Clean-air primary switchgear, protection relays Strong European utility framework agreements
Hitachi Energy ~7–10% Gas-insulated and eco-efficient assemblies Transmission adjacency and grid integration expertise
Eaton Corporation plc ~5–8% Metal-clad and pad-mounted equipment North American distribution channel strength
GE Vernova ~4–7% Protection and control, hybrid assemblies Grid automation software integration
Mitsubishi Electric Corporation ~3–6% Vacuum circuit breakers, cubicle systems Asian utility relationships and reliability record
Toshiba Energy Systems ~2–5% Solid-insulated switchgear Japanese domestic base with export expansion
Ormazabal (Velatia) ~2–4% Secondary distribution and compact substations European utility specialist with custom engineering
CG Power and Industrial Solutions ~1–3% Indoor and outdoor panels for emerging grids Cost-competitive Indian manufacturing footprint
Powell Industries ~1–3% Custom-engineered assemblies and e-houses Oil, gas and petrochemical project focus
Lucy Electric ~1–3% Automated secondary distribution units Distribution automation niche leadership


Recent News & Developments

  • Schneider Electric (March 2023): Expanded its shielded solid-insulation product family to cover 24 kV ratings, targeting European utilities preparing for prohibition deadlines [17]
  • European Commission (February 2024): Adopted Regulation (EU) 2024/573, establishing staged bans on fluorinated-gas equipment across voltage classes and locking in a decade of replacement demand [6]
  • Hitachi Energy (June 2024): Announced a multi-year capacity expansion across its transformer and switchgear plants, citing order backlogs stretching beyond two years [20]
  • FERC (May 2024): Issued Order No. 1920 mandating long-term regional transmission planning, with downstream implications for distribution reinforcement budgets [22]
  • Siemens (September 2024): Secured a framework agreement with a European distribution system operator for clean-air primary equipment covering multiple national networks [18]
  • Eaton (January 2025): Opened expanded North American production capacity dedicated to data centre power distribution assemblies [19]
  • ABB (April 2025): Launched an extended retrofit programme allowing breaker and relay replacement inside legacy cubicles without civil modification [16]
  • Ministry of Power, India (August 2025): Reported cumulative disbursement milestones under the Revamped Distribution Sector Scheme, accelerating state-level equipment tenders [10]


Medium Voltage Switchgear Market Report Scope

Parameter Detail
Market Scope Global Medium Voltage Switchgear Market covering equipment rated above 1 kV and up to 52 kV
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.19% (2026–2035)
Market Size Checkpoints USD 44.53 Billion (2025); USD 46.51 Billion (2026); USD 73.33 Billion (2035)
Fastest Growing Segments Alternative-insulation technologies (11.2% CAGR); Residential end-user (7.7% CAGR); Asia-Pacific (7.3% CAGR)
Companies Profiled ABB, Schneider Electric, Siemens Smart Infrastructure, Hitachi Energy, Eaton, GE Vernova, Mitsubishi Electric, Toshiba Energy Systems, Ormazabal, CG Power, Powell Industries, Lucy Electric
Valuation Currency USD Billion

FAQs

What procurement lead times should buyers plan for in the Medium Voltage Switchgear Market?
Utility-grade panel lead times ran between 60 and 90 weeks through 2025. Place frame orders roughly 18 months ahead of energisation dates, and negotiate breaker and instrument-transformer allocations as separate line items. [13]
How does total cost of ownership compare between SF₆ and SF₆-free designs?
Alternative-insulation units carry a 12–15% capital premium but remove gas handling contracts, leak reporting obligations and end-of-life recovery costs. Lifecycle parity typically arrives around year eight of a thirty-year asset life. [6]
Which testing standards matter most when specifying equipment in the Medium Voltage Switchgear Market?
IEC 62271-200 governs internal arc classification and loss-of-service continuity categories. North American buyers additionally require IEEE C37.20.2 metal-clad qualification, and dual certification adds four to six months to vendor approval cycles. [15]
What integration problems appear when retrofitting digital protection into legacy panels?
Retrofits usually stall on current-transformer accuracy class and cubicle space rather than the relay itself. Budget 15–20% of project cost for auxiliary wiring and validate station-bus timing before commissioning. [14]
How should investors assess aftermarket exposure among suppliers?
Service lines typically deliver 30–40% of vendor operating profit at roughly half the cyclicality of new equipment sales. Favour suppliers with certified retrofit programmes and multi-year utility framework contracts. [16]
Are campus microgrids a credible growth channel in the Medium Voltage Switchgear Market?
Colocation halls and industrial campuses increasingly require 11–33 kV intake assemblies with fast transfer capability. Vendors offering factory-tested modular packages win these tenders on schedule certainty rather than unit price. [25]
Which supply-chain inputs deserve the closest monitoring?
Grain-oriented electrical steel, epoxy insulating resin and vacuum interrupter tube capacity are the binding constraints. Dual-sourcing interrupters and qualifying a second panel builder remain the practical mitigations. [13]    
Author
Author
Author Profile
Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry standards, peer-reviewed engineering journals, technical publications, and authoritative energy organizations. Key sources included the International Electrotechnical Commission (IEC), Institute of Electrical and Electronics Engineers (IEEE), American National Standards Institute (ANSI), National Electrical Manufacturers Association (NEMA), European Committee for Electrotechnical Standardization (CENELEC), US Department of Energy (DOE), International Energy Agency (IEA), US Energy Information Administration (EIA), European Network of Transmission System Operators for Electricity (ENTSO-E), World Bank Energy Data Portal, International Renewable Energy Agency (IRENA), Power Grid Corporation of India (PGCIL), China Electricity Council (CEC), German Federal Ministry for Economic Affairs and Energy (BMWi), UK Department for Business, Energy & Industrial Strategy (BEIS), and national utility regulatory commission reports from key markets. These sources were used to collect grid infrastructure investment data, regulatory compliance standards, technical safety studies, electrification trends, and competitive landscape analysis for air-insulated switchgear (AIS), gas-insulated switchgear (GIS), ring main units (RMU), and other switchgear technologies.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of engineering, heads of product development, and commercial directors from switchgear manufacturers, component suppliers, and OEMs were examples of supply-side sources. Chief electrical engineers, grid infrastructure managers, procurement leads from electric utilities, power production firms, industrial facilities, renewable energy providers, and EPC contractors were examples of demand-side suppliers. Primary research provided information on smart grid adoption trends, pricing tactics, and procurement dynamics in addition to validating market segmentation and product development schedules.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (32%), Europe (29%), Asia-Pacific (33%), Rest of World (6%)


Market Size Estimation

Global market valuation was derived through revenue mapping and installation volume analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, Middle East, and Latin America

Product mapping across air-insulated switchgear (AIS), gas-insulated switchgear (GIS), ring main units (RMU), and other switchgear categories by voltage rating (1kV-15kV, 15kV-25kV, 25kV-35kV)

Analysis of reported and modeled annual revenues specific to medium voltage switchgear portfolios

Coverage of manufacturers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (installation volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations

This methodology maintains the same rigorous structure while adapting the sources and parameters specifically for the electrical equipment and power infrastructure sector.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.