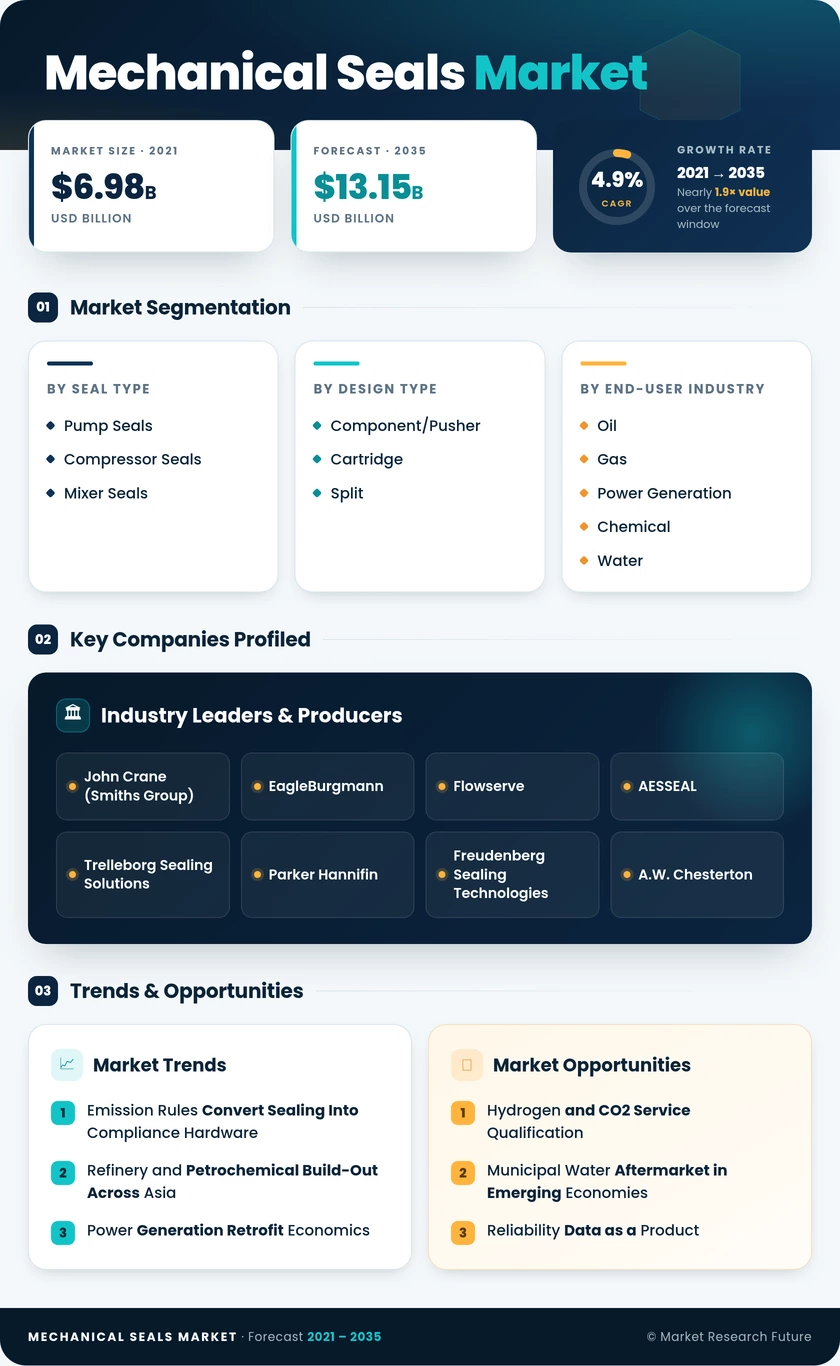
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Seal Type | Pump Seals, Compressor Seals, Mixer Seals | Pump Seals | Compressor Seals |
| By Design Type | Component/Pusher, Cartridge, Split | Cartridge | Component/Pusher |
| By End-User Industry | Oil and Gas, Power Generation, Chemical, Water and Waste-Water, Other End-User Industries | Oil and Gas | Power Generation |
| By Geography | Asia-Pacific, North America, Europe, South America, Middle-East and Africa | Asia-Pacific | Asia-Pacific |
Market Segmentation Overview
By Seal Type
| Sub-Segment | Key Trend |
| Pump Seals | Steady replacement demand from the centrifugal pump installed base; mix shifting toward pre-set assemblies |
| Compressor Seals | Gas-lubricated arrangements gaining share as LNG, hydrogen and CO2 compression duties expand |
| Mixer Seals | Hygienic and containment-rated designs growing with pharmaceutical and specialty chemical capacity |
Seal type economics split cleanly between volume and value. Pump seals deliver the recurring revenue base, while compressor seals concentrate engineering margin in a comparatively small number of critical machines.
By Design Type
| Sub-Segment | Key Trend |
| Component/Pusher | Retains OEM first-fill volume on standard duties; faces sharpest price competition |
| Cartridge | Preferred format for reliability-driven buyers; eliminates field setting error |
| Split | Expanding in large municipal and industrial pumps where disassembly is impractical |
Design preference tracks workforce capability as much as technical requirement. As experienced fitters retire, pre-engineered formats that remove installation judgement continue to take share from loose component arrangements.
By End-User Industry
| Sub-Segment | Key Trend |
| Oil and Gas | Largest revenue pool; upgrade cycle driven by emission compliance and standard revisions |
| Power Generation | Fastest expansion on turbine retrofits and flexible generation commissioning |
| Chemical | Containment and exposure rules favour dual-pressurised arrangements |
| Water and Waste-Water | Rehabilitation spending outpacing new-build capacity additions |
| Other End-User Industries | Mining, pulp and paper, and food processing provide diversification ballast |
End-user rotation is gradually reducing dependence on hydrocarbon capex cycles. Power and water demand follow regulated investment programmes, which improves revenue predictability for suppliers with balanced portfolios.
By Geography
| Sub-Segment | Key Trend |
| Asia-Pacific | Project-led growth from refining, petrochemical and power capacity additions |
| North America | Compliance-driven upgrades plus the densest aftermarket service network |
| Europe | Plant life extension, hydrogen readiness and emission documentation requirements |
| South America | Offshore production systems and mining pumping anchor demand |
| Middle-East and Africa | Gas processing, desalination and local content mandates shape sourcing |
Geographic strategy now hinges on channel structure rather than product range. Winning suppliers pair global engineering capability with regional assembly and repair footprints close to the installed base.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA