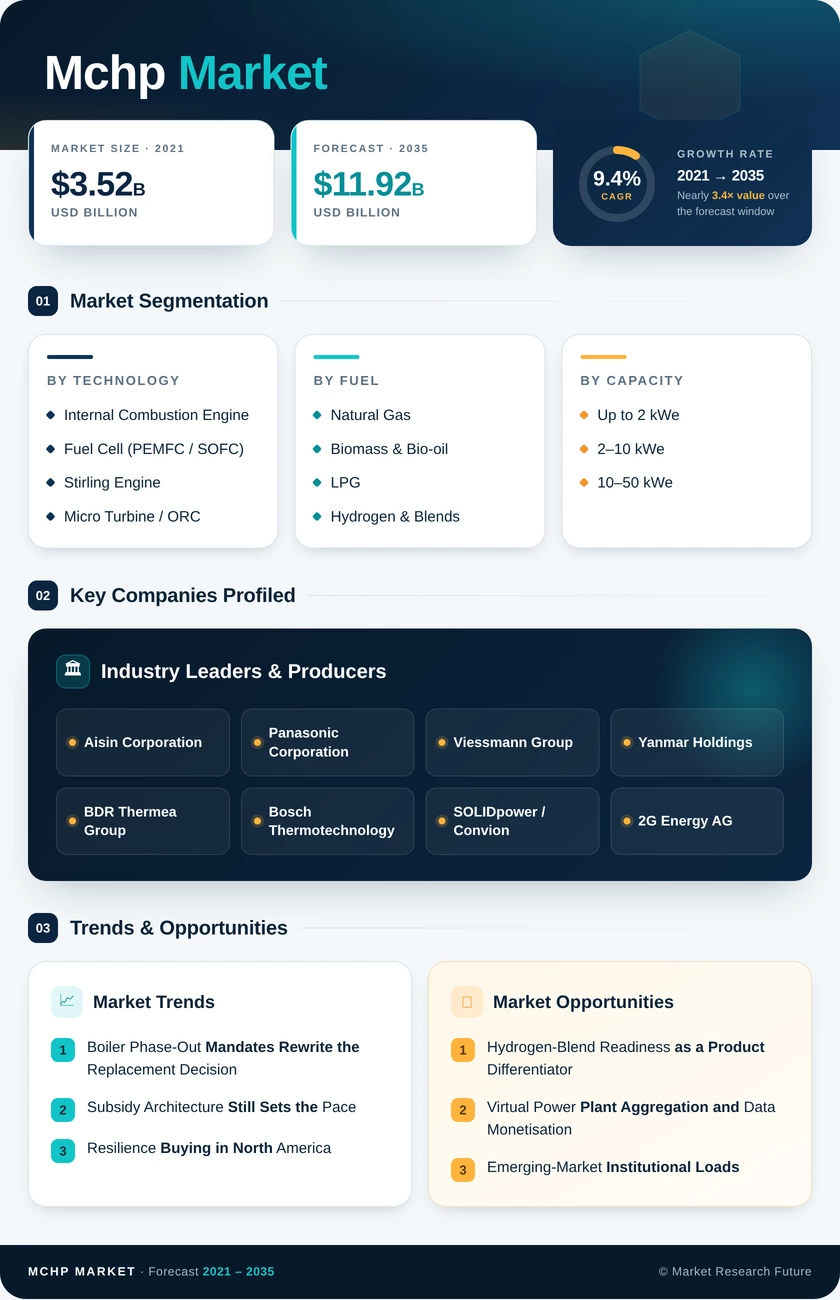
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Technology | Internal Combustion Engine; Fuel Cell (PEMFC / SOFC); Stirling Engine; Micro Turbine / ORC | Internal Combustion Engine | Fuel Cell (PEMFC / SOFC) |
| By Fuel | Natural Gas; Biomass & Bio-oil; LPG; Hydrogen & Blends | Natural Gas | Hydrogen & Blends |
| By Capacity | Up to 2 kWe; 2–10 kWe; 10–50 kWe | 2–10 kWe | 10–50 kWe |
| By End User | Residential; Commercial; Light Industrial & Institutional | Residential | Commercial |
| By Region | Europe; North America; Asia-Pacific; South America; Middle East & Africa | Europe | Asia-Pacific |
Market Segmentation Overview
By Technology
| Sub-Segment | Key Trend |
| Internal Combustion Engine | Service-network depth and low capital cost sustain volume leadership |
| Fuel Cell (PEMFC / SOFC) | Stack cost decline and subsidy support drive premium-tier revenue |
| Stirling Engine | Low noise and fuel tolerance secure retrofit and off-grid niches |
| Micro Turbine / ORC | Waste-heat recovery and biomass pairings define the addressable pocket. |
Technology choice is increasingly decided by building vintage rather than buyer preference — engines for high-runtime commercial loads, fuel cells where electrical efficiency and emissions reporting matter, Stirling machines where installation constraints rule out vibration.
By Fuel
| Sub-Segment | Key Trend |
| Natural Gas | Existing distribution infrastructure keeps installation cost low |
| Biomass & Bio-oil | Agro-industrial and rural sites with on-site feedstock |
| LPG | Off-grid residential and rural commercial applications |
| Hydrogen & Blends | Certification requirements arriving ahead of supply volumes |
Fuel strategy has become a hedging exercise. Manufacturers ship gas-fired hardware today while certifying the same platforms for blends, protecting installed-base value against a policy shift they cannot time precisely.
By Capacity
| Sub-Segment | Key Trend |
| Up to 2 kWe | Single-family housing, tightly coupled to subsidy availability |
| 2–10 kWe | Multi-family and small commercial; best capital-to-runtime ratio |
| 10–50 kWe | Hotels, care homes and light industry; fastest institutional uptake |
Capacity banding maps almost exactly onto permitting thresholds, which is why the 2–10 kWe class carries the largest revenue pool — it clears simplified interconnection in most jurisdictions while serving buildings with meaningful year-round heat demand.
By End User
| Sub-Segment | Key Trend |
| Residential | Boiler replacement cycle and grant eligibility set the pace |
| Commercial | Resilience economics and continuous occupancy drive adoption |
| Light Industrial & Institutional | Process heat and critical-load protection anchor demand |
End-user mix is rebalancing toward commercial and institutional buyers, whose investment cases rest on outage avoidance and operational continuity rather than on grant schemes that can change with an election cycle.
.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA