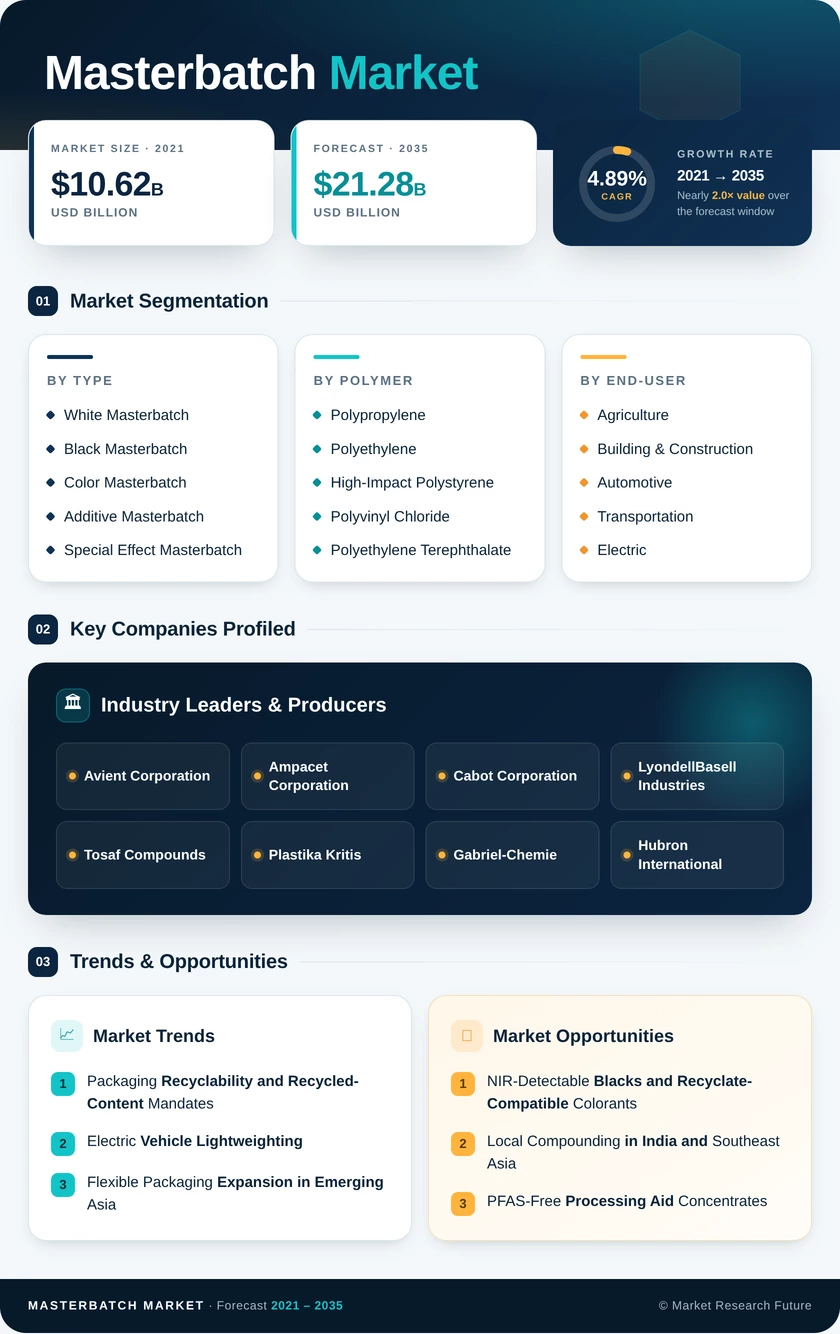
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Type | White Masterbatch, Black Masterbatch, Color Masterbatch, Additive Masterbatch, Special Effect Masterbatch | White Masterbatch (34.7% share) | Color Masterbatch (5.2% CAGR) |
| By Polymer | Polypropylene, Polyethylene, High-Impact Polystyrene, Polyvinyl Chloride, Polyethylene Terephthalate, Others | Polyethylene (45.5% share) | Polypropylene (5.5% CAGR) |
| By End-user | Agriculture, Building & Construction, Automotive and Transportation, Electric and Electronics, Packaging, Others | Packaging (32.4% share) | Automotive and Transportation (5.6% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific (48.5% share) | Middle East & Africa (5.7% CAGR) |
Market Segmentation Overview
By Type
| Sub-Segment | Key Trend |
|---|---|
| White Masterbatch | Hybrid pigment blends reduce titanium dioxide dependence |
| Black Masterbatch | NIR-detectable grades replace conventional carbon black in packaging. |
| Color Masterbatch | Shade proliferation driven by private label and brand refreshes |
| Additive Masterbatch | Multifunctional pellets stabilize recycled resin. |
| Special Effect Masterbatch | Metallic and pearlescent finishes replace painting in interiors. |
White Masterbatch leads this dimension with a 34.7% share because film, bottle and medical packaging cannot achieve opacity without titanium dioxide. Color Masterbatch grows fastest at a 5.2% CAGR as brand owners and retailers multiply shades and shorten runs. Black Masterbatch faces a packaging-specific shift toward NIR-detectable formulations, while its pipe and agricultural uses remain stable.
By Polymer
| Sub-Segment | Key Trend |
|---|---|
| Polypropylene | EV interior and hot-fill packaging adoption |
| Polyethylene | Mono-material film designs for recyclability |
| High-Impact Polystyrene | Gradual substitution by polypropylene in appliances |
| Polyvinyl Chloride | Lead-free stabilizer systems for long-life profiles |
| Polyethylene Terephthalate | Toners for recycled bottle content |
| Others | Bio-based and engineering carriers in niche uses |
Polyethylene holds a 45.5% share as the default carrier for film extrusion, blow molding and rotomolding. Polypropylene posts the fastest 5.5% CAGR because automakers shift interior and under-hood parts to it to save weight, and hot-fill containers need its heat resistance. High-Impact Polystyrene continues to lose appliance applications to polypropylene as price gaps narrow.
By End-user
| Sub-Segment | Key Trend |
|---|---|
| Agriculture | Longer-life mulch and silage films |
| Building & Construction | Weatherable grades for pipes and profiles |
| Automotive and Transportation | Recycled-content and lightweight polypropylene parts |
| Electric and Electronics | Halogen-free flame retardants meeting UL 94 V-0 |
| Packaging | Recyclate-compatible colors and closure redesign |
| Others | Traceability-driven healthcare and consumer grades |
Packaging remains the largest end use with a 32.4% share, driven by flexible film, rigid containers and closures that must now meet recyclability rules. Automotive and Transportation is the fastest-growing end use at a 5.6% CAGR, supported by electric vehicle platforms and proposed EU recycled plastic requirements for new vehicles. Electric and Electronics adds value through halogen-free flame-retardant grades rather than volume.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA