Lithium Market (2026 - 2035)

Lithium Market Research Report Information By Compound (Carbonate, Hydroxide, Chloride, and Other Compounds), By Application (Battery, Lubricants & Grease, Air Treatment, and Other Applications), By End-User Industry (Automotive, Industrial, Consumer Electronics, Energy Storage, Medical, and Other End Users) – Forecast Till 2035.
ID: MRFR/CnM/6558-HCR 111 Pages Chitranshi Jaiswal Last Updated: August 24, 2026
Lithium Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)17.8%
2025 Market SizeUSD 9,200 Million
2035 Market SizeUSD 47,340 Million
Key Players
Albemarle Corporation
SQM
Ganfeng Lithium
Tianqi Lithium
Arcadium Lithium
Pilbara Minerals
Opportunities
  • Closed-Loop Battery Recycling
  • Emerging-Market Electrification in Africa and Southeast Asia
  • Digital Traceability and ESG Certification Premiums

Lithium Market Summary

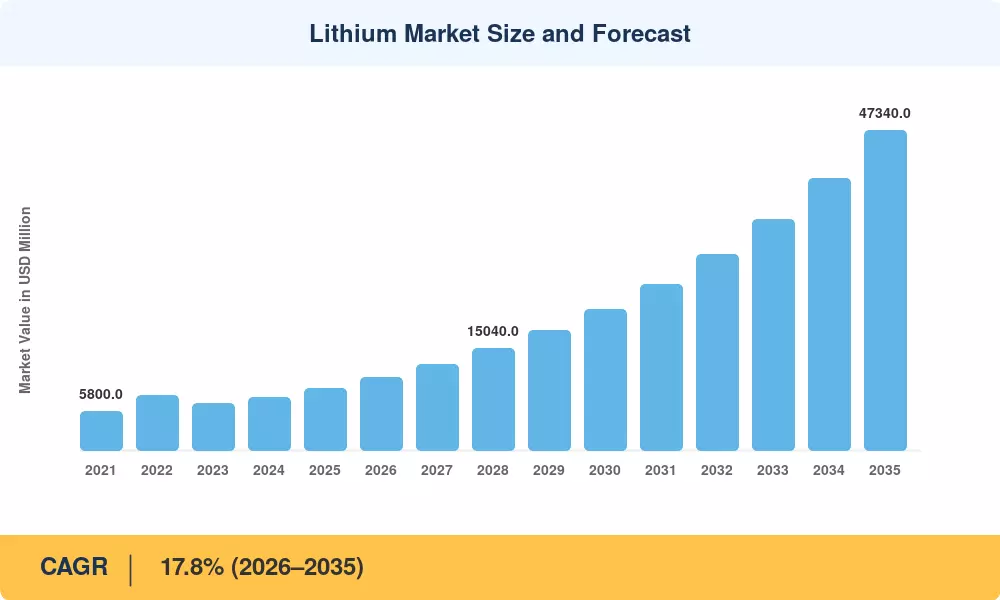
The global Lithium Market reached an estimated USD 9,200 Million in 2025 and is projected to grow from USD 10,840 Million in 2026 to USD 47,340 Million by 2035, registering a compound annual growth rate of 17.8% across the forecast period. Two catalysts are reshaping the competitive landscape: the European Union's tightening CO₂ fleet emission standards (which mandate a 55% reduction by 2030 relative to 2021 baselines) and the U.S. Inflation Reduction Act's domestic content requirements that channel over USD 7 billion in tax credits toward qualified mineral processing [1][2]. Together, these policies are pulling raw-material supply chains closer to end-market demand and accelerating mine-to-cathode investments.

The underlying technology transformation centers on replacing conventional nickel-manganese-cobalt cathode chemistries with lithium-iron-phosphate and high-nickel formulations that shift the bottleneck toward lithium feedstock. Battery-pack costs dropped below the USD 110 per kilowatt-hour threshold in 2025, triggering a wave of multi-year off-take agreements between automakers and upstream producers [3]. Direct-lithium-extraction technology is simultaneously shortening project timelines from seven years to under three, opening previously uneconomic brine resources in Argentina, the United States, and Germany [4].

Asia-Pacific dominated the Lithium Market with approximately 60.5% of global revenue in 2025, anchored by China's integrated refining-to-cell manufacturing corridor. North America is the fastest-growing region, advancing at a projected 23.8% CAGR through 2035, driven by IRA incentives and gigafactory build-outs across the U.S. Southeast [5]. Europe held the second-largest share at roughly 16.3%, propelled by the EU Critical Raw Materials Act and emerging refinery projects in Finland and Poland. As the decade unfolds, the Lithium Market is expected to undergo structural shifts in pricing, contract design, and geographic diversification that will redefine competitive positioning.


Key Report Takeaways

• By Compound

  • Carbonate accounted for roughly 69% of the Lithium Market in 2025, supported by its dominance in lithium-iron-phosphate cell production.
  • Hydroxide is forecast to expand at a 21.2% CAGR through 2035, reflecting the transition toward high-nickel cathode chemistries.
  • Chloride and other compounds combined represented less than 8% of the total volume, serving niche pharmaceutical and metallurgical applications.

• By Application

  • The battery segment captured approximately 73.5% of the Lithium Market share in 2025.
  • Lubricants and grease applications contributed a 19.5% CAGR through the forecast period.

• By End-User Industry

  • Automotive held around 47% of the Lithium Market revenue in 2025, reflecting accelerating EV adoption mandates globally.
  • The consumer electronics segment is projected to register a 16.8% CAGR through 2035.

• By Region

  • Asia-Pacific dominated the Lithium Market with a 60.5% share in 2025.
  • North America is the fastest-growing region at a 23.8% CAGR through 2035.


Lithium Market Size and Forecast (2021–2035)

Market Research Future's proprietary estimation framework integrates upstream mine output data, midstream refining-capacity trackers, downstream cell-manufacturing procurement disclosures, and regulatory filings across 42 countries. Historical figures (2021–2024) rely on audited company reports and trade-flow databases; forecast projections (2026–2035) are generated through scenario modeling calibrated against IEA, BloombergNEF, and supply-demand balances [6][7].
Lithium Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
EV adoption mandates & fleet-emission regulations ~28% Global Short-term (≤2 yr)
Utility-scale storage deployment (4-hour systems) ~18% North America, Europe Medium-term (2–4 yr)
IRA & CRMA mineral-processing incentives ~16% North America, Europe Short-term (≤2 yr)
Direct-lithium-extraction commercialization ~14% South America, North America Medium-term (2–4 yr)
Solid-state & silicon-anode cell R&D ~10% Asia-Pacific, North America Long-term (≥4 yr)
Consumer electronics battery densification ~8% Asia-Pacific Medium-term (2–4 yr)
Aerospace & defense electrification ~6% North America, Europe Long-term (≥4 yr)


EV Adoption Mandates and Fleet-Emission Regulations

The EU's "Fit for 55" package requires new passenger cars to achieve zero tailpipe emissions by 2035, effectively mandating full battery-electric fleets across 27 member states [2]. China's dual-credit policy has driven new-energy-vehicle penetration past 38% in 2024, and the U.S. EPA's multi-pollutant rule projects 56% BEV share of new light-duty sales by 2032 [1]. These overlapping mandates create a demand floor for the Lithium Market that insulates consumption from short-term price volatility.

Utility-Scale Storage Deployment

California's AB 2514 and the broader FERC Order 2222 framework have catalyzed over 25 GW of grid-connected storage in the United States by 2025, with four-hour-duration systems increasingly specified for resource-adequacy compliance [12]. Each gigawatt-hour of deployed storage requires approximately 750 tonnes of lithium carbonate equivalent, directly linking utility procurement cycles to the Lithium Market growth trajectory.

IRA and CRMA Mineral-Processing Incentives

The Inflation Reduction Act allocates USD 7.1 billion in advanced manufacturing production credits (Section 45X) for domestically refined critical minerals, while the EU Critical Raw Materials Act targets 40% of processing within Europe by 2030 [1][2]. These policies are relocating refining capacity from China to allied jurisdictions and reshaping the Lithium Market supply chain.

Direct-Lithium-Extraction Commercialization

Pilot-scale DLE operations in Argentina's Salta province and Nevada's Clayton Valley have demonstrated recovery rates above 90% with water consumption 80% below conventional evaporation ponds [4]. With project lead times compressed to under three years, DLE has the potential to unlock an estimated 12 million tonnes of previously uneconomic resources, structurally expanding the Lithium Market supply base by the early 2030s.


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Periodic oversupply and spot-price volatility ~−22% Global Short-term (≤2 yr)
Environmental permitting & water-use restrictions ~−20% South America, Australia Medium-term (2–4 yr)
Geopolitical concentration of refining capacity ~−18% Asia-Pacific Medium-term (2–4 yr)
Sodium-ion battery substitution risk ~−15% Asia-Pacific Long-term (≥4 yr)
High capital intensity of greenfield projects ~−12% Global Long-term (≥4 yr)


Periodic Oversupply and Spot-Price Volatility

From 2023 to 2025, Tier-2 Chinese converters increased their refining capacity by ~40%, exceeding upstream mine supply and pushing spot prices below USD 10,000 / tonne of lithium carbonate equivalent [8]. The margin squeeze that followed caused high-cost Australian spodumene producers to cut back production, generating a boom-bust cycle that deters long-term capital commitment in the Lithium Market.


Environmental Permitting and Water-Use Restrictions

Chile’s new concession framework mandates impact evaluations on indigenous water rights, adding 18–24 months to project deadlines in the Atacama area [17]. Hard-rock mine tailings management is also subject to the same level of scrutiny under Australia’s Environment Protection and Biodiversity Conservation Act. These regulatory constraints are slowing the speed at which new supply enters the Lithium Market, even as demand grows.


Geopolitical Concentration of Refining

China processed approximately 65% of the world's lithium chemicals in 2024, creating a single-point-of-failure risk that OEMs and governments are actively working to mitigate through reshoring incentives [18]. Until Western refining capacity reaches meaningful scale—projected after 2028—the Lithium Market remains vulnerable to trade-policy disruptions.


Lithium Market Opportunities

Closed-Loop Battery Recycling

The EU Battery Regulation sets minimum recycled-content levels of 6% lithium by 2030 and 12% by 2035, providing a secondary feedstock pathway that minimizes reliance on primary extraction [21]. Companies investing in hydrometallurgical recycling facilities could gain margin in the Lithium Market when scrap volumes from first-generation EV batteries reach critical mass.


Emerging-Market Electrification in Africa and Southeast Asia

The USD 1.5 billion of World Bank climate-financing pledges to Sub-Saharan Africa to support the two- and three-wheeler electrification schemes could create a new demand tier for small-format lithium-iron-phosphate cells [22]. This is a geographic whitespace opportunity for the Lithium Market outside of the established automotive corridors.


Digital Traceability and ESG Certification Premiums

Blockchain-based mineral-traceability platforms are enabling mine-to-cell provenance tracking, allowing responsibly sourced material to command a 5–8% premium on contract markets [23]. Producers who embed digital ESG certification into their offtake agreements will differentiate within the Lithium Market as downstream OEMs face regulatory reporting obligations under the EU Corporate Sustainability Due Diligence Directive.

Solid-State Battery Commercialization

Toyota, Samsung SDI, and QuantumScape have announced pre-production timelines for solid-state cells between 2027 and 2029, each requiring lithium-metal anodes that increase per-cell lithium intensity by 30–40% relative to conventional liquid-electrolyte designs [13]. Successful commercialization would create a step-change in per-vehicle lithium demand and open a premium segment within the Lithium Market.

Integrated Mine-to-Cathode Business Models

Vertical integration—from brine or spodumene extraction through conversion and precursor manufacturing—can compress margins from four separate value-chain participants into one. Albemarle's Kings Mountain project and Ganfeng's Argentina operations exemplify this model, which is reshaping competitive positioning across the Lithium Market.


Lithium Market Future Outlook

AI-Optimized Extraction and Processing

Machine-learning algorithms are being deployed across brine-field management and spodumene flotation circuits to optimize recovery rates and reduce reagent consumption by up to 15% [24]. As predictive-maintenance platforms mature, the Lithium Market will benefit from lower unit production costs and faster ramp-up curves for greenfield operations.

Platform Economics and Digital Commodity Trading

Digital spot-trading platforms such as Metalshub and Fastmarkets' lithium price-assessment service are improving price transparency, shifting the Lithium Market from opaque bilateral negotiations toward standardized, exchange-traded contracts. The CME Group launched lithium hydroxide futures in 2023, and open interest has grown 340% through early 2025, signaling institutional acceptance [25].

Electrification Supercycle Alignment

The IEA projects global EV sales will surpass 45 million units annually by 2030, requiring approximately 2.5 million tonnes of lithium carbonate equivalent—nearly double 2025 consumption levels [6]. Grid-storage additions are expected to contribute another 600,000 tonnes by 2032. This dual-demand pull anchors the Lithium Market growth thesis through the mid-2030s.

ESG Reporting and Supply-Chain Decarbonization

Scope 3 emission disclosures under the EU Corporate Sustainability Reporting Directive and the SEC's proposed climate-risk rules are compelling automakers to quantify—and reduce—the carbon intensity of their mineral supply chains [23]. Producers offering verified low-carbon lithium (below 5 tonnes CO₂e per tonne of LCE) will command pricing premiums and preferred-supplier status in the Lithium Market.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
Asia-Pacific 60.5% share (2025) Cell manufacturing, refining integration
North America 23.8% CAGR (2026–2035) IRA incentives, DLE projects, gigafactories
Europe 16.3% share (2025) CRMA compliance, refinery build-outs
South America USD 1,290 Million (2025) Brine extraction, DLE pilots
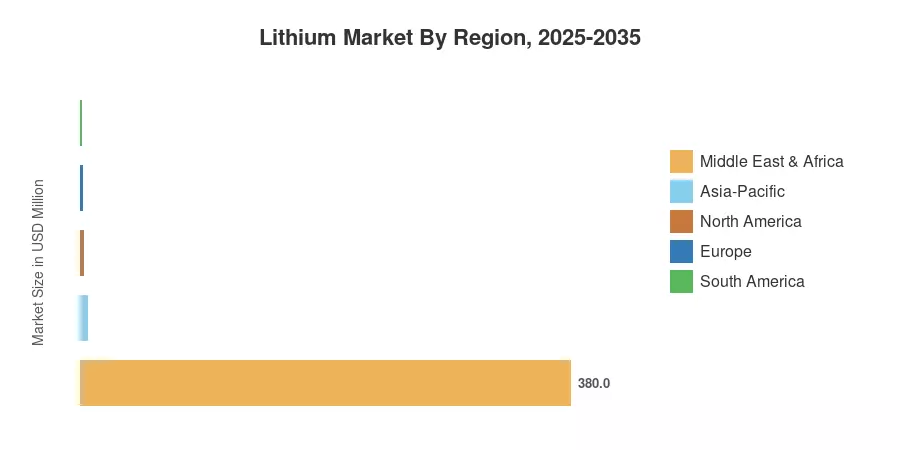
Middle East & Africa USD 380 Million (2025) Mining exploration, off-grid storage
Total USD 9,200 Million (2025)

The Lithium Market exhibits distinct regional demand profiles shaped by policy frameworks, manufacturing infrastructure, and resource endowments. Asia-Pacific leads in absolute consumption, North America is accelerating fastest, and South America anchors supply-side growth.


North America

Country Key Metric Key Driver
US 78% of regional share IRA Section 45X credits, gigafactory clusters
Canada 15.2% CAGR Ontario refinery investments, Quebec spodumene
Mexico USD 95 Million (2025) Nearshoring of cathode-material plants


The United States dominates North America's Lithium Market presence, with over 15 announced gigafactory projects in Tennessee, Georgia, and Nevada collectively requiring an estimated 280,000 tonnes of lithium carbonate equivalent annually by 2030 [5]. Canada's federal Critical Minerals Strategy has committed CAD 3.8 billion to domestic processing, while Mexico's nascent role focuses on cathode-material assembly linked to cross-border automotive supply chains [10].

Europe

Country Key Metric Key Driver
Germany 31% of regional share Automotive OEM procurement, BASF cathode plants
UK 12.6% CAGR Britishvolt successor projects, Cornish lithium
France USD 185 Million (2025) Renault-Envision AESC partnership
Italy 10.4% CAGR Stellantis Termoli gigafactory
Spain USD 110 Million (2025) Extremadura mining concessions
Nordic Countries 14.8% CAGR Northvolt expansion, Finnish refining
Russia USD 65 Million (2025) Domestic spodumene development
Rest of Europe 9.7% CAGR Poland, Czech Republic cell-assembly growth


Asia-Pacific

Country Key Metric Key Driver
China 72% of regional share Integrated refining-to-cell supply chain
India 26.1% CAGR PLI scheme for advanced chemistry cells
Japan USD 420 Million (2025) Solid-state R&D, Panasonic partnerships
South Korea 18.3% CAGR LG, Samsung SDI cathode expansion
ASEAN USD 195 Million (2025) Indonesia nickel-lithium co-processing
Rest of Asia-Pacific 15.6% CAGR Australia mine output, emerging processors


China's refining dominance underpins the Asia-Pacific Lithium Market, with Jiangxi and Sichuan provinces hosting over 60% of global conversion capacity [18]. India's Production-Linked Incentive scheme has attracted USD 6.2 billion in committed investment for advanced cell manufacturing, creating upstream pull for lithium chemicals [15]. Japan and South Korea remain technology leaders in high-nickel cathode design, sustaining premium-grade hydroxide demand.

South America

Country Key Metric Key Driver
Argentina 44% of regional share Salta and Jujuy brine projects, DLE adoption
Brazil 19.7% CAGR Grota do Cirilo spodumene mine
Rest of South America USD 210 Million (2025) Bolivia state-led extraction, Chile policy reform


Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 21.4% CAGR NEOM-linked storage procurement
UAE USD 55 Million (2025) Battery import hub, recycling pilots
South Africa 16.9% CAGR Cape Town lithium exploration, renewable pairing
Egypt USD 28 Million (2025) Off-grid solar-storage installations
Rest of MEA 14.2% CAGR Zimbabwe & DRC spodumene exploration


Lithium Market By Region, 2025-2035

Lithium Market Segmentation

By Compound

Segment Key Metric Primary Demand Driver
Carbonate 69% share (2025) LFP cathode prevalence in standard-range EVs
Hydroxide 21.2% CAGR (2026–2035) High-nickel NMC/NCA cathode adoption
Chloride USD 310 Million (2025) Aluminum smelting flux, pharmaceutical inputs
Other Compounds 11.8% CAGR (2026–2035) Specialty glass, ceramic, and polymer additives


Carbonate remains the workhorse of the Lithium Market, driven by the global proliferation of lithium-iron-phosphate cells that now account for over 40% of EV battery installations worldwide. Chinese cell manufacturers have standardized around carbonate-based precursors, creating a self-reinforcing demand cycle tied to the world's largest EV market. Hydroxide, however, is the faster-growing compound segment as Western and South Korean cell producers scale high-nickel formulations for premium vehicles requiring energy densities above 250 Wh/kg. Automakers such as BMW and Mercedes-Benz have structured hydroxide-specific offtake agreements extending beyond 2030, locking in supply at formula-based pricing linked to spodumene concentrate indices [13].

By Application

Segment Key Metric Primary Demand Driver
Battery 73.5% share (2025) EV, grid storage, consumer electronics cells
Lubricants & Grease USD 680 Million (2025) Industrial machinery, aerospace greases
Air Treatment 13.4% CAGR (2026–2035) HVAC absorption chillers, CO₂ scrubbing
Other Applications USD 295 Million (2025) Continuous casting, polymer catalysis


The battery application dominates the Lithium Market because cell demand spans three reinforcing verticals—automotive, stationary storage, and portable electronics. As pack-level costs continue declining, second-life battery deployments and behind-the-meter commercial installations create additional pull on primary lithium procurement.

By End-User Industry

Segment Key Metric Primary Demand Driver
Automotive 47% share (2025) BEV and PHEV production ramp
Industrial USD 1,150 Million (2025) Metallurgical, ceramic, and glass applications
Consumer Electronics 16.8% CAGR (2026–2035) Smartphone, laptop, wearable battery densification
Energy Storage 22.4% CAGR (2026–2035) Utility and C&I grid-connected systems
Medical USD 190 Million (2025) Implantable device batteries, psychiatric pharmaceuticals
Other End Users 14.1% CAGR (2026–2035) Aerospace, defense, marine propulsion


The automotive end-user segment is the largest within the Lithium Market, reflecting the industry's shift from internal-combustion powertrains to full-electric architectures across passenger, commercial, and two-wheeler categories. Energy storage is the fastest-growing end-user segment, propelled by regulatory mandates for four-hour-duration resources in California, Australia, and the UK [12].


Competitive Benchmarking

The Lithium Market exhibits high concentration, with the top five producers accounting for an estimated 55–60% of global refined lithium output. The Herfindahl-Hirschman Index sits in the moderately concentrated range (~1,800–2,200), reflecting a handful of vertically integrated majors alongside a growing tail of mid-cap developers. Strategic consolidation accelerated in 2023–2024 through the Allkem-Livent merger (creating Arcadium Lithium) and Albemarle's expansion of its Kemerton hydroxide refinery [9][20].

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Albemarle Corporation ~14–17% Battery-grade carbonate, hydroxide, spodumene Vertically integrated; U.S. & Australia operations
SQM ~11–14% Brine-derived carbonate, hydroxide, iodine Low-cost Atacama salar extraction
Ganfeng Lithium ~10–13% Carbonate, hydroxide, metal, recycling China's largest converter; global mine equity stakes
Tianqi Lithium ~8–11% Hydroxide, carbonate, Greenbushes equity SQM shareholding; Australian concentrate access
Arcadium Lithium ~7–10% Hydroxide, carbonate, butyllithium Argentina brine plus Australian hard-rock
Pilbara Minerals ~4–6% Spodumene concentrate Pilgangoora mine; BMX digital sales platform
Mineral Resources ~3–5% Spodumene concentrate, mining services Low-cost Mt. Marion and Wodgina operations
Sigma Lithium ~2–4% Green spodumene concentrate ESG-differentiated Grota do Cirilo mine, Brazil
Piedmont Lithium ~1–3% Spodumene concentrate, hydroxide (planned) North Carolina asset; Tennessee JV with Sayona
IGO Limited ~1–3% Spodumene concentrate (Greenbushes JV) Downstream nickel-lithium integration strategy


Recent News & Developments


  • Arcadium Lithium (January 2024): Completed the Allkem-Livent merger, creating the world's third-largest lithium producer with combined capacity spanning Argentina, Australia, Canada, and the United States [20].
  • European Commission (March 2024): Formally adopted the Critical Raw Materials Act, setting binding 2030 targets of 10% domestic extraction and 40% domestic processing for strategic minerals, including lithium [2].


  • U.S. Department of Energy (September 2024): Awarded USD 2.26 billion in grants under the Battery Materials Processing program to seven lithium refining and recycling projects across Nevada, Louisiana, and North Carolina [1].


Lithium Market Report Scope

Parameter Detail
Market Scope Global Lithium Market covering mining, refining, and downstream compounds
Study Period 2021–2035
CAGR 17.8% (2026–2035)
Base Year Value USD 9,200 Million (2025)
Forecast Endpoint USD 47,340 Million (2035)
Fastest Growing Segment Hydroxide (by compound); Energy Storage (by end-user)
Companies Profiled 10 (Albemarle, SQM, Ganfeng, Tianqi, Arcadium, Pilbara, MinRes, Sigma, Piedmont, IGO)
Valuation Currency USD Million

FAQs

How should investors evaluate lithium juniors versus integrated majors?
Juniors offer leverage to resource discoveries but carry permitting and financing risk; integrated majors deliver steadier cash flows through the Lithium Market cycle. Portfolio allocation should reflect individual risk tolerance and time horizon [7].
What contract structures are OEMs using to secure lithium supply?
Most automakers now negotiate five-to-ten-year offtake agreements with floor-price clauses indexed to spodumene or carbonate benchmarks. These structures reduce procurement volatility across the Lithium Market [13].
How does sodium-ion technology affect the long-term lithium demand thesis?
Sodium-ion cells suit low-energy-density applications like micro-EVs and stationary storage but lack the gravimetric performance for premium vehicles. The net displacement risk to the Lithium Market remains limited through 2035 [19].
What role does recycling play in reducing primary lithium extraction?
The EU mandates 12% recycled lithium content by 2035, yet scrap availability lags cell-production growth. Recycling will supplement—not replace—primary supply in the Lithium Market this decade [21].
Which DLE technologies are closest to commercial-scale deployment?
Ion-exchange and adsorption-based DLE systems have reached pilot scale in Argentina and Nevada. Full commercialization timelines range from 2026 to 2028 depending on water-chemistry complexity [4].
How do ESG certification premiums affect producer margins in the Lithium Market?
Responsibly sourced material commands a 5–8% contract premium, offsetting higher compliance costs. Producers with verified low-carbon operations capture margin uplift relative to uncertified competitors [23].
What distinguishes spodumene hard-rock economics from brine-based extraction in the Lithium Market?
Hard-rock projects offer faster ramp-up (two to three years) but carry higher per-unit operating costs. Brine operations achieve lower cash costs yet require five-plus years to reach steady-state output [7].    
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, mining and geological surveys, energy policy publications, and authoritative industry organizations. Key sources included the US Geological Survey (USGS) Mineral Commodity Summaries, US Department of Energy (DOE) Vehicle Technologies Office, European Commission Directorate-General for Internal Market, Industry, Entrepreneurship and SMEs (DG GROW), European Raw Materials Alliance (ERMA), International Energy Agency (IEA) Critical Minerals Market Review, International Renewable Energy Agency (IRENA), International Energy Forum (IEF), National Renewable Energy Laboratory (NREL), Argonne National Laboratory GREET Model, Australian Bureau of Statistics (ABS) Mineral and Petroleum Exploration, Geoscience Australia Critical Minerals Reports, China Ministry of Natural Resources Mineral Resources Planning, Chilean Ministry of Mining (Ministerio de Minería) National Lithium Strategy, Argentina Ministry of Productive Development Mining Secretariat, Bolivian Ministry of Hydrocarbons and Energy Yacimientos de Litio Bolivianos (YLB) reports, World Bank Commodity Price Data, International Monetary Fund (IMF) Commodity Special Feature reports, United Nations Conference on Trade and Development (UNCTAD) Commodities and Development Report, Organisation for Economic Co-operation and Development (OECD) Mining Regions and Cities Case Studies, and national geological surveys from key lithium-producing jurisdictions. These sources were used to collect resource reserve estimates, production statistics, trade flow data, regulatory policy frameworks, battery supply chain analysis, and market landscape assessments for lithium carbonate, lithium hydroxide, lithium metal, and other derivative products.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. CEOs, VPs of Operations, principal geologists, and commercial directors from lithium mining companies, brine extraction operators, hard-rock spodumene producers, and lithium conversion facilities comprised the supply-side sources. Electric vehicle OEMs, battery cell manufacturers, consumer electronics companies, and energy storage system integrators constituted chief technology officers, supply chain directors, procurement leads, and battery material scientists (demand-side sources). Market segmentation was verified, production expansion timelines were confirmed, and insights regarding offtake agreement structures, pricing mechanism shifts, recycling technology developments, and regional supply chain localization strategies were obtained through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through production volume analysis, trade data reconciliation, and price trend modeling. The methodology included:

Identification of 50+ key producers across brine extraction, hard-rock mining, and conversion/refining operations spanning South America (Lithium Triangle), Australia, North America, Africa, and Asia

Product mapping across lithium carbonate (battery and industrial grades), lithium hydroxide (monohydrate and anhydrous), lithium metal, butyllithium, and lithium chloride categories

Analysis of reported and modeled annual production volumes and realized pricing specific to lithium product portfolios

Coverage of producers representing 75-80% of global lithium chemical supply in 2024

Extrapolation using bottom-up (production volume × realized price by product type and region) and top-down (producer revenue validation against trade statistics) approaches to derive segment-specific valuations, incorporating battery demand forecasts from EV sales projections and stationary storage deployment targets

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















