Linerless Labels Market (2026 - 2035)

ID: MRFR/PCM/1391-HCR 111 Pages Snehal Singh Last Updated: October 08, 2026
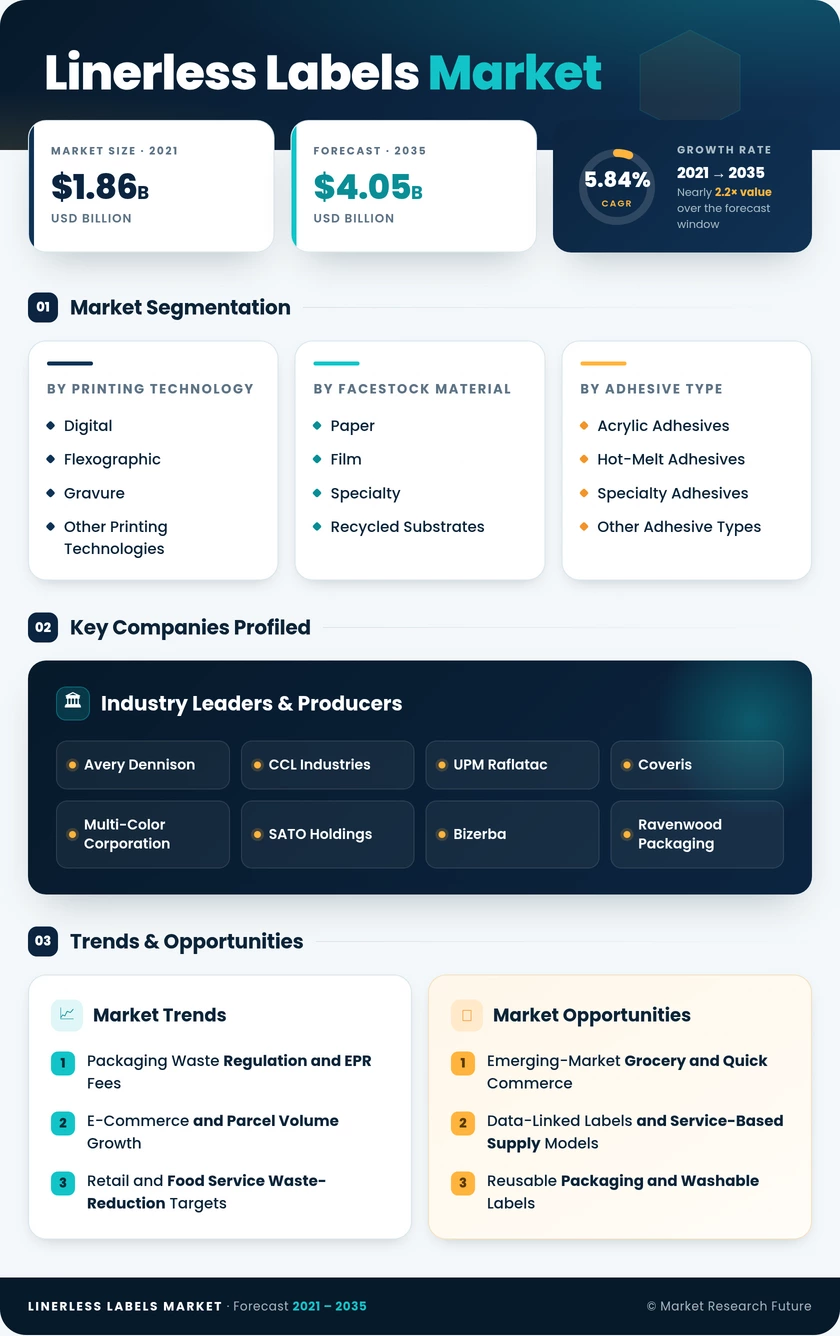
Linerless Labels Market Research Report Information By Printing Technology (Digital, Flexographic, Gravure, and Other Printing Technologies), By Facestock Material (Paper, Film, and Specialty and Recycled Substrates), By Adhesive Type (Acrylic Adhesives, Hot-Melt Adhesives, Specialty Adhesives, and Other Adhesive Types), and By End-User Industry (Food, Beverage, Healthcare and Pharmaceuticals, Cosmetics and Personal Care, and Other End-User Industries) – Forecast Till 2035.
Linerless Labels Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.84%
2025 Market SizeUSD 2.30 Billion
2035 Market SizeUSD 4.05 Billion
Key Players
Avery Dennison
CCL Industries
UPM Raflatac
Coveris
Multi-Color Corporation
SATO Holdings
Opportunities
  • Emerging-Market Grocery and Quick Commerce
  • Data-Linked Labels and Service-Based Supply Models
  • Reusable Packaging and Washable Labels
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Printing Technology | |
    2. 2.2 By Facestock Material | |
    3. 2.3 By Adhesive Type | |
    4. 2.4 By End-User Industry | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Packaging Waste Regulation and EPR Fees | |
    2. 4.2 E-Commerce and Parcel Volume Growth | |
    3. 4.3 Retail and Food Service Waste-Reduction Targets | |
    4. 4.4 Variable Data, Digital Print, and 2D Codes | |
    5. 4.5 Roll Productivity and Logistics Savings | |
    6. 4.6 Recyclable and Recycled Facestock Innovation | |
    7. 4.7 Plastic Taxes and Recycled-Content Rules | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Printer and Applicator Retrofit Costs | |
    2. 5.2 Shape and Format Limitations | |
    3. 5.3 Adhesive Buildup and Printhead Wear | |
    4. 5.4 Raw Material Cost Volatility | |
    5. 5.5 Thin Converter Base in Emerging Markets | |
  6. 6 Opportunities | |
    1. 6.1 Emerging-Market Grocery and Quick Commerce | |
    2. 6.2 Data-Linked Labels and Service-Based Supply Models | |
    3. 6.3 Reusable Packaging and Washable Labels | |
    4. 6.4 Healthcare Specimen and Pharmacy Labeling | |
    5. 6.5 Automated Fulfillment Integration | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Automated Print-and-Apply and AI-Driven Fulfillment | |
    2. 8.2 Circularity Regulation and Material Verification | |
    3. 8.3 Digital Product Passports and the Data-Carrying Label | |
    4. 8.4 Asia-Pacific Volume Shift | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Printing Technology | | |
      1. 9.1.1 Digital | | |
      2. 9.1.2 Flexographic | | |
      3. 9.1.3 Gravure | | |
      4. 9.1.4 Other Printing Technologies | |
    2. 9.2 By Facestock Material | | |
      1. 9.2.1 Paper | | |
      2. 9.2.2 Film | | |
      3. 9.2.3 Specialty and Recycled Substrates | |
    3. 9.3 By Adhesive Type | | |
      1. 9.3.1 Acrylic Adhesives | | |
      2. 9.3.2 Hot-Melt Adhesives | | |
      3. 9.3.3 Specialty Adhesives | | |
      4. 9.3.4 Other Adhesive Types | |
    4. 9.4 By End-User Industry | | |
      1. 9.4.1 Food | | |
      2. 9.4.2 Beverage | | |
      3. 9.4.3 Healthcare and Pharmaceuticals | | |
      4. 9.4.4 Cosmetics and Personal Care | | |
      5. 9.4.5 Other End-User Industries | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Avery Dennison | | |
      2. 10.3.2 CCL Industries | | |
      3. 10.3.3 UPM Raflatac | | |
      4. 10.3.4 Coveris | | |
      5. 10.3.5 Multi-Color Corporation | | |
      6. 10.3.6 SATO Holdings | | |
      7. 10.3.7 Bizerba | | |
      8. 10.3.8 Ravenwood Packaging | | |
      9. 10.3.9 Lintec Corporation | | |
      10. 10.3.10 Hub Labels | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis on CAGR, 2026–2035 | |
  18. TABLE 4 Restraints Impact Analysis on CAGR, 2026–2035 | |
  19. TABLE 5 Regional Market Summary, 2025 | |
  20. TABLE 6 North America Market, by Country, 2025 | |
  21. TABLE 7 Europe Market, by Country, 2025 | |
  22. TABLE 8 Asia-Pacific Market, by Country, 2025 | |
  23. TABLE 9 South America Market, by Country, 2025 | |
  24. TABLE 10 Middle East & Africa Market, by Country, 2025 | |
  25. TABLE 11 Global Market, by Printing Technology, 2025 | |
  26. TABLE 12 Global Market, by Facestock Material, 2025 | |
  27. TABLE 13 Global Market, by Adhesive Type, 2025 | |
  28. TABLE 14 Global Market, by End-User Industry, 2025 | |
  29. TABLE 15 Competitive Benchmarking Matrix, 2025 | |
  30. TABLE 16 Report Scope and Methodology | |
  31. TABLE 17 Detailed Sources and Citations | |
  32. TABLE 18 Segmentation Quick Reference | | LIST OF FIGURES | |
  33. FIGURE 1 Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  34. FIGURE 2 Industry Value Chain Analysis | |
  35. FIGURE 3 Porter's Five Forces Analysis | |
  36. FIGURE 4 Global Market Size Trend (USD Billion), 2021–2035 | |
  37. FIGURE 5 Market Share by Printing Technology, 2025 | |
  38. FIGURE 6 Market Share by Facestock Material, 2025 | |
  39. FIGURE 7 Market Share by Adhesive Type, 2025 | |
  40. FIGURE 8 Market Share by End-User Industry, 2025 | |
  41. FIGURE 9 Regional Market Share, 2025 | |
  42. FIGURE 10 Asia-Pacific Growth Outlook by Country, 2026–2035 | |
  43. FIGURE 11 Competitive Landscape Share Ranges, 2025 | |
  44. FIGURE 12 Company Strategic Positioning Map

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Printing TechnologyDigital, Flexographic, Gravure, Other Printing TechnologiesFlexographic (43.1% share)Digital (5.95% CAGR)
By Facestock MaterialPaper, Film, Specialty and Recycled SubstratesFilm (51.4% share)Specialty and Recycled Substrates (6.11% CAGR)
By Adhesive TypeAcrylic Adhesives, Hot-Melt Adhesives, Specialty Adhesives, Other Adhesive TypesHot-Melt Adhesives (32.4% share)Acrylic Adhesives (6.00% CAGR)
By End-User IndustryFood, Beverage, Healthcare and Pharmaceuticals, Cosmetics and Personal Care, Other End-User IndustriesFood (38.6% share)Other End-User Industries (6.4% CAGR)
By RegionNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaEurope (37.5% share)Asia-Pacific (7.1% CAGR)


Market Segmentation Overview

By Printing Technology

Sub-SegmentKey Trend
Digital1,200 DPI inkjet and hybrid presses absorb short-run and variable-data work
FlexographicInstalled base retains long-run volume and plate-efficient economics.
GravureLimited to premium beverage and cosmetics needing image consistency
Other Printing TechnologiesScreen and offset hybrids serve specification-heavy programs


Flexographic leads because converters have years of plate, ink, and finishing investment tuned to topcoated facestocks. Digital grows fastest as 2D codes and short runs reward inkjet and thermal output that changes every label without a plate. Gravure and Other Printing Technologies stay specialist, and hybrid presses let converters add digital capability without retiring flexographic lines.

By Facestock Material

Sub-SegmentKey Trend
PaperDirect-thermal grades dominate tickets, shipping, and ambient food
FilmPP, PET, and PE grades preferred for chilled and wet environments.
Specialty and Recycled SubstratesVerified recycling-compatible and washable grades gain specification


Film leads because chilled food, beverage, and personal care applications need moisture and chemical resistance that paper cannot offer. Specialty and Recycled Substrates grow fastest as PPWR recyclability rules push buyers toward grades with independent compatibility verification, such as UPM ProCycle. Paper stays essential for direct-thermal tickets and shipping, where low cost outweighs durability.

By Adhesive Type

Sub-SegmentKey Trend
Acrylic AdhesivesCold-surface gains and lower printhead silicone transfer
Hot-Melt AdhesivesFast tack on films and corrugated board at high speed
Specialty AdhesivesMigration-safe and sterile-grade formulations for regulated uses
Other Adhesive TypesWater-based and emulsion systems for slower-speed lines


Hot-Melt Adhesives lead because their immediate tack suits high-speed applicators on film and corrugated surfaces. Acrylic Adhesives grow fastest as newer formulations hold on cold trays and pair with thermal silicone release systems that reduce printhead contamination. Specialty Adhesives remain a qualification-driven niche in pharmaceutical and food-contact work.

By End-User Industry

Sub-SegmentKey Trend
FoodWeigh-price scale networks in deli, bakery, and meat counters
BeverageVariable promotional data on secondary packaging
Healthcare and PharmaceuticalsBedside specimen, pharmacy, and serialized labeling
Cosmetics and Personal CareFilm durability in wet-use environments
Other End-User IndustriesLogistics and parcel print-and-apply automation


Food leads because grocery weigh-price counters were the first large-scale linerless application and remain the deepest installed base. Other End-User Industries grow fastest, led by logistics and parcel lines where longer rolls cut stoppages on automated packing equipment. Healthcare and Pharmaceuticals follow closely as certified adhesives clear validation hurdles for specimen and pharmacy printing.


 

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.