SEGMENTATION QUICK REFERENCE
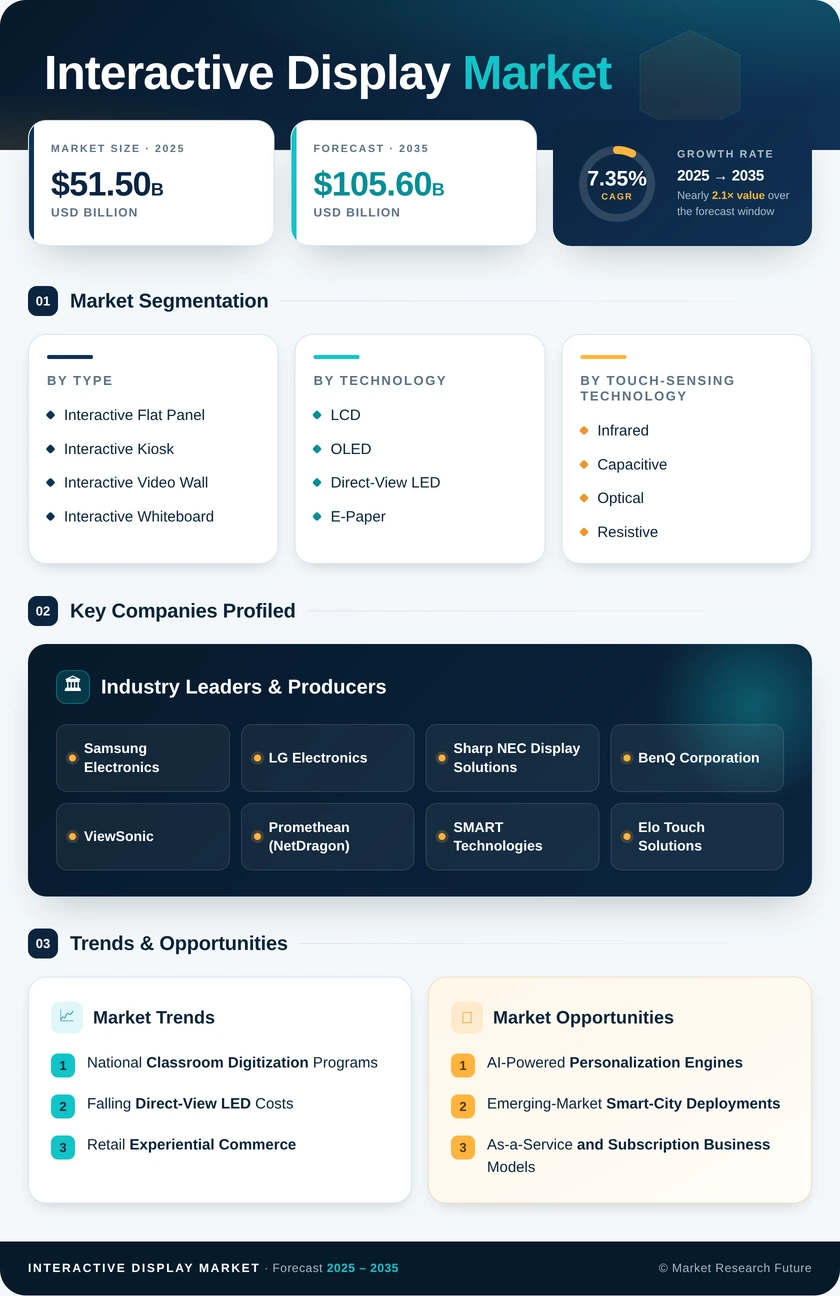
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| Display Type | Interactive Flat Panel, Interactive Kiosk, Interactive Video Wall, Interactive Whiteboard | Interactive Flat Panel | Interactive Kiosk |
| Technology | LCD, OLED, Direct-View LED, E-Paper | LCD | Direct-View LED |
| Touch-Sensing Technology | Infrared, Capacitive, Optical, Resistive | Infrared | Capacitive |
| Panel Size | Up to 32″, 32″–65″, Above 65″ | 32″–65″ | Above 65″ |
| Panel Orientation | Landscape, Portrait | Landscape | Portrait |
| End-User Vertical | Education, Corporate, Retail & Hospitality, Healthcare, Government & Transport | Education | Retail & Hospitality |
MARKET SEGMENTATION OVERVIEW
By Display Type
| Sub-Segment | Key Trend |
| Interactive Flat Panel | Consolidation around 75″ and 86″ screen sizes for education and corporate; AI-embedded models emerging |
| Interactive Kiosk | Self-service ordering and check-in accelerating in QSR, airports, and healthcare lobbies |
| Interactive Video Wall | Direct-view LED tiling replacing LCD bezeled walls in control rooms and retail flagships. |
| Interactive Whiteboard | Legacy installed base in K-12 declining as flat panels offer superior all-in-one functionality. |
Interactive flat panels remain the volume leader, driven by a form factor that replaces projectors, whiteboards, and videoconferencing codecs in a single device. Kiosks are gaining share as contactless and self-service workflows expand across verticals.
By Technology
| Sub-Segment | Key Trend |
| LCD | Mature, cost-optimized supply chain; IPS and VA panel improvements extending relevance |
| OLED | Premium adoption in corporate boardrooms and retail; transparent OLED pilots in luxury settings |
| Direct-View LED | Sub-1.2 mm pixel-pitch modules enabling indoor-quality seamless installations |
| E-Paper | Niche use in low-power digital signage and shelf-edge labels |
LCD dominates on cost-per-inch economics, while direct-view LED is rapidly closing the gap in large-format installations where seamless visuals and brightness justify the premium.
By Touch-Sensing Technology
| Sub-Segment | Key Trend |
| Infrared | Preferred for large-format panels; tolerates glove and stylus input |
| Capacitive | Growing in sub-55″ kiosks and panels where smartphone-like responsiveness is expected |
| Optical | Mid-tier alternative balancing cost and multi-touch accuracy |
| Resistive | Industrial and ruggedized niche; declining share in commercial settings |
Infrared sensing dominates panels above 65 inches, while capacitive technology is gaining traction in smaller-format kiosks and meeting-room panels.
By Panel Size
| Sub-Segment | Key Trend |
| Up to 32″ | Point-of-sale and kiosk applications; price-sensitive segment |
| 32″–65″ | Classroom and huddle-room workhorse; highest unit volume |
| Above 65″ | Fastest growing; driven by boardrooms, auditoriums, and immersive retail |
The 32″–65″ bracket is the volume core, but screens above 65″ are expanding fastest as declining panel costs make large-format interactive surfaces accessible to a wider buyer base.
By Panel Orientation
| Sub-Segment | Key Trend |
| Landscape | Default for education, conferencing, and video content display |
| Portrait | Rising adoption in wayfinding, digital menu boards, and elevator signage |
Landscape orientation dominates due to content format compatibility, while portrait deployments are expanding in vertical-signage and kiosk contexts.
By End-User Vertical
| Sub-Segment | Key Trend |
| Education | K-12 and higher-ed digitization mandates sustaining the largest revenue pool |
| Corporate | Meeting-room modernization and hybrid-work collaboration driving steady upgrades |
| Retail & Hospitality | Self-service, experiential commerce, and wayfinding fueling the fastest growth |
| Healthcare | Patient engagement terminals and digital wayfinding gaining CMS reimbursement linkage. |
| Government & Transport | Smart-city kiosks, transit passenger information, and public service terminals |
Education remains the anchor vertical, while retail and hospitality are expanding fastest as physical venues compete with e-commerce on in-store experience and data collection.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA