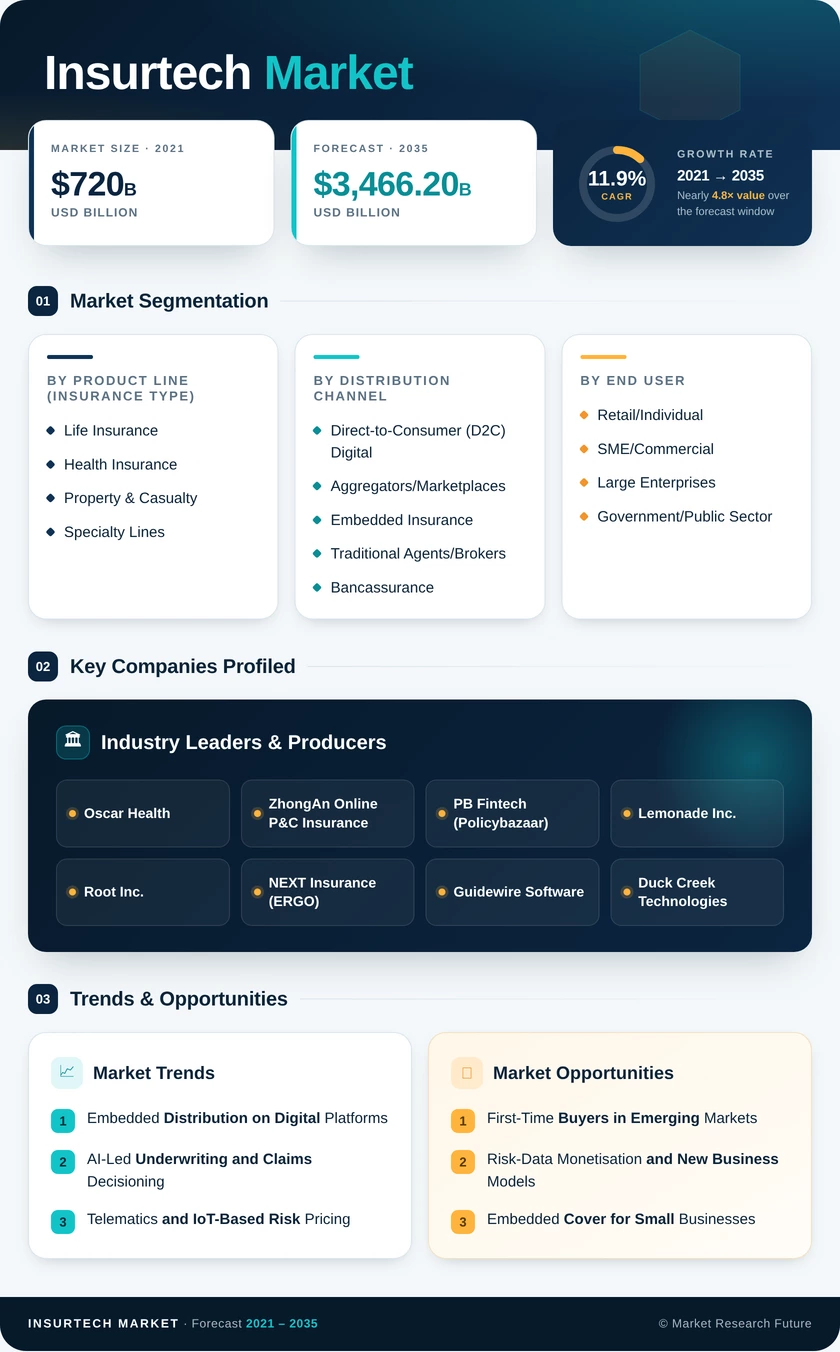
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Product Line (Insurance Type) | Life Insurance; Health Insurance; Property & Casualty; Specialty Lines | Property & Casualty (55.2% share) | Specialty Lines (17.5% CAGR) |
| By Distribution Channel | Direct-to-Consumer (D2C) Digital; Aggregators/Marketplaces; Embedded Insurance; Traditional Agents/Brokers; Bancassurance | Traditional Agents/Brokers (38.2% share) | Embedded Insurance (15.8% CAGR) |
| By End User | Retail/Individual; SME/Commercial; Large Enterprises; Government/Public Sector | Retail/Individual (63.1% share) | SME/Commercial (14.3% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America (38.5% share) | Asia-Pacific (14.6% CAGR) |
Market Segmentation Overview
By Product Line (Insurance Type)
| Sub-Segment | Key Trend |
|---|---|
| Life Insurance | Frictionless, accelerated underwriting issues term policies in minutes |
| Health Insurance | Digital plans bundle virtual care and chronic-condition programmes. |
| Property & Casualty | Telematics and smart-home sensors refine auto and home pricing. |
| Specialty Lines | Cyber, pet, marine and travel cover use parametric triggers. |
Property & Casualty leads with a 55.2% share because auto and homeowners policies are standardised, high-frequency and responsive to telematics data. Specialty Lines grow fastest at a 17.5% CAGR, as cyber and travel losses are discrete and verifiable enough for automated, trigger-based payouts. Life Insurance and Health Insurance digitise more slowly because mortality and morbidity rules limit how quickly underwriting models can change.
By Distribution Channel
| Sub-Segment | Key Trend |
|---|---|
| Direct-to-Consumer (D2C) Digital | Online self-service for commoditised personal lines |
| Aggregators/Marketplaces | Comparison platforms gain from transparency rules. |
| Embedded Insurance | Cover bound inside travel, mobility and e-commerce checkouts. |
| Traditional Agents/Brokers | Advisers adopt digital quoting for complex risks. |
| Bancassurance | App-based offers triggered by account activity |
Traditional Agents/Brokers hold the largest share at 38.2% because commercial and life products still require advice, though most now quote through digital tools. Embedded Insurance is the fastest-growing channel at a 15.8% CAGR, as partner platforms remove the separate shopping step and lift attachment rates. Direct-to-Consumer (D2C) Digital and Aggregators/Marketplaces compete on price in simple lines, where carriers increasingly build their own storefronts.
By End User
| Sub-Segment | Key Trend |
|---|---|
| Retail/Individual | Mobile purchase of auto, home, health and life cover |
| SME/Commercial | Accounting and e-commerce software embed liability and cyber cover. |
| Large Enterprises | Captives and analytics platforms support self-insurance. |
| Government/Public Sector | Digital procurement of crop and infrastructure cover |
Retail/Individual buyers dominate with a 63.1% share because personal lines are bought frequently and are easy to price online. SME/Commercial is the fastest-growing group at a 14.3% CAGR, since vertical software lowers acquisition costs for small policies that brokers once found uneconomic. Large Enterprises lean on captives, which cap third-party premium, while Government/Public Sector demand remains early-stage and pilot-driven.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA