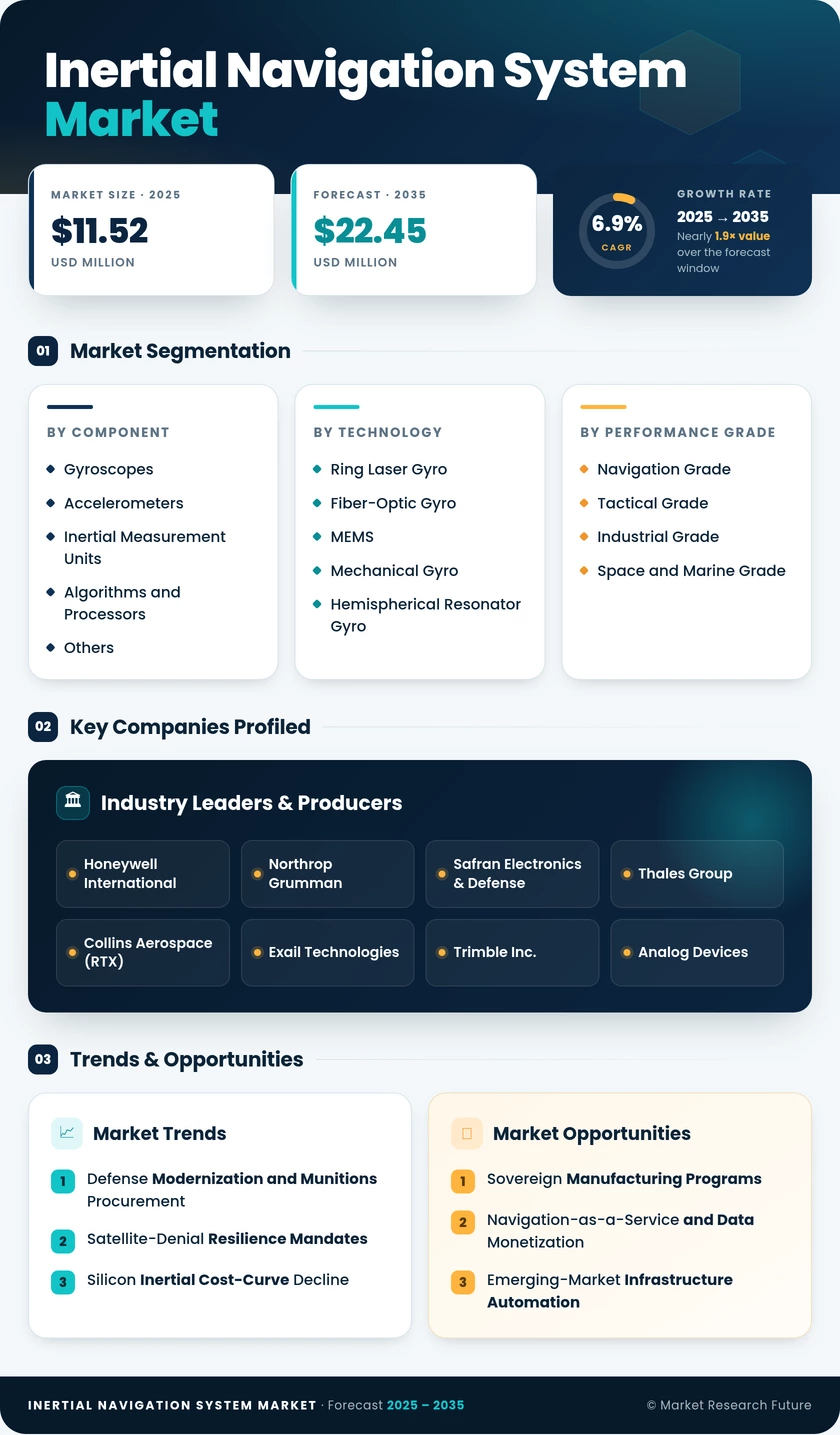
Inertial Navigation System Market (2026 - 2035)

ID: MRFR/AD/7074-HCR 173 Pages Abbas Raut Last Updated: September 15, 2026
Inertial Navigation System (INS) Market Size, Share, Industry Trend & Analysis Research Report Information By Component (Gyroscopes, Accelerometers, Inertial Measurement Units, Algorithms and Processors, Others), By Technology (Ring Laser Gyro, Fiber-Optic Gyro, MEMS, Mechanical Gyro, Hemispherical Resonator Gyro), By Performance Grade (Navigation Grade, Tactical Grade, Industrial Grade, Space and Marine Grade), By End-User Industry (Aerospace and Defense, Marine, Automotive, Industrial and Robotics, Construction and Agriculture, Others), By Platform (Airborne, Land, Naval / Maritime, Space), By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035
Inertial Navigation System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.9%
2025 Market SizeUSD 11.52 Billion
2035 Market SizeUSD 22.45 Billion
Key Players
Honeywell International
Northrop Grumman
Safran Electronics & Defense
Thales Group
Collins Aerospace
Exail Technologies
Opportunities
  • Sovereign Manufacturing Programs
  • Navigation-as-a-Service and Data Monetization
  • Emerging-Market Infrastructure Automation
  1. 1 Market Summary |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Key Report Takeaways |
    1. 2.1 By Technology |
    2. 2.2 By Sector |
    3. 2.3 By Region
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2024) |
    2. 3.2 Base Year Assessment (2025) |
    3. 3.3 Forecast Market Size (2026–2035) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 Defense Modernization and Munitions Procurement |
    2. 4.2 Satellite-Denial Resilience Mandates |
    3. 4.3 Silicon Inertial Cost-Curve Decline |
    4. 4.4 Autonomous Mobility Localization
  5. 5 Restraints Impact Analysis |
    1. 5.1 Export Control and Licensing Friction |
    2. 5.2 Unit Cost of Navigation-Grade Systems |
    3. 5.3 Drift and Integration Complexity
  6. 6 Opportunities |
    1. 6.1 Sovereign Manufacturing Programs |
    2. 6.2 Navigation-as-a-Service and Data Monetization |
    3. 6.3 Emerging-Market Infrastructure Automation |
    4. 6.4 Quantum and Cold-Atom Sensing |
    5. 6.5 Small Satellite Attitude Control
  7. 7 Regional Market Share & Country-Level Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of MEA
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Autonomy Becomes the Volume Engine |
    2. 8.2 Sensor Fusion Displaces Standalone Hardware |
    3. 8.3 Resilience Regulation Hardens |
    4. 8.4 Quantum Sensing Reaches Field Trials
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Component | |
      1. 9.1.1 Gyroscopes | |
      2. 9.1.2 Accelerometers | |
      3. 9.1.3 Magnetometers
      4. 9.1.5 Algorithms and Processors | |
      5. 9.1.6 Others |
    2. 9.1.4vInertial Measurement Units | |
    3. 9.2 By Technology | |
      1. 9.2.1 Ring Laser Gyro | |
      2. 9.2.2 Fiber-Optic Gyro | |
      3. 9.2.3 MEMS | |
      4. 9.2.4 Mechanical Gyro | |
      5. 9.2.5 Hemispherical Resonator Gyro |
    4. 9.3 By Performance Grade | |
      1. 9.3.1 Navigation Grade | |
      2. 9.3.2 Tactical Grade | |
      3. 9.3.3 Industrial Grade | |
      4. 9.3.4 Space and Marine Grade | |
      5. 9.3.5 Consumer Grade |
    5. 9.4 By End-User Industry | |
      1. 9.4.1 Aerospace and Defense | |
      2. 9.4.2 Marine | |
      3. 9.4.3 Automotive | |
      4. 9.4.4 Industrial and Robotics | |
      5. 9.4.5 Oil and Gas and Energy | |
      6. 9.4.6 Construction and Agriculture
    6. 9.4.7Others |
    7. 9.5 By Platform | |
      1. 9.5.1 Airborne | |
      2. 9.5.2 Land | |
      3. 9.5.3 Naval / Maritime | |
      4. 9.5.4 Space
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Honeywell International | |
      2. 10.3.2 Northrop Grumman | |
      3. 10.3.3 Safran Electronics & Defense | |
      4. 10.3.4 Thales Group | |
      5. 10.3.5 Collins Aerospace (RTX) | |
      6. 10.3.6 Exail Technologies | |
      7. 10.3.7 Trimble Inc. | |
      8. 10.3.8 Analog Devices | |
      9. 10.3.9 Teledyne Marine | |
      10. 10.3.10 KVH Industries | |
      11. 10.3.11 VectorNav Technologies | |
      12. 10.3.12 SBG Systems
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Triangulation |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES Source: Market Research Future Analysis
  16. 16 LIST OF FIGURES Source: Market Research Future Analysis

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentGyroscopes; Accelerometers; Inertial Measurement Units; Algorithms and Processors; OthersGyroscopesInertial Measurement Units
By TechnologyRing Laser Gyro; Fiber-Optic Gyro; MEMS; Mechanical Gyro; Hemispherical Resonator GyroRing Laser GyroFiber-Optic Gyro
By Performance GradeNavigation Grade; Tactical Grade; Industrial Grade; Space and Marine GradeNavigation GradeIndustrial Grade
By End-User IndustryAerospace and Defense; Marine; Automotive; Industrial and Robotics; Construction and Agriculture; OthersAerospace and DefenseAutomotive
By PlatformAirborne; Land; Naval / Maritime; SpaceAirborneNaval / Maritime
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
GyroscopesOptical architectures displacing spinning-mass designs across new-build platforms
AccelerometersSilicon fabrication driving unit cost down and shipment volume up
Inertial Measurement UnitsBuyers shifting from discrete devices to pre-calibrated integrated modules
Algorithms and ProcessorsEstimation software emerging as the primary accuracy differentiator
OthersMounting, thermal management and interface electronics bundled into system contracts


Component economics are inverting. Hardware margin compresses while software and calibration services expand, and suppliers who once sold sensors now sell guaranteed error budgets backed by lifecycle support contracts.

By Technology

Sub-SegmentKey Trend
Ring Laser GyroSustained demand from strategic aircraft and submarine sustainment programs
Fiber-Optic GyroPreferred for high-shock and long-endurance missions; strongest optical growth
MEMSCost decline opening agriculture, rail and warehouse automation applications
Mechanical GyroLegacy sustainment only; no meaningful new-build design wins
Hemispherical Resonator GyroSpace and deep-endurance niche expanding with constellation launch cadence


Technology selection maps almost directly onto mission duration and shock environment. Buyers increasingly specify performance outcomes and let suppliers choose the underlying architecture.

By Performance Grade

Sub-SegmentKey Trend
Navigation GradeAnchored by submarine, strategic aircraft and long-endurance unmanned platforms
Tactical GradeConsumable demand from guided munitions creating recurring revenue
Industrial GradeFastest expansion as automation reaches ports, mines and warehouses
Space and Marine GradeRadiation and pressure tolerance commanding sustained price premiums


Grade boundaries are blurring as silicon devices creep upward in performance. That migration threatens mid-tier optical pricing more than it threatens the navigation-grade tier.

By End-User Industry

Sub-SegmentKey Trend
Aerospace and DefenseModernization cycles and munitions replenishment sustaining majority share
MarineDynamic positioning and subsea survey demand tied to offshore energy capex
AutomotiveRedundant localization mandates driving the steepest growth trajectory
Industrial and RoboticsIndoor autonomy where satellite reception is unavailable
Construction and AgricultureMachine control and precision guidance adoption in mid-size fleets
OthersRail signaling, surveying and medical robotics applications


Defense dominance provides stability, but the diversification story sits in automotive and industrial autonomy. Both demand automotive-scale pricing, forcing suppliers to rethink cost structures built around low-volume programs.

By Platform

Sub-SegmentKey Trend
AirborneRetrofit demand accelerating on interference-affected commercial corridors
LandArmored vehicle upgrades and ground robotics adding steady volume
Naval / MaritimeUncrewed surface and subsea vessels driving the strongest platform growth
SpaceConstellation deployment cadence creating volume demand for compact units


Platform mix is broadening beyond the traditional airborne core. Maritime autonomy in particular converts inertial reference from a redundancy layer into the primary navigation source.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.