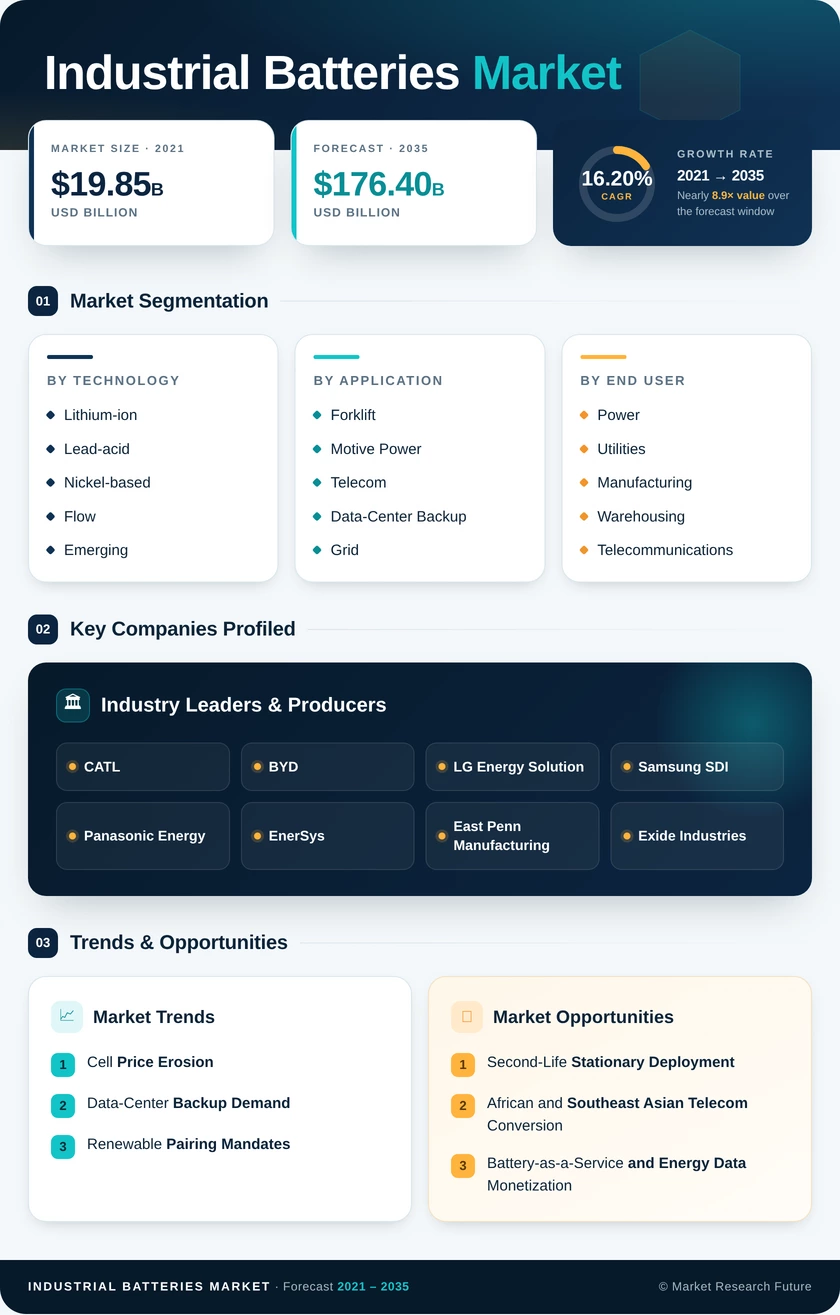
Industrial Batteries Market (2026 - 2035)

ID: MRFR/EnP/1100-HCR 111 Pages Chitranshi Jaiswal Last Updated: September 15, 2026
Industrial Batteries Market Research Report By Technology (Lithium-ion, Lead-acid, Nickel-based, Flow and Emerging), By Application (Forklift and Motive Power, Telecom and Data-Center Backup, Grid and Renewable Integration, Industrial UPS and Process Backup, Rail and Marine Traction), By End User (Power and Utilities, Manufacturing and Warehousing, Telecommunications, Transportation and Logistics, Oil, Gas, and Mining) - Forecast to 2035
Industrial Batteries Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)16.20%
2025 Market SizeUSD 38.10 Billion
2035 Market SizeUSD 176.40 Billion
Key Players
CATL
BYD
LG Energy Solution
Samsung SDI
Panasonic Energy
EnerSys
Opportunities
  • Second-Life Stationary Deployment
  • African and Southeast Asian Telecom Conversion
  • Battery-as-a-Service and Energy Data Monetization
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Technology | |
    2. 2.2 By Sector | |
    3. 2.3 By Geography | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Cell Price Erosion | |
    2. 4.2 Data-Center Backup Demand | |
    3. 4.3 Renewable Pairing Mandates | |
    4. 4.4 Warehouse Electrification | |
    5. 4.5 Manufacturing Tax Credits | |
    6. 4.6 Telecom Tower Conversion | |
    7. 4.7 Grid Resilience Regulation | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Fire Safety and Insurance Costs | |
    2. 5.2 Critical Mineral Price Volatility | |
    3. 5.3 Grid Interconnection Backlogs | |
    4. 5.4 Recycling and EPR Compliance Cost | |
    5. 5.5 Skilled Installation Shortage | |
  6. 6 Opportunities | |
    1. 6.1 Second-Life Stationary Deployment | |
    2. 6.2 African and Southeast Asian Telecom Conversion | |
    3. 6.3 Battery-as-a-Service and Energy Data Monetization | |
    4. 6.4 Sodium-Ion for Cost-Sensitive Backup | |
    5. 6.5 Localized Assembly Under Trade Policy | |
  7. 7 Regional Market Share & Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Software-Defined Battery Management | |
    2. 8.2 Long-Duration Storage Segmentation | |
    3. 8.3 Supply Chain Regionalization | |
    4. 8.4 Circularity as Procurement Criterion | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Technology | | |
      1. 9.1.1 Lithium-ion | | |
      2. 9.1.2 Lead-acid | | |
      3. 9.1.3 Nickel-based | | |
      4. 9.1.4 Flow and Emerging | |
    2. 9.2 By Application | | |
      1. 9.2.1 Forklift and Motive Power | | |
      2. 9.2.2 Telecom and Data-Center Backup | | |
      3. 9.2.3 Grid and Renewable Integration | | |
      4. 9.2.4 Industrial UPS and Process Backup | | |
      5. 9.2.5 Rail and Marine Traction | |
    3. 9.3 By End User | | |
      1. 9.3.1 Power and Utilities | | |
      2. 9.3.2 Manufacturing and Warehousing | | |
      3. 9.3.3 Telecommunications | | |
      4. 9.3.4 Transportation and Logistics | | |
      5. 9.3.5 Oil, Gas, and Mining | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope & Methodology | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Industrial Batteries Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Industrial Batteries Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis – Global Industrial Batteries Market, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis – Global Industrial Batteries Market, 2026–2035 | |
  19. TABLE 5 Global Industrial Batteries Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Industrial Batteries Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Industrial Batteries Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Industrial Batteries Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Industrial Batteries Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Industrial Batteries Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Industrial Batteries Market Size, by Technology, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Industrial Batteries Market Size, by Application, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Industrial Batteries Market Size, by End User, 2021–2035 (USD Billion) | |
  28. TABLE 14 North America Industrial Batteries Market Size, by Technology, 2021–2035 (USD Billion) | |
  29. TABLE 15 Europe Industrial Batteries Market Size, by Technology, 2021–2035 (USD Billion) | |
  30. TABLE 16 Asia-Pacific Industrial Batteries Market Size, by Technology, 2021–2035 (USD Billion) | |
  31. TABLE 17 North America Industrial Batteries Market Size, by Application, 2021–2035 (USD Billion) | |
  32. TABLE 18 Europe Industrial Batteries Market Size, by Application, 2021–2035 (USD Billion) | |
  33. TABLE 19 Asia-Pacific Industrial Batteries Market Size, by Application, 2021–2035 (USD Billion) | |
  34. TABLE 20 Competitive Benchmarking Matrix – Global Industrial Batteries Market, 2026 | |
  35. TABLE 21 Company Profiles – Key Players, Global Industrial Batteries Market | |
  36. TABLE 22 Recent Developments & Strategic Announcements, 2023–2025 | |
  37. TABLE 23 Report Scope & Methodology Summary | |
  38. TABLE 24 Detailed Sources & Citations Index | | LIST OF FIGURES | |
  39. FIGURE 1 Global Industrial Batteries Market Dynamics – Drivers, Restraints, Opportunities | |
  40. FIGURE 2 Industry Value Chain Analysis – Cell, Module, Pack, Integration, Recycling | |
  41. FIGURE 3 Porter's Five Forces Analysis – Global Industrial Batteries Market | |
  42. FIGURE 4 Global Market Size Trend & Forecast, 2021–2035 (USD Billion) | |
  43. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 (%) | |
  44. FIGURE 6 Market Share by Technology, 2025 vs 2035 (%) | |
  45. FIGURE 7 Market Share by Application, 2025 vs 2035 (%) | |
  46. FIGURE 8 Market Share by End User, 2025 (%) | |
  47. FIGURE 9 Regional Revenue Share Distribution, 2025 (%) | |
  48. FIGURE 10 Regional CAGR Comparison, 2026–2035 (%) | |
  49. FIGURE 11 Country-Level Share Within Asia-Pacific, 2025 (%) | |
  50. FIGURE 12 Competitive Landscape – Estimated Revenue Share Ranges, 2026 | |
  51. FIGURE 13 Cell Price Decline Curve vs Deployment Volume, 2021–2035 | |
  52. FIGURE 14 Second-Life Battery Supply Availability Forecast, 2026–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TechnologyLithium-ion; Lead-acid; Nickel-based; Flow and EmergingLithium-ionFlow and Emerging
By ApplicationForklift and Motive Power; Telecom and Data-Center Backup; Grid and Renewable Integration; Industrial UPS and Process Backup; Rail and Marine TractionForklift and Motive PowerGrid and Renewable Integration
By End UserPower and Utilities; Manufacturing and Warehousing; Telecommunications; Transportation and Logistics; Oil, Gas, and MiningPower and UtilitiesManufacturing and Warehousing
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Technology

Sub-SegmentKey Trend
Lithium-ionLFP displacing nickel-rich chemistries in stationary duty on cost and thermal stability
Lead-acidRetaining share in rarely-cycled reserve applications; volumes flat, value stable
Nickel-basedConcentrated in aviation, rail, and extreme-temperature reliability niches
Flow and EmergingSodium-ion and vanadium flow entering pilot-to-commercial transition for long duration


Chemistry selection is increasingly duty-cycle driven rather than performance driven. Lithium-ion wins wherever cycling is frequent or footprint constrained, while lead-acid holds standby positions on pure capital cost. Emerging chemistries grow fastest from a small base, targeting duration bands where lithium economics deteriorate.

By Application

Sub-SegmentKey Trend
Forklift and Motive PowerOpportunity charging eliminating battery-swap infrastructure in multi-shift warehouses
Telecom and Data-Center BackupFootprint reduction and extended service life displacing valve-regulated strings
Grid and Renewable IntegrationStorage attachment mandates converting discretionary spend into compulsory procurement
Industrial UPS and Process BackupAutomation raising the cost of downtime in continuous manufacturing
Rail and Marine TractionFleet renewal on ten-to-fifteen-year cycles favoring lithium and nickel hybrids


Application demand splits between replacement-driven and mandate-driven pools. Motive power and backup are replacement cycles with predictable cadence; grid integration is policy-timed and therefore lumpier. Suppliers serving both smooth revenue against regulatory timing risk.

By End User

Sub-SegmentKey Trend
Power and UtilitiesCapacity market revenue and resilience mandates supporting large-scale procurement
Manufacturing and WarehousingElectrified material handling and automation driving fastest end-user growth
TelecommunicationsDiesel displacement economics strongest in weak-grid geographies
Transportation and LogisticsPort, depot, and rail electrification programs expanding fleet-scale demand
Oil, Gas, and MiningRemote site power and underground haulage conversion reducing ventilation load


Utilities anchor volume through project scale, but growth momentum sits with industrial and warehousing buyers whose purchase decisions are shorter-cycle and less permit-constrained. Telecom and mining demand is geographically concentrated and driven by total cost of ownership rather than policy.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.