Hydrate Inhibitors Market Summary
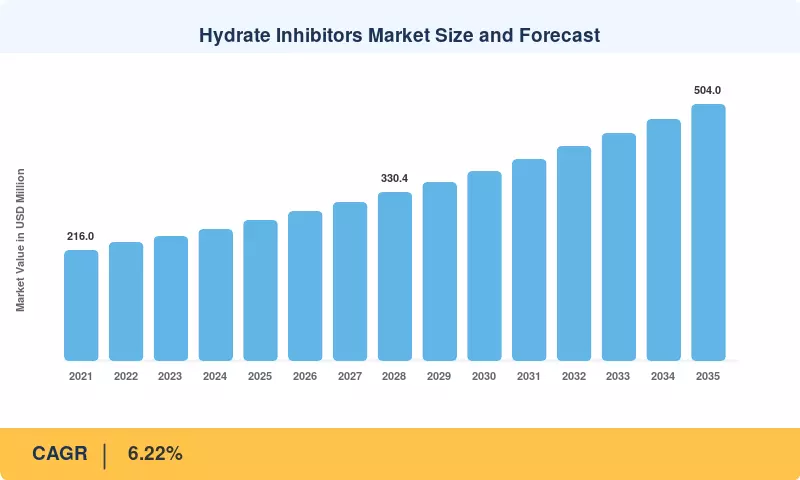
The Hydrate Inhibitors Market was valued at USD 274.8 Million in 2025 and is projected to reach USD 292.8 Million in 2026, climbing to USD 504.0 Million by 2035 at a CAGR of 6.22% over 2026–2035. Two catalysts anchor this outlook. QatarEnergy's North Field East expansion lifts national LNG capacity from 77 to 110 million tonnes per annum, with continuous glycol injection across its offshore gathering grid [5]. In parallel, Chevron's Anchor field became the first deepwater development to produce at 20,000 psi, setting a new pressure envelope for subsea chemical programs [11].
Across the Hydrate Inhibitors Market, operators are retiring batch methanol washes in favor of continuously metered, low-dosage chemistries delivered through subsea injection skids. Kinetic inhibitors and anti-agglomerants work at roughly 1–3 wt% of produced water, against 30–60 wt% for methanol or monoethylene glycol (MEG), cutting tankage, umbilical size, and vessel logistics [22]. That shift matters most on long tie-backs, where every cubic metre of injected fluid carries a high transport cost.
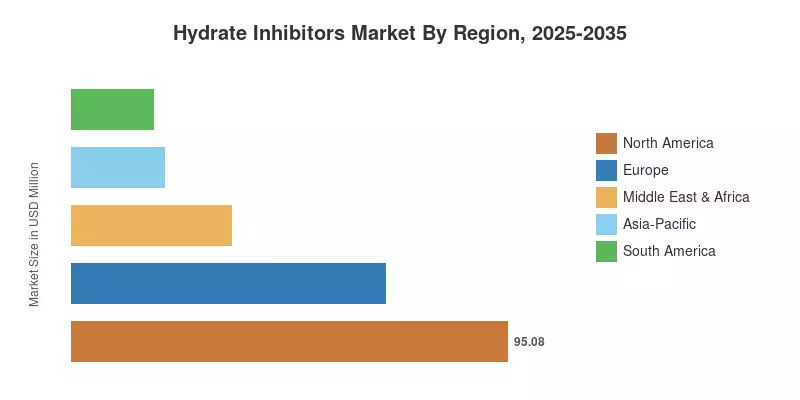
North America leads the Hydrate Inhibitors Market with a 34.6% share, supported by Gulf of America deepwater activity and an LNG export build-out [3]. Asia-Pacific is the fastest-growing region at a 7.4% CAGR, driven by gas developments in China, India, and Southeast Asia. Europe ranks second, where North Sea discharge rules are steering spending toward biodegradable products [6]. Over the next decade, pressure, distance, and environmental scrutiny will decide which chemistries win share.
Key Report Takeaways
• By Type
- Thermodynamic Hydrate Inhibitors (THIs) hold a 45.6% share of the Hydrate Inhibitors Market, sustained by MEG recovery loops at onshore gas plants.
- Green/Biodegradable Inhibitors are set to expand at a 7.9% CAGR as North Sea and U.S. Gulf discharge permits tighten.
• By Form
- Liquid inhibitors account for 82.4% of the Hydrate Inhibitors Market, because one umbilical can meter hydrate, scale, and corrosion chemicals together.
- Solid formulations are forecast to grow at a 7.8% CAGR, led by unmanned wellhead pilots.
• By Application
- Subsea Pipelines and Transportation commands a 41.1% share, reflecting tie-backs beyond 100 kilometres.
- Oil and Gas Production Wells generated USD 67.3 million in 2025.
• By End-user Industry
- Upstream Oil and Gas is projected to post a 7.7% CAGR on continuous downhole and subsea dosing.
- Midstream and Transmission holds a 26.3% share as transmission grids extend to new LNG import terminals.
• By Region
- North America holds a 34.6% share of the Hydrate Inhibitors Market.
- Asia-Pacific is the fastest-growing region at a 7.4% CAGR.
- Europe was valued at USD 68.4 million in 2025.
Market Size and Forecast (2021–2035)
Market Research Future sized the Hydrate Inhibitors Market bottom-up from injection-volume data at producing assets, cross-checked against supplier revenue disclosures and LNG, pipeline, and subsea project trackers. Historical values reflect reported chemical consumption by operators, while forecasts layer project start-ups, discharge regulation timelines, and expected LDHI substitution rates onto the 2025 base.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


