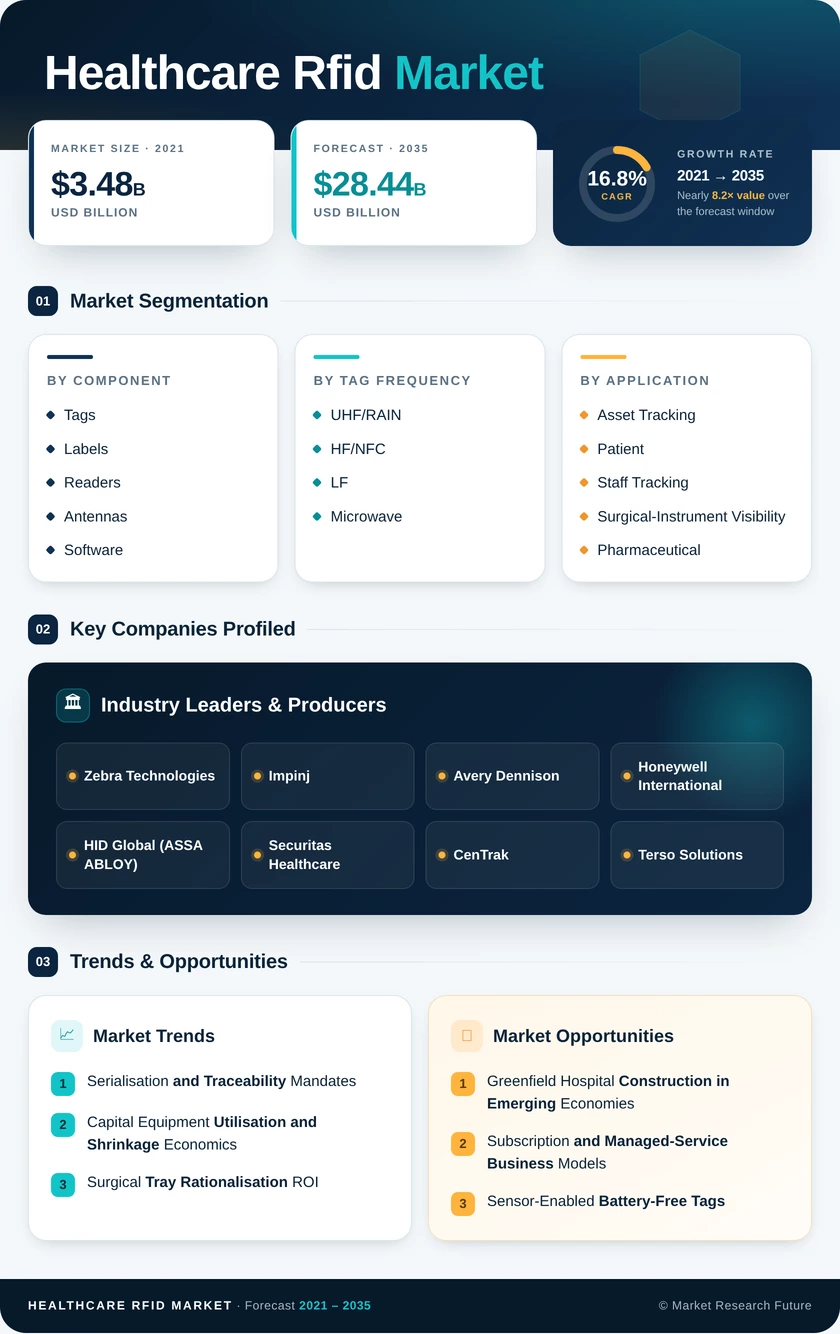
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Component | Tags and Labels; Readers and Antennas; Software and Analytics; Services | Tags and Labels (42.9% share) | Software and Analytics (19.9% CAGR) |
| By Tag Frequency | UHF/RAIN; HF/NFC; LF; Microwave | UHF/RAIN (51.2% share) | Microwave (20.5% CAGR) |
| By Application | Asset Tracking; Patient and Staff Tracking; Surgical-Instrument Visibility; Pharmaceutical and Medication Tracking; Blood and Specimen Monitoring | Asset Tracking (29.5% share) | Surgical-Instrument Visibility (20.4% CAGR) |
| By End User | Hospitals; Pharmaceutical Manufacturers; Contract Logistics and Third-Party Providers; Research Labs and Biobanks; Other End Users | Hospitals (56.2% share) | Contract Logistics and Third-Party Providers (19.6% CAGR) |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
| Tags and Labels | Inlay pricing below four cents widens addressable inventory to consumables |
| Readers and Antennas | Multi-protocol devices extend lifecycle utility and slow replacement cycles. |
| Software and Analytics | Predictive utilisation and maintenance modules shift value to the data layer. |
| Services | Engagements expand into workflow redesign and cybersecurity hardening. |
Tags and Labels lead component revenue at 42.9% because item count, not deployment count, sets demand — every tracked pump, tray, and vial needs its own identifier. Software and Analytics grows fastest at 19.9% as finance committees fund platforms that translate reads into utilisation evidence rather than additional hardware. Readers and Antennas face price compression from multi-protocol designs that delay replacement, while Services grow on the consultative side rather than through installation labour.
By Tag Frequency
| Sub-Segment | Key Trend |
| UHF/RAIN | Passive portal reads at scale, reinforced by 44.8 billion annual chip shipments. |
| HF/NFC | Short-range security preferred for controlled-access carts and cabinets |
| LF | Retained for read-through performance in fluids, implants, and dialysers |
| Microwave | Centimetre-level accuracy demanded by perioperative instrument counting |
UHF/RAIN holds 51.2% of frequency revenue because standard passive portals interrogate hundreds of items across rooms without line of sight, making it the default backbone for hospital-wide coverage. Microwave posts the steepest 20.5% growth as operating rooms require pinpoint resolution on scalpels and drill bits that longer wavelengths cannot deliver. HF/NFC and LF hold defensible niches where short-range security or transmission through fluid and metal outweighs range.
By Application
| Sub-Segment | Key Trend |
| Asset Tracking | Utilisation recovery on pump and monitor fleets defers replacement capital |
| Patient and Staff Tracking | Workforce scarcity drives telemetry-based rounding and duress systems. |
| Surgical-Instrument Visibility | Tray rationalisation evidence delivers the category's clearest ROI case. |
| Pharmaceutical and Medication Tracking | Serialisation enforcement extends into hospital pharmacy operations. |
| Blood and Specimen Monitoring | Tag-level temperature logging replaces manual custody logbooks. |
Asset Tracking commands 29.5% of application revenue because movable equipment counts run into the thousands per campus, giving the widest immediate deployment surface. Surgical-Instrument Visibility grows fastest at 20.4%, carried by documented reprocessing savings that sterile processing directors can defend line by line. Blood and Specimen Monitoring is the emerging pull, since pathology and transfusion services need continuous custody evidence rather than sampled documentation at inspection intervals.
By End User
| Sub-Segment | Key Trend |
| Hospitals | Enterprise standardisation replaces fragmented departmental pilots |
| Pharmaceutical Manufacturers | Unit-level provenance required under falsified-medicine regulation |
| Contract Logistics and Third-Party Providers | Dedicated serialisation centres sold as subscription compliance |
| Research Labs and Biobanks | Chain-of-custody needs constrained by grant funding cycles. |
| Other End Users | Ambulatory centres and long-term care adopt packaged low-cost deployments. |
Hospitals anchor 56.2% of end-user revenue given their capital fleet ownership and direct liability for adverse events, which keeps them the largest single buying centre. Contract Logistics and Third-Party Providers grow fastest at 19.6% as outsourcers absorb serialisation obligations that manufacturers prefer not to build internally. Pharmaceutical Manufacturers adopt steadily under regulatory pressure, while Research Labs and Biobanks value custody documentation but move on slower grant-driven procurement rhythms.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA