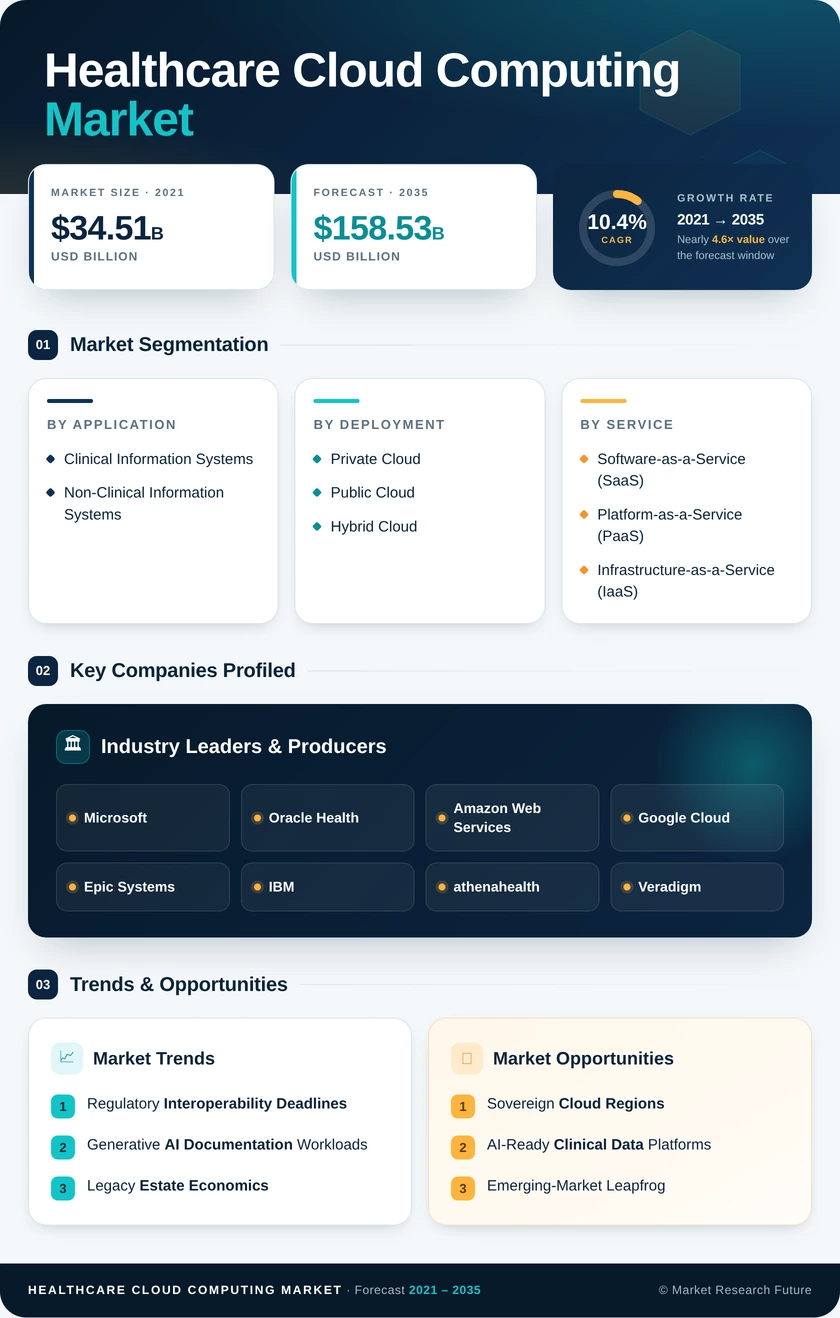
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Application | Clinical Information Systems; Non-Clinical Information Systems | Clinical Information Systems | Non-Clinical Information Systems |
| By Deployment | Private Cloud; Public Cloud; Hybrid Cloud | Private Cloud | Hybrid Cloud |
| By Service | Software-as-a-Service (SaaS); Platform-as-a-Service (PaaS); Infrastructure-as-a-Service (IaaS) | Software-as-a-Service (SaaS) | Platform-as-a-Service (PaaS) |
| By End User | Healthcare Providers; Healthcare Payers | Healthcare Providers | Healthcare Payers |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Application
| Sub-Segment | Key Trend |
| Clinical Information Systems | Certified record replacement cycles and imaging archive migration sustain the largest workload base |
| Non-Clinical Information Systems | Revenue cycle and supply chain modules migrate first where finance teams control the IT agenda |
Clinical workloads carry regulatory obligations that make deferral expensive, which keeps this dimension weighted toward patient-facing systems even as administrative modules deliver quicker measurable returns.
By Deployment
| Sub-Segment | Key Trend |
| Private Cloud | Dedicated tenancy remains the default answer to clinical audit and isolation requirements |
| Public Cloud | Elastic capacity for analytics, imaging inference, and research workloads |
| Hybrid Cloud | Phased migration and jurisdictional partitioning make hybrid the practical steady state |
Deployment choice increasingly reflects legal geography rather than technical preference, and hybrid architectures persist far longer than migration roadmaps originally assume.
By Service
| Sub-Segment | Key Trend |
| Software-as-a-Service (SaaS) | Vendor-hosted clinical and administrative suites dominate subscription spend |
| Platform-as-a-Service (PaaS) | FHIR data platforms and governance tooling grow as AI programmes mature |
| Infrastructure-as-a-Service (IaaS) | Imaging archives, backup and disaster recovery anchor raw capacity demand |
Buyers begin at the application layer and move downward, acquiring platform control only once AI ambitions expose the limits of packaged software.
By End User
| Sub-Segment | Key Trend |
| Healthcare Providers | Record modernisation, ambient documentation and imaging drive sustained spend |
| Healthcare Payers | Interoperability API mandates trigger a concentrated modernisation cycle |
Provider spending grows steadily with clinical adoption, while payer spending clusters around regulatory deadlines and therefore arrives in sharper, less predictable waves.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA