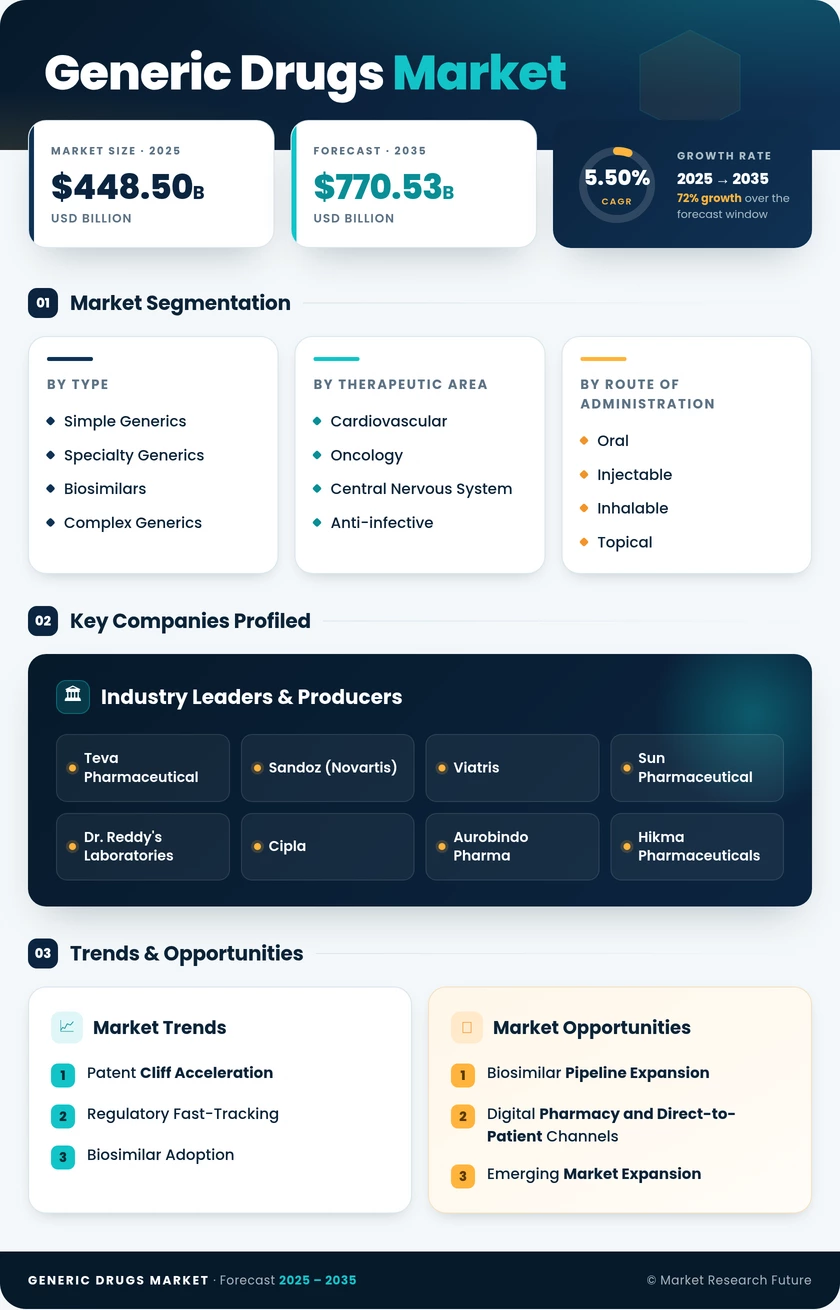
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| Drug Type | Simple Generics, Specialty Generics, Biosimilars, Complex Generics | Simple Generics | Biosimilars |
| Therapeutic Area | Cardiovascular, Oncology, Central Nervous System, Anti-infective, Others | Cardiovascular | Oncology |
| Route of Administration | Oral, Injectable, Inhalable, Topical | Injectable | Inhalable |
| Distribution Channel | Hospital Pharmacies, Retail Pharmacies, Online Pharmacies | Hospital Pharmacies | Online Pharmacies |
| Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Drug Type
| Sub-Segment | Key Trend |
| Simple Generics | Sustained volume leadership in chronic-therapy categories with intensifying price competition |
| Specialty Generics | Growing demand for differentiated formulations with limited competition |
| Biosimilars | Accelerating launches driven by biologic patent cliffs and interchangeability designations |
| Complex Generics | Rising investment in modified-release, long-acting injectable, and device-combination products |
Simple generics continue to anchor global prescription volumes, though margin compression is driving manufacturers toward higher-value segments. Biosimilars represent the most dynamic growth opportunity as regulatory pathways mature and payer adoption accelerates across major markets.
By Therapeutic Area
| Sub-Segment | Key Trend |
| Cardiovascular | Dominant share sustained by aging demographics and high hypertension prevalence globally |
| Oncology | Fastest growth driven by immuno-oncology and targeted-therapy patent expirations |
| Central Nervous System | Expanding antidepressant and antiepileptic generic availability |
| Anti-infective | Steady demand supported by antimicrobial stewardship and essential medicines programs |
Cardiovascular generics benefit from the largest established patient base and decades of accumulated off-patent molecules. Oncology is emerging as the high-growth frontier as biosimilar versions of monoclonal antibodies enter global formularies.
By Route of Administration
| Sub-Segment | Key Trend |
| Oral | Largest manufacturing base with lowest per-unit costs and highest patient compliance |
| Injectable | Dominant revenue share driven by hospital and specialty pharmacy procurement |
| Inhalable | Fastest growth supported by respiratory disease burden despite complex bioequivalence requirements |
| Topical | Niche growth in dermatology and localized pain management applications |
Injectable generics command premium pricing relative to oral forms and benefit from institutional procurement dynamics. Inhalable generics present significant opportunity but require specialized device development and manufacturing capabilities.
By Distribution Channel
| Sub-Segment | Key Trend |
| Hospital Pharmacies | Largest channel driven by institutional formulary systems and GPO contracts |
| Retail Pharmacies | Stable chronic-therapy refill volumes with mandatory substitution support |
| Online Pharmacies | Fastest-growing channel powered by telehealth integration and consumer digital adoption |
Hospital pharmacies retain channel leadership through centralized procurement and formulary management. Online pharmacies are disrupting traditional distribution by integrating prescription services with chronic-disease management platforms and home delivery.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA