Generic Drugs Market (2026 - 2035)

Generic Drugs Market Research Report By Product Type (Simple Generics, Super Generics, Biosimilars), By Application (Cardiovascular Diseases, Anti-Infective Diseases, Central Nervous System Diseases, Respiratory Diseases, Oncology, Diabetes, Others), By Route of Administration (Oral, Injectable, Topical, Others), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/HC/57639-CR 139 Pages Rahul Gotadki, Kinjoll Dey Last Updated: September 17, 2026
Generic Drugs Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.50%
2025 Market SizeUSD 448.50 Billion
2035 Market SizeUSD 770.53 Billion
Key Players
Teva Pharmaceutical
Sandoz
Viatris
Sun Pharmaceutical
Dr. Reddy's Laboratories
Cipla
Opportunities
  • Biosimilar Pipeline Expansion
  • Digital Pharmacy and Direct-to-Patient Channels
  • Emerging Market Expansion

Generic Drugs Market Summary

The Generic Drugs Market size was valued at USD 448.50 Billion in 2025, and the market is projected to grow from USD 475.90 Billion in 2026 to USD 770.53 Billion by 2035, registering a CAGR of 5.50% during the forecast period 2026–2035. Two catalysts are accelerating this trajectory: the expiry of blockbuster patents — including sitagliptin and apixaban, which together unlock more than USD 18 billion in annual branded revenue for substitution [1] — and the pricing mandates embedded in the U.S. Inflation Reduction Act, which are channeling payer savings toward lower-cost alternatives .

The Generic Drugs Market is undergoing a structural transformation as legacy small-molecule generics give way to complex formulations and biosimilars. Regulators worldwide have shortened review timelines; the FDA's GDUFA III staffing expansion has compressed average approval cycles, encouraging earlier competitive entry [3]. At the same time, governments in the U.S., Europe, and India are investing in API reshoring initiatives to reduce dependence on concentrated supply chains in Asia [4]. These policy-driven investments totaled more than USD 2.3 billion in committed public funding between 2023 and 2025.

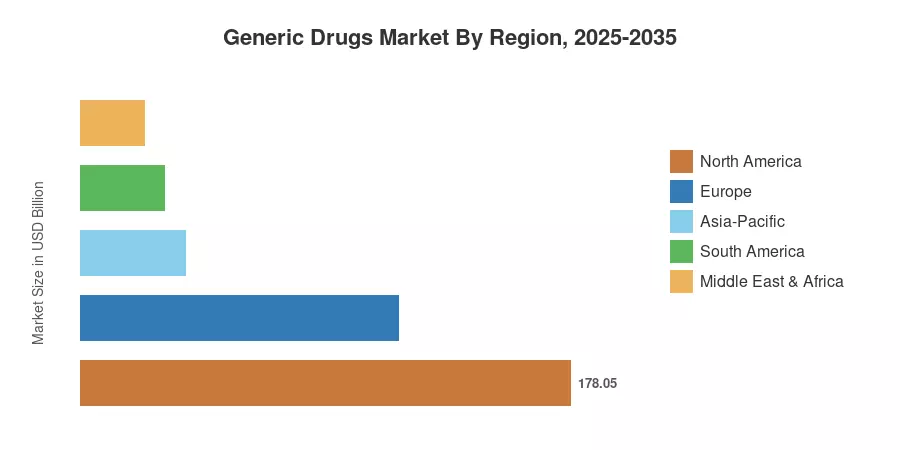
North America commands the largest share of the Generic Drugs Market at approximately 39.7% of global revenue, supported by formulary mandates and pharmacy benefit manager (PBM) substitution incentives. Asia-Pacific is the fastest-growing region with a projected CAGR of 8.52%, driven by expanding universal healthcare programs in India, China, and Southeast Asia. Europe holds the second-largest share at roughly 25.8%, anchored by centralized procurement frameworks and reference pricing systems. The decade ahead will reward companies that master complex generic development and global regulatory harmonization.


Key Report Takeaways

• By Drug Type

  • Simple generics represented approximately 57.5% of Generic Drugs Market revenue in 2025, reflecting their dominance in high-volume chronic-therapy categories.
  • Biosimilars are forecast to post the highest segment CAGR of 7.37% through 2035, driven by patent cliffs on major biologics.

• By Therapeutic Area

  • Cardiovascular agents led the Generic Drugs Market with a 52.5% revenue share in 2025.
  • Oncology products are projected to expand at a 7.89% CAGR through 2035 as branded immuno-oncology therapies lose exclusivity.

• By Region

  • North America dominated the Generic Drugs Market in 2025 with a 39.7% share.
  • Asia-Pacific is expected to register the fastest growth at an 8.52% CAGR from 2026 to 2035.


Market Size and Forecast (2021–2035)

Market Research Future employs a triangulated estimation methodology that cross-references manufacturer revenue filings, national pharmaceutical procurement databases, and payer reimbursement datasets. Historical values (2021–2024) are validated against audited industry data, while forecast estimates (2026–2035) apply a calibrated growth model accounting for patent expiry schedules, regulatory approval pipelines, and regional pricing dynamics.
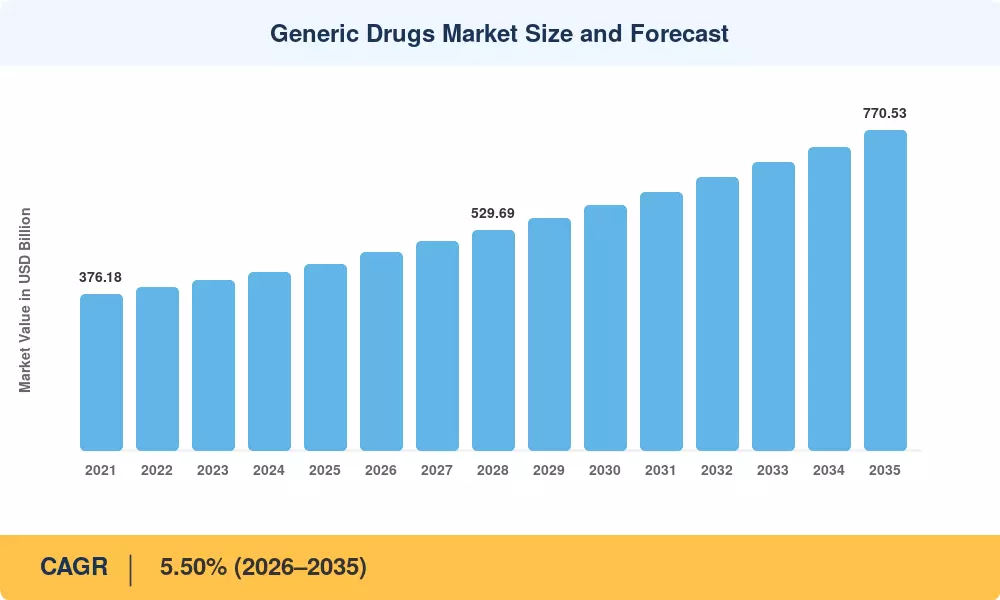
Generic Drugs Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Patent cliff acceleration ~1.4% Global Short-term (≤2 yr)
Regulatory fast-tracking (GDUFA III, EMA initiatives) ~0.9% North America, Europe Medium-term (2–4 yr)
Biosimilar adoption and formulary inclusion ~1.1% North America, Europe Medium-term (2–4 yr)
Universal healthcare expansion in emerging economies ~0.8% Asia-Pacific, South America Long-term (≥4 yr)
API supply-chain diversification and reshoring ~0.5% Global Long-term (≥4 yr)
Digital health integration and e-pharmacy growth ~0.6% Global Medium-term (2–4 yr)
Value-based procurement frameworks ~0.4% Europe, Asia-Pacific Long-term (≥4 yr)


Patent Cliff Acceleration

The ongoing patent cliff is the most important commercially since the early 2010s. Before the generic arrival, apixaban (Eliquis) alone had about USD 12 billion annual branded sales while sitagliptin (Januvia) had about USD 4 billion [1]. First-to-file exclusivity provisions in the U.S. still enable early entrants to quickly build volumes, with 180-day exclusivity periods producing disproportionate margins to subsequent entrants. This concentrated patent expiry cycle is the most significant near-term growth driver for the Generic Drugs Market.


Regulatory Fast-Tracking

Expanded staffing and performance targets contained in the FDA’s GDUFA III reauthorization dramatically lowered median review times [3]. The European Medicines Agency has also been tracking similar activities through its centralised referral mechanisms that allow for simultaneous multi-country approvals. These regulatory speed-ups reduce time-to-revenue for generic applications and encourage pipeline investment.


Biosimilar Adoption

In North America and Europe, hospital formulary committees and PBMs have been mandating biosimilar substitution with increasing frequency, particularly in the cancer and autoimmune categories [7]. In 2024, the U.S. Centers for Medicare & Medicaid Services (CMS) reported biosimilar use rates above 40% in some therapeutic groups. With this structural change, the addressable market for Generic Drugs grows outside of typical small-molecule categories.


Universal Healthcare Expansion

The Ayushman Bharat initiative in India now covers more than 500 million individuals and requires generic prescribing at every public health facility [9]. China’s volume-based procurement system has seen consecutive rounds of bidding, reducing average generic prices by more than 50%, and drastically increasing patient access and unit numbers. These programs are reshaping the Asia-Pacific generic drugs market.


Restraints Impact Analysis

The restraint estimates below represent directional headwinds on growth momentum. They should not be subtracted from driver impacts to derive net CAGR.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
API supply-chain concentration risk –0.6% Global Medium-term (2–4 yr)
Pricing erosion and margin compression –0.8% North America, Europe Short-term (≤2 yr)
Complex generic development barriers –0.5% Global Long-term (≥4 yr)
Regulatory divergence across jurisdictions –0.4% Global Long-term (≥4 yr)
Quality compliance and manufacturing recalls –0.3% Global Short-term (≤2 yr)


Pricing Erosion and Margin Compression

Competition among many approved generics for the same chemical has driven per-unit prices below sustainable criteria in a number of areas. Average yearly generic price reductions of 8–12% were observed in the U.S. market for high-competition compounds between 2021 and 2024 [16]. Margins have been squeezed, and some producers have pulled back from making low-margin products, which has resulted in shortages even in what is an oversupplied market.


API Supply-Chain Concentration

About 65–70% of world API production is concentrated in China and India, which makes it strategically vulnerable to geopolitical instability, export restrictions, and quality deficiencies [4]. These dangers were uncovered during the COVID-19 pandemic, when delays in raw-material shipments caused significant shortages across North America and Europe. Reshoring efforts have begun, but real diversification of production takes 3-5 years of capital investment.


Complex Generic Development Barriers

Complex generics — including long-acting injectables, transdermal systems, and abuse-deterrent formulations — require specialized manufacturing capabilities and extended development timelines that conventional generic firms often lack [8]. Device patents and formulation trade secrets create additional barriers that delay competitive entry well beyond small-molecule timelines, limiting growth in this high-value segment of the Generic Drugs Market.


Generic Drugs Market Opportunities

Biosimilar Pipeline Expansion

Over 50 biologic products face patent expiration between 2026 and 2032, representing more than USD 230-300 billion in combined annual branded sales [10]. Companies with integrated biologic manufacturing platforms stand to capture a significant share in the Generic Drugs Market's highest-growth segment. Early clinical development and strategic partnerships with reference-product innovators will differentiate winners.

Digital Pharmacy and Direct-to-Patient Channels

Online pharmacy platforms are projected to post the fastest distribution-channel growth through 2035, driven by consumer convenience preferences and telehealth integration [14]. This channel shift creates opportunities for generic manufacturers to build direct consumer relationships, bypassing traditional wholesaler economics.

Emerging Market Expansion

Sub-Saharan Africa and Southeast Asia remain significantly under-penetrated for generic medicines, with per-capita pharmaceutical spending below USD 30 annually in many countries [9]. WHO prequalification programs and regional pooled procurement mechanisms — such as the African Union's AMSP — are lowering market-entry barriers for quality-assured generics.

AI-Driven Formulation and Manufacturing

Artificial intelligence is transforming generic drug development by accelerating bioequivalence study design, optimizing formulation parameters, and enabling predictive quality control in continuous manufacturing . Companies deploying machine-learning platforms report 20–30% reductions in development timelines and significant yield improvements.

Contract Development and Manufacturing (CDMO) Partnerships

The growing complexity of generic portfolios is driving demand for specialized CDMO services, creating a new business model opportunity for companies with excess capacity or niche capabilities [8]. Strategic CDMO relationships allow smaller generic firms to access complex dosage-form manufacturing without full capital investment.


Generic Drugs Market Future Outlook

AI-Powered Drug Development and Quality Assurance

Machine-learning platforms are reshaping how generic manufacturers approach formulation development, bioequivalence prediction, and continuous manufacturing quality control. This efficiency gain will prove especially valuable in the Generic Drugs Market for complex formulations where traditional trial-and-error approaches are prohibitively expensive.

Supply-Chain Regionalization

The strategic push to diversify API sourcing away from concentrated production hubs will reshape manufacturing regions through 2035. The U.S. BARDA has allocated over USD 1 billion toward domestic API and finished-dosage manufacturing capacity, while the EU Pharmaceutical Strategy targets strategic autonomy for critical medicines [4]. These investments will create parallel supply networks that reduce disruption risk but increase per-unit costs for the Generic Drugs Market.

Sustainability and Green Chemistry in Manufacturing

Environmental regulations and ESG reporting requirements are pushing generic manufacturers toward solvent-recovery systems, continuous-flow chemistry, and reduced-waste API synthesis. Companies that invest early in green manufacturing will gain procurement advantages as sustainability criteria enter government tender evaluations.

Value-Based and Outcomes-Linked Pricing Models

The emergence of value-based contracts in the Generic Drugs Market signals a shift from pure price competition toward demonstrated therapeutic outcomes. Payers in the U.S. and Europe are piloting outcomes-linked agreements for biosimilars in oncology and autoimmune categories, creating opportunities for differentiated generics that demonstrate real-world effectiveness advantages .


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 39.7% share (2025) Patent cliff capture, biosimilar formulary mandates
Europe 25.8% share (2025) Reference pricing, centralized procurement
Asia-Pacific 8.52% CAGR (2026–2035) Volume-based procurement, universal coverage
South America USD 30.50 Billion (2025) Public formulary expansion, local manufacturing
Middle East & Africa 5.2% share (2025) WHO prequalification, pooled procurement
Total USD 448.50 Billion (2025) —

The Generic Drugs Market exhibits distinct regional dynamics shaped by regulatory frameworks, pricing structures, and healthcare coverage levels.


North America

Country Key Metric Key Driver
United States 72.1% of regional share PBM substitution mandates and IRA provisions
Canada 5.18% CAGR Pan-Canadian pharmaceutical procurement
Mexico USD 23.15 Billion GoBi procurement reforms


The United States remains the single largest national market for generic drugs globally, with mandatory generic substitution laws active in all 50 states and PBMs aggressively favoring low-cost alternatives. Canada's Patented Medicine Prices Review Board continues to apply international reference pricing, while Mexico's consolidated government procurement system has expanded generic access through centralized purchasing .

Europe

Country Key Metric Key Driver
Germany 22.4% of regional share Reference pricing and Aut-idem substitution
United Kingdom 4.92% CAGR NHS generic-first prescribing
France USD 18.51 Billion Tariff-based reimbursement
Italy 12.8% of regional share AIFA therapeutic equivalence lists
Spain 5.10% CAGR Regional health service procurement
Nordic Countries USD 9.26 Billion Parallel import competition
Russia 6.2% of regional share Pharma 2030 localization mandates
Rest of Europe 5.28% CAGR EU cross-border procurement


Europe's Generic Drugs Market benefits from mature regulatory frameworks and centralized reimbursement systems. Germany's automatic substitution policies and the UK's NHS generic-first prescribing culture drive high penetration rates, while Eastern European markets are growing rapidly as EU accession countries adopt reference pricing .

Asia-Pacific

Country Key Metric Key Driver
China 31.8% of regional share Volume-based procurement rounds
India 9.12% CAGR Jan Aushadhi and Ayushman Bharat
Japan USD 20.18 Billion 80% generic target policy
South Korea 7.6% of regional share HIRA reimbursement reforms
ASEAN 8.74% CAGR UHC expansion programs
Rest of Asia-Pacific USD 5.05 Billion Varied regulatory maturation


Asia-Pacific is the fastest-growing region in the Generic Drugs Market, powered by government-mandated generic substitution and expanding insurance coverage. China's centralized procurement system has driven dramatic price reductions while boosting generic utilization rates above 70% in public hospitals. India functions simultaneously as the world's largest generic exporter and a rapidly growing domestic market [9].

South America

Country Key Metric Key Driver
Brazil 52.3% of regional share ANVISA generic approval pathway
Argentina 5.84% CAGR ANMAT regulatory modernization
Rest of South America USD 7.32 Billion PAHO pooled procurement


Brazil dominates the South American Generic Drugs Market through its well-established regulatory framework and mandatory generic substitution at point of sale. Argentina's pharmaceutical sector is expanding generic penetration through updated bioequivalence requirements and pharmacy substitution legislation [18].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 22.1% of regional share Vision 2030 local manufacturing
UAE 4.96% CAGR MOHAP regulatory modernization
South Africa USD 4.66 Billion Medicines Control Council reforms
Egypt 15.2% of regional share Local manufacturing incentives
Rest of MEA 5.38% CAGR WHO prequalification access


The Middle East & Africa region presents growing opportunities as governments prioritize pharmaceutical self-sufficiency. Saudi Arabia's Vision 2030 framework includes substantial incentives for local generic manufacturing, while South Africa's procurement system increasingly favors domestically produced generics [19].


Generic Drugs Market By Region, 2025-2035

Generic Drugs Market Segmentation

By Drug Type

Segment Key Metric Primary Demand Driver
Simple Generics 57.5% share (2025) High-volume chronic-therapy substitution
Specialty Generics USD 72.45 Billion (2025) Complex formulation barriers limit competition
Biosimilars 7.37% CAGR (2026–2035) Biologic patent expirations
Complex Generics USD 48.92 Billion (2025) Device-combination and modified-release demand


Simple generics remain the volume backbone of the Generic Drugs Market, accounting for the majority of prescriptions dispensed globally. High-prevalence chronic conditions — hypertension, diabetes, hyperlipidemia — generate persistent demand for established molecules where multiple competitors ensure pricing accessibility. Biosimilars represent the fastest-growing drug type, propelled by a wave of biologic patent expirations that will open over USD 120 billion in addressable branded revenue by 2032 [10]. Manufacturers with integrated biologic development and fill-finish capabilities hold competitive advantages in this capital-intensive segment.

By Therapeutic Area

Segment Key Metric Primary Demand Driver
Cardiovascular 52.5% share (2025) Aging populations, hypertension prevalence
Oncology 7.89% CAGR (2026–2035) Branded immuno-oncology patent cliffs
Central Nervous System USD 54.18 Billion (2025) Antidepressant and antiepileptic demand
Anti-infective 4.82% CAGR (2026–2035) AMR stewardship programs


Cardiovascular generics dominate the Generic Drugs Market therapeutic mix because of the sheer patient population size and decades of accumulated off-patent molecules. Oncology generics are growing fastest as high-cost branded therapies lose exclusivity and payers push formulary committees toward lower-cost biosimilar alternatives [7].

By Route of Administration

Segment Key Metric Primary Demand Driver
Oral USD 193.62 Billion (2025) Patient compliance, manufacturing simplicity
Injectable 56.9% share (2025) Hospital and specialty pharmacy channels
Inhalable 6.44% CAGR (2026–2035) Respiratory disease burden, device-generic complexity
Topical USD 22.87 Billion (2025) Dermatology and pain management


Injectable generics hold the largest share by route of administration in the Generic Drugs Market, reflecting their predominance in hospital formularies and specialty care settings. Inhalable generics present the fastest growth trajectory, though device-patent barriers and complex bioequivalence requirements limit competitive entry [12].

By Distribution Channel

Segment Key Metric Primary Demand Driver
Hospital Pharmacies 43.6% share (2025) Institutional formulary procurement
Retail Pharmacies USD 147.52 Billion (2025) Chronic-therapy refill volumes
Online Pharmacies 9.56% CAGR (2026–2035) Telehealth integration, convenience


Hospital pharmacies lead the Generic Drugs Market distribution landscape through centralized purchasing and GPO-negotiated contracts. Online pharmacies are the fastest-growing channel as digital health platforms integrate prescription fulfillment with telehealth consultations and chronic-disease management programs [14].


Competitive Benchmarking

The Generic Drugs Market exhibits moderate concentration, with the top five players holding an estimated combined share of 28–35%. The Herfindahl-Hirschman Index falls in the low-to-moderate range, reflecting a competitive but not fragmented landscape where scale advantages in API sourcing, regulatory filing breadth, and distribution networks create meaningful barriers to entry.

Company Est. Revenue Share Range Key Offerings for Generic Drugs Market Strategic Positioning
Teva Pharmaceutical ~7–10% Broad small-molecule portfolio, biosimilars Global volume leader with integrated API production
Sandoz (Novartis) ~6–8% Biosimilars, complex generics Biosimilar pioneer with standalone spin-off focus
Viatris ~5–7% Branded generics, complex injectables Emerging market distribution strength
Sun Pharmaceutical ~4–6% Specialty generics, dermatology Vertical integration from API to finished dosage
Dr. Reddy's Laboratories ~3–5% Injectable generics, biosimilars U.S. and emerging market dual focus
Cipla ~3–5% Respiratory generics, anti-retrovirals Leading inhaled-generic pipeline
Aurobindo Pharma ~3–4% Oral solids, injectable portfolio High-volume, cost-competitive manufacturing
Hikma Pharmaceuticals ~2–4% Injectable generics, branded generics MENA regional dominance
Fresenius Kabi ~2–3% IV generics, biosimilars Hospital-channel specialization
Amneal Pharmaceuticals ~2–3% Complex oral solids, specialty generics U.S.-focused differentiated portfolio


Recent News & Developments

  • Sandoz (October 2023): Completed spin-off from Novartis and announced a USD 500 million biosimilar pipeline investment targeting five new launches by 2027 [21].
  • Teva Pharmaceutical (July 2024): Partnered with Samsung Bioepis to secure FDA approval for EPYSQLI (eculizumab-aagh), an advanced biosimilar referencing Soliris, expanding its sterile specialized distribution footprint within the United States market.
  • U.S. FDA (March 2024): Issued its finalized industry guidance titled "Controlled Correspondence Related to Generic Drug Development," establishing explicit communication frameworks and strict response timelines to accelerate ongoing Abbreviated New Drug Application (ANDA) reviews.


  • ].
  • European Commission (April 2023): Proposed revisions to the EU Pharmaceutical Legislation, including shortened data-exclusivity periods to accelerate generic and biosimilar entry across member states [13].


Generic Drugs Market Report Scope

Parameter Detail
Market Scope Global Generic Drugs Market by drug type, therapeutic area, route of administration, distribution channel, and region
Study Period 2021–2035
CAGR (Forecast Period) 5.50% (2026–2035)
Market Size — Base Year (2025) USD 448.50 Billion
Market Size — Forecast Endpoint (2035) USD 770.53 Billion
Fastest Growing Segment Biosimilars (by drug type); Oncology (by therapeutic area); Online Pharmacies (by distribution channel)
Companies Profiled 10 (Teva, Sandoz, Viatris, Sun Pharma, Dr. Reddy's, Cipla, Aurobindo, Hikma, Fresenius Kabi, Amneal)
Valuation Currency USD Billion

FAQs

How do generic drug price deflation cycles affect manufacturer profitability?
Sustained price erosion compresses margins below reinvestment thresholds, forcing companies to exit low-competition molecules. Profitable manufacturers offset deflation by scaling into complex and specialty categories [16].
What differentiates a 505(b)(2) pathway from a standard generic application?
The 505(b)(2) pathway allows applicants to reference prior FDA findings while adding proprietary clinical data. This route suits modified-release and combination products that cannot use standard abbreviated filings [8].
How do pharmacy benefit managers influence generic drug adoption rates?
PBMs set formulary tier placement and mandatory substitution rules that directly determine dispensing volumes. Their rebate negotiations with branded manufacturers also shape the competitive price floor for generics [7].
What manufacturing capabilities are needed for complex generic development?
Complex generics require specialized equipment for modified-release, long-acting injectable, or device-combination production. Manufacturers also need advanced analytical methods for characterization studies [8].
How does API sourcing region affect supply-chain resilience?
Concentrated API production in two countries creates single-point-of-failure risks during geopolitical or pandemic disruptions. Dual-sourcing and regional stockpiling are emerging mitigation strategies [4].
What role do interchangeability designations play in biosimilar uptake?
Interchangeability status allows pharmacists to substitute biosimilars without prescriber intervention. This designation accelerates volume capture by removing a key institutional friction point [7].
How are real-world evidence studies reshaping the Generic Drugs Market?
Payers increasingly require post-market effectiveness data to justify formulary placement for higher-cost generics. Real-world evidence differentiates quality-focused manufacturers from commodity suppliers .    
What is the current size of the generic drugs market?
The generic drugs market reached USD 448.50 billion in 2025 and is projected to reach USD 770.53 billion by 2035.
What is the CAGR of the generic drugs market?
The generic drugs market is projected to grow at a CAGR of 5.50% during the forecast period 2026–2035.
Which region leads the generic drugs market?
North America holds the largest share at 39.7%, while Asia-Pacific is the fastest-growing region at 8.52% CAGR.
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author Co-Author Profile Kinjoll Dey LinkedIn Senior Research Analyst
He is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Kinjoll is comfortably versed in data centric research backed by healthcare educational background. He leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. His key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, he showcases extensive affinity towards learning new skills and remain fascinated in implementing them.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















