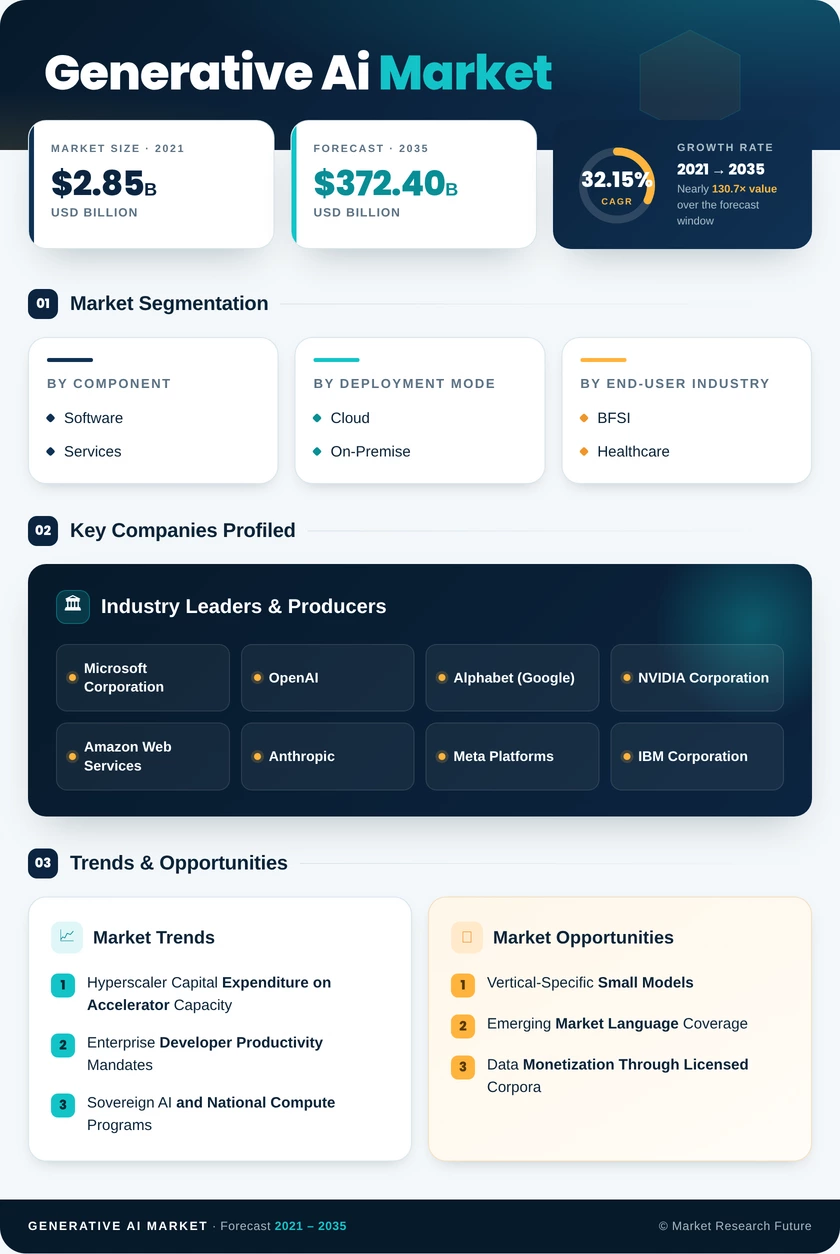
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Component | Software; Services | Software (59.80% share, 2025) | Services (40.15% CAGR) |
| By Deployment Mode | Cloud; On-Premise | Cloud (USD 15.15 Billion, 2025) | On-Premise (45.30% CAGR) |
| By End-User Industry | BFSI; Healthcare | BFSI (20.65% share, 2025) | Healthcare (33.60% CAGR) |
| By Application | Content Creation; Code Generation | Content Creation (32.85% share, 2025) | Code Generation (45.85% CAGR) |
| By Model Architecture | GAN; Transformer; Diffusion | Transformer (54.20% share, 2025) | Diffusion (41.20% CAGR) |
| By Organisation Size | Large Enterprises; Small and Medium Enterprises | Large Enterprises (USD 15.55 Billion, 2025) | Small and Medium Enterprises (38.40% CAGR) |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
| Software | Platform layers absorb model routing, prompt management, and output validation |
| Services | Advisory engagements bundle risk assessment with implementation into multi-year contracts |
Software leads at 59.80% of 2025 revenue because every production deployment routes through an orchestration and validation layer regardless of which model sits underneath. Services grow fastest at a 40.15% CAGR for a skills reason rather than a technology one: enterprises can license a platform far faster than they can hire people who know how to fine-tune, evaluate, and monitor models against regulated workflows. Integrators have responded by attaching governance audits to deployment scopes, which converts one-time projects into recurring monitoring revenue. The gap narrows over the forecast window without closing.
By Deployment Mode
| Sub-Segment | Key Trend |
| Cloud | Consumption pricing removes capital approval barriers for experimentation |
| On-Premise | Sovereignty rules and latency ceilings force local inference in production |
Cloud accounted for USD 15.15 billion in 2025 because pilots began where no hardware purchase was required. On-Premise grows fastest at a 45.30% CAGR as those pilots reach production and encounter constraints pilots never tested — sub-100-millisecond response requirements in manufacturing inspection, and data-residency statutes that prohibit regulated records leaving a jurisdiction entirely. Buyers increasingly specify hybrid routing at the architecture stage rather than migrating later, which favours vendors shipping identical toolchains across both modes.
By End-User Industry
| Sub-Segment | Key Trend |
| BFSI | Audit-ready models required for conversational service and fraud analytics |
| Healthcare | Ambient documentation and imaging triage scale on clearer device authorization pathways |
BFSI holds 20.65% of 2025 revenue because banks and insurers combine enormous unstructured document volumes with existing model-governance functions borrowed from credit risk. Healthcare compounds faster at a 33.60% CAGR from a smaller base, where the buying case rests on clinician time recovered from charting rather than on new revenue. Both verticals buy for auditability first and capability second, which is why vendors selling into them lead with evaluation logs and evidence packages rather than benchmark scores.
By Application
| Sub-Segment | Key Trend |
| Content Creation | Marketing and media production volume absorbs generated text, image, and video |
| Code Generation | Instrumentable throughput gains make finance approval straightforward |
Content Creation captured 32.85% of 2025 application revenue because output is usable immediately and quality thresholds are negotiable at the draft stage. Code Generation grows fastest at a 45.85% CAGR precisely because engineering organizations already measure cycle time and pull-request throughput, so the productivity claim survives finance scrutiny that creative applications cannot always withstand. Scope has widened past suggestion into test synthesis, documentation, and refactoring, expanding addressable spend per developer seat.
By Model Architecture
| Sub-Segment | Key Trend |
| GAN | Synthetic tabular data for privacy-preserving analytics on constrained hardware |
| Transformer | Single architecture serves language, audio, and cross-modal reasoning |
| Diffusion | Video and molecular generation quality crosses commercial thresholds |
Transformer designs hold 54.20% of 2025 deployments because one architecture family covers text, speech, and multimodal reasoning, letting vendors amortize tooling investment across every application they sell. Diffusion grows fastest at a 41.20% CAGR as video generation and molecular structure prediction reach quality levels that justify production budgets. GAN implementations persist in defined niches — synthetic record generation for privacy-constrained analytics — where training efficiency on modest hardware still beats newer alternatives.
By Organisation Size
| Sub-Segment | Key Trend |
| Large Enterprises | Integration capacity and compliance budget enable custom deployment |
| Small and Medium Enterprises | Packaged vertical applications remove the integration requirement entirely |
Large Enterprises generated USD 15.55 billion in 2025 because meaningful deployment demands data engineering, security review, and change management that only sizeable IT functions can staff. Small and Medium Enterprises grow fastest at a 38.40% CAGR as vendors package capability into workflow products — an accounting practice buys document automation, not a model endpoint. Falling list prices matter more to this group than to enterprises, since smaller buyers lack the volume commitments that secure negotiated discounts.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA