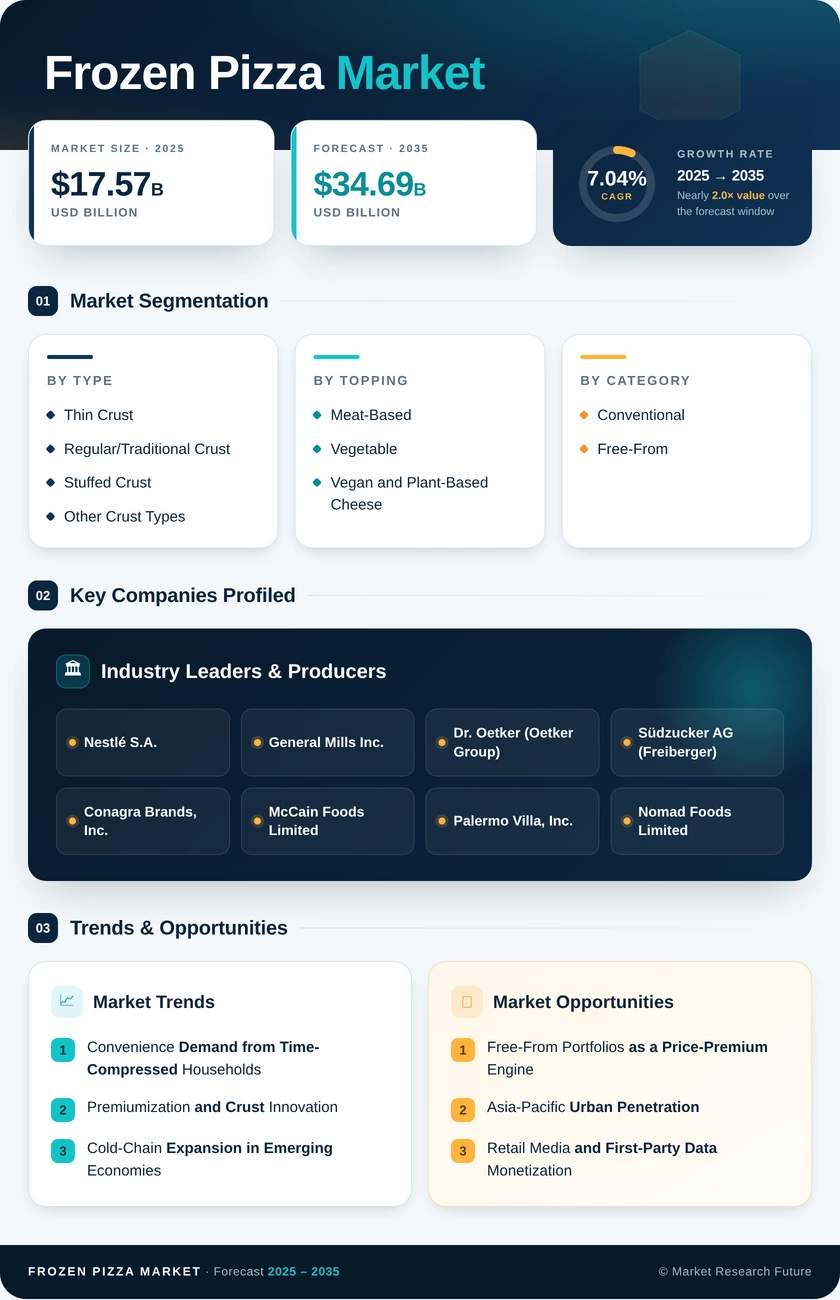
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Crust Type | Thin Crust; Regular/Traditional Crust; Stuffed Crust; Other Crust Types | Thin Crust | Stuffed Crust |
| By Topping | Meat-Based; Vegetable; Vegan and Plant-Based Cheese | Meat-Based | Vegan and Plant-Based Cheese |
| By Category | Free-From; Conventional | Conventional | Free-From |
| By Distribution Channel | Foodservice; Retail | Retail | Foodservice |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Crust Type
| Sub-Segment | Key Trend |
| Thin Crust | Health-halo positioning and faster bake times sustain leadership across mature markets |
| Regular/Traditional Crust | Anchors family-size value occasions and private-label programs |
| Stuffed Crust | Direct imitation of quick-service indulgence formats drives fastest growth |
| Other Crust Types | Cauliflower, sourdough and multigrain bases expand the premium free-from tier |
Crust selection dictates line capability more than any other variable. Producers with sealed-edge and sheeting flexibility can pivot between value and indulgence tiers as promotional calendars shift, while single-format plants remain exposed to mix change.
By Topping
| Sub-Segment | Key Trend |
| Meat-Based | Pepperoni and sausage remain default household choices with stable repeat rates |
| Vegetable | Flexitarian adoption lifts mixed-vegetable and Mediterranean-style profiles |
| Vegan and Plant-Based Cheese | Improved melt and browning performance unlocks mainstream distribution |
Topping innovation is the fastest feedback loop in the category. New flavour profiles reach shelf within two quarters, letting brands test regional preferences at low capital risk before committing to broader rollout.
By Category
| Sub-Segment | Key Trend |
| Conventional | Retains volume leadership through price accessibility and universal distribution |
| Free-From | Gluten, dairy, and additive avoidance sustains premium pricing and margin expansion |
Free-from lines require dedicated allergen-controlled capacity, which raises the entry barrier and concentrates supply. That structural constraint is precisely what preserves the segment's pricing power as volumes scale.
By Distribution Channel
| Sub-Segment | Key Trend |
| Retail | Freezer-aisle assortment breadth and private-label growth sustain the volume base |
| Foodservice | Convenience-store hot cases and institutional catering drive the steepest recovery |
Channel strategy increasingly determines pack architecture. Multipacks serve club and discount formats, single-serve suits quick commerce, and par-baked bases serve foodservice — three distinct production specifications from one core dough platform.
By Region
| Sub-Segment | Key Trend |
| North America | Premiumization and refrigerant-compliance capex define the mature-market playbook |
| Europe | Clean-label regulation and contract manufacturing depth shape competitive structure |
| Asia-Pacific | Cold-chain buildout and localized flavour development unlock the fastest growth |
| South America | Domestic manufacturing strength offsets currency and labelling pressures |
| Middle East & Africa | Halal certification and hospitality demand anchor Gulf-led expansion |
Geographic strategy now follows infrastructure rather than demographics. Freezer density in modern trade is the single best predictor of category headroom, which is why capacity planning increasingly precedes brand investment in emerging regions.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA