Freight Forwarding Services Market

Freight Forwarding Services Market Size, Share and Trends Analysis Research Report Information By End User (Manufacturing, Retail, E-commerce, Pharma, Automotive), By Cargo Type (General, Hazardous, Perishable, Heavy, Liquid), By Service Type (Air, Ocean, Land Freight, Customs, Logistics), By Shipment Type (FCL, LCL, Bulk, Break Bulk, Reefer), By Transportation Mode (Road, Rail, Air, Sea, Intermodal), And By Region – Market Forecast Till 2035.

Forecast Period
2025 - 2035
CAGR
3.07%
2024 Market Size
$ 208 Billion
2035 Market Size
$ 290 Billion
Professional Services ● Updated March 28, 2026 Report ID: MRFR/PS/65021-HCR | Pages: 200 | Author: Rahul Gotadki, Garvit Vyas

Freight Forwarding Services Market Summary

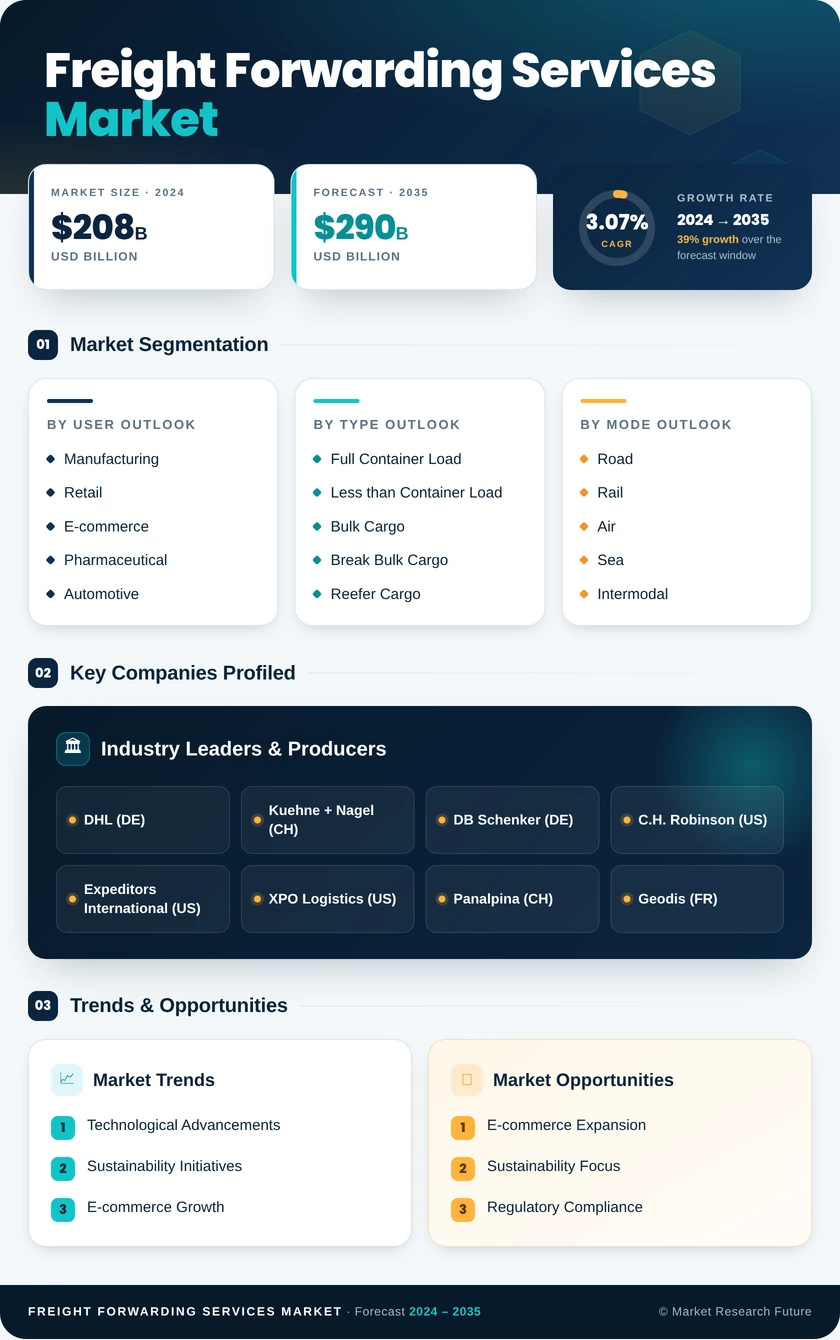
As per MRFR analysis, the Freight Forwarding Services Market Size was estimated at 208.0 USD Billion in 2024. The Freight Forwarding Services industry is projected to grow from 214.39 USD Billion in 2025 to 290.0 USD Billion by 2035, exhibiting a compound annual growth rate (CAGR) of 3.07% during the forecast period 2025 - 2035.

Key Market Trends & Highlights

The Freight Forwarding Services Market is experiencing dynamic growth driven by technological advancements and increasing trade volumes.

  • Technological advancements are reshaping operational efficiencies in the freight forwarding sector.
  • Sustainability initiatives are becoming increasingly critical as companies seek to reduce their carbon footprints.
  • E-commerce growth is significantly influencing logistics strategies, particularly in the Asia-Pacific region.
  • Increasing trade volumes and e-commerce expansion are major drivers propelling the market forward.

Market Size & Forecast

2024 Market Size 208.0 (USD Billion)
2035 Market Size 290.0 (USD Billion)
CAGR (2025 - 2035) 3.07%

Major Players

DHL (DE), Kuehne + Nagel (CH), DB Schenker (DE), C.H. Robinson (US), Expeditors International (US), XPO Logistics (US), Panalpina (CH), Geodis (FR), Sinotrans (CN), Nippon Express (JP)
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Freight Forwarding Services Market Drivers

E-commerce Expansion

The rapid expansion of e-commerce is significantly influencing the Freight Forwarding Services Market. As online shopping continues to gain traction, the need for efficient logistics solutions becomes paramount. In 2025, e-commerce sales are projected to surpass 6 trillion USD, creating a substantial demand for freight forwarding services to facilitate the movement of goods from suppliers to consumers. This trend is particularly evident in the rise of last-mile delivery services, which require specialized logistics solutions. Freight forwarders are increasingly adapting their offerings to cater to the unique needs of e-commerce businesses, thereby driving growth within the Freight Forwarding Services Market. The ability to provide timely and reliable delivery options is becoming a key differentiator in this competitive landscape.

Sustainability Focus

The growing emphasis on sustainability is becoming a pivotal driver within the Freight Forwarding Services Market. As businesses increasingly prioritize environmentally friendly practices, there is a rising demand for sustainable logistics solutions. Freight forwarders are responding by adopting greener practices, such as optimizing transportation routes, utilizing eco-friendly packaging, and investing in carbon offset programs. In 2025, it is projected that the market for sustainable logistics will reach approximately 300 billion USD, reflecting a shift towards more responsible supply chain practices. This focus on sustainability not only aligns with consumer preferences but also enhances the reputation of freight forwarders, making them more attractive to environmentally conscious clients. As a result, the Freight Forwarding Services Market is likely to see continued growth driven by this sustainability imperative.

Regulatory Compliance

The Freight Forwarding Services Market is also shaped by the increasing complexity of regulatory compliance requirements across various regions. As governments implement stricter regulations regarding customs, safety, and environmental standards, freight forwarders must navigate these challenges to ensure compliance. This necessity creates a demand for specialized services that can assist businesses in adhering to local and international regulations. In 2025, it is anticipated that compliance-related services will account for a significant portion of the revenue generated within the Freight Forwarding Services Market. Consequently, freight forwarders that invest in compliance expertise and technology are likely to gain a competitive edge, positioning themselves as trusted partners for businesses seeking to mitigate risks associated with regulatory non-compliance.

Increasing Trade Volumes

The Freight Forwarding Services Market is experiencing a notable surge in trade volumes, driven by the expansion of international trade agreements and the liberalization of trade policies. As countries engage in more cross-border transactions, the demand for efficient logistics solutions intensifies. In 2025, the total value of global merchandise trade is projected to reach approximately 25 trillion USD, indicating a robust growth trajectory. This increase in trade volumes necessitates the services of freight forwarders, who play a crucial role in managing the complexities of shipping and logistics. Consequently, the Freight Forwarding Services Market is likely to benefit from this upward trend, as businesses seek reliable partners to navigate the intricacies of global supply chains.

Technological Integration

The integration of advanced technologies within the Freight Forwarding Services Market is transforming operational efficiencies and customer experiences. Innovations such as artificial intelligence, blockchain, and the Internet of Things are being adopted to streamline processes, enhance tracking capabilities, and improve transparency. For instance, the implementation of blockchain technology can reduce paperwork and expedite customs clearance, thereby minimizing delays. As of 2025, it is estimated that around 60% of freight forwarders are utilizing some form of technology to optimize their services. This technological shift not only enhances service delivery but also positions the Freight Forwarding Services Market as a more competitive and agile sector, capable of adapting to the evolving demands of clients.

Market Segment Insights

By Service Type: Air Freight (Largest) vs. Ocean Freight (Fastest-Growing)

In the Freight Forwarding Services Market, the service type segment reveals a diverse distribution of market share among its key players. Air Freight currently holds the largest share, favored for its speed and reliability, catering to businesses that require quick delivery of goods. Conversely, Ocean Freight, though historically significant, is rapidly gaining momentum as global trade expands, driven by its cost-effectiveness for bulk shipments. This dynamic illustrates the contrasting priorities of urgency and economics among companies in different sectors. Growth trends in this segment are significantly influenced by globalization and emerging markets. Air Freight continues to dominate, driven by demand in e-commerce and high-value goods transportation. Meanwhile, Ocean Freight is witnessing rapid growth, primarily fueled by increased trade volume and investments in port infrastructure. The evolving logistics landscape and advancements in technology also promote efficiency, aligning with the rising expectations for integrated service offerings that include Customs Brokerage and Logistics Management.

Air Freight (Dominant) vs. Logistics Management (Emerging)

Air Freight is currently the dominant service in the Freight Forwarding Services Market, known for its swift delivery times and critical role in international trade, especially for high-value and perishable goods. Its strategic advantage lies in its ability to reduce lead times, making it essential for industries like electronics and pharmaceuticals. In contrast, Logistics Management has emerged as a vital service, gaining traction as companies seek to optimize their supply chains. This segment focuses on integrating various logistics processes to enhance efficiency and reduce costs, thereby catering to the increasing complexity of global supply chains. The growth in e-commerce and demand for seamless service integration has propelled Logistics Management into prominence, positioning it as a key player in the evolving freight landscape.

By End User: Manufacturing (Largest) vs. E-commerce (Fastest-Growing)

In the Freight Forwarding Services Market, the manufacturing sector holds the largest share, driven by the continuous need for raw materials and finished goods to be transported efficiently. This segment represents a significant portion of freight traffic, ensuring timely deliveries and enhancing supply chain effectiveness. Meanwhile, the e-commerce sector is rapidly gaining traction, fueled by the growing trend of online shopping and increasing consumer demand for quick delivery services. As businesses pivot towards digital platforms, the e-commerce segment is projected to expand its footprint in the freight forwarding arena.

Manufacturing (Dominant) vs. E-commerce (Emerging)

The manufacturing segment in freight forwarding is characterized by its reliance on intricately organized logistics operations to handle large volumes of goods. This sector emphasizes efficiency in transporting components to assembly lines and finished products to markets, often requiring specialized freight services. On the other hand, the emerging e-commerce segment is increasingly demanding innovative solutions that cater to expedited shipping and last-mile delivery. With a surge in online retail, e-commerce stakeholders are prioritizing flexibility and speed, creating a unique set of challenges and opportunities for freight forwarders. Companies are adapting to these dynamics by enhancing their technological capabilities to streamline operations and meet customer expectations.

By Shipment Type: Full Container Load (Largest) vs. Less than Container Load (Fastest-Growing)

In the Freight Forwarding Services Market, the shipment type segment is characterized by distinct categories such as Full Container Load (FCL), Less than Container Load (LCL), Bulk Cargo, Break Bulk Cargo, and Reefer Cargo. Full Container Load has emerged as the largest segment, as it caters to businesses requiring dedicated shipping solutions that efficiently manage large volumes of goods. Conversely, Less than Container Load, which involves the consolidation of shipments from various customers, is gaining traction rapidly, addressing the growing demand for flexible shipping solutions among small to medium enterprises.

Full Container Load (Dominant) vs. Less than Container Load (Emerging)

Full Container Load (FCL) represents a significant portion of the shipment types due to its advantages in terms of cost-efficiency for large shipments, security during transit, and reduced handling risks. It allows shippers to utilize an entire container, minimizing the chances of damage and theft. In contrast, Less than Container Load (LCL) is increasingly favored by businesses seeking cost-effective logistics solutions. With the rising trend of e-commerce and SMEs entering global markets, LCL provides smaller businesses with access to competitive shipping rates without the need for full container commitments, making it an emerging player in the freight forwarding landscape.

By Transportation Mode: Road (Largest) vs. Air (Fastest-Growing)

In the Freight Forwarding Services Market, the transportation mode segment reflects diverse dynamics, with Road transport holding the largest market share due to its extensive infrastructure and flexibility. Road transport benefits from its ability to facilitate short-haul deliveries globally, making it a preferred choice across various industries, including retail and manufacturing. In contrast, Air transport, while representing a smaller share, is rapidly gaining traction due to its ability to expedite deliveries and meet the demand for speed in e-commerce and time-sensitive shipments.

Road (Dominant) vs. Air (Emerging)

Road transport dominates the Freight Forwarding Services segment, thanks to its vast network and integration with last-mile delivery solutions, making it indispensable for local and regional shipments. It offers unparalleled flexibility and cost-effectiveness, catering to various cargo types. However, the Air transport segment is emerging rapidly, driven by increasing e-commerce activities and the need for quicker delivery options. Air freight services are becoming crucial for high-value and perishable goods, allowing businesses to meet stringent delivery timelines. As companies prioritize efficiency and speed, the Air transport segment is expected to continue growing, enhancing its market positioning.

By Cargo Type: General Cargo (Largest) vs. Perishable Goods (Fastest-Growing)

In the Freight Forwarding Services Market, General Cargo emerges as the largest segment, accounting for a significant share of the market. This segment encompasses a wide range of goods that do not require special handling, making it a versatile and essential part of logistics operations. It contributes to a majority of the freight volume and is favored by businesses for its reliability and efficiency in transportation. Meanwhile, Perishable Goods are gaining momentum as the fastest-growing segment, driven by the increasing demand for fresh produce and temperature-sensitive items. The expansion of e-commerce and changes in consumer behavior further drive this growth, highlighting the need for specialized logistics solutions.

General Cargo (Dominant) vs. Perishable Goods (Emerging)

General Cargo in the Freight Forwarding Services Market stands out due to its breadth and ease of transport, covering a multitude of items from manufactured products to everyday supplies. It serves as the backbone for many industries, promoting efficiency and resilience in supply chains. On the other hand, Perishable Goods represent an emerging segment characterized by the necessity for time-sensitive shipping solutions. The rise in online grocery shopping and consumer preferences for fresh food are catalyzing growth in this area. This segment requires advanced temperature control and handling methods, making logistics providers focus on technological innovations and improving turnaround times to stay competitive.

Get more detailed insights about Freight Forwarding Services Market Request Free Sample

Key Players and Competitive Insights

The Freight Forwarding Services Market is currently characterized by a dynamic competitive landscape, driven by globalization, e-commerce growth, and technological advancements. Major players such as DHL (DE), Kuehne + Nagel (CH), and DB Schenker (DE) are strategically positioned to leverage these trends. DHL (DE) focuses on innovation and digital transformation, enhancing its logistics capabilities through advanced technologies. Kuehne + Nagel (CH) emphasizes sustainability and operational efficiency, while DB Schenker (DE) is actively pursuing regional expansion and strategic partnerships to bolster its market presence. Collectively, these strategies contribute to a competitive environment that is increasingly shaped by technological integration and customer-centric solutions.Key business tactics within the Freight Forwarding Services Market include supply chain optimization and localized service offerings. The market structure appears moderately fragmented, with a mix of large multinational corporations and smaller regional players. The influence of key players is substantial, as they set industry standards and drive innovation, thereby shaping customer expectations and competitive dynamics.
In November DHL (DE) announced a significant investment in AI-driven logistics solutions aimed at enhancing operational efficiency and customer service. This strategic move underscores the company's commitment to digital transformation, positioning it to better meet the evolving demands of the market. By integrating AI technologies, DHL (DE) aims to streamline its operations, reduce costs, and improve delivery times, which could potentially enhance its competitive edge.
In October Kuehne + Nagel (CH) launched a new sustainability initiative focused on reducing carbon emissions across its supply chain. This initiative is particularly relevant as environmental concerns continue to gain prominence among consumers and businesses alike. By prioritizing sustainability, Kuehne + Nagel (CH) not only addresses regulatory pressures but also aligns itself with the growing demand for eco-friendly logistics solutions, thereby enhancing its brand reputation and customer loyalty.
In September DB Schenker (DE) entered into a strategic partnership with a leading technology firm to develop advanced logistics software. This collaboration aims to enhance supply chain visibility and efficiency through real-time data analytics. The strategic importance of this partnership lies in its potential to provide DB Schenker (DE) with a competitive advantage by offering clients improved insights and control over their logistics operations, which is increasingly critical in today's fast-paced market.
As of December current competitive trends in the Freight Forwarding Services Market are heavily influenced by digitalization, sustainability, and AI integration. Strategic alliances are becoming more prevalent, as companies seek to enhance their service offerings and operational capabilities. The competitive differentiation is likely to evolve from traditional price-based competition to a focus on innovation, technology, and supply chain reliability. This shift indicates that companies that can effectively leverage technology and sustainability will be better positioned to thrive in the future.

Key Companies in the Freight Forwarding Services Market include

Future Outlook

Freight Forwarding Services Market Future Outlook

The Freight Forwarding Services Market is projected to grow at a 3.07% CAGR from 2025 to 2035, driven by e-commerce expansion, technological advancements, and increasing global trade.

New opportunities lie in:

  • Integration of AI-driven logistics management systems Expansion of green logistics solutions Development of blockchain-based supply chain transparency tools

By 2035, the market is expected to be robust, reflecting sustained growth and innovation.

Market Segmentation

Freight Forwarding Services Market End User Outlook

  • Manufacturing
  • Retail
  • E-commerce
  • Pharmaceutical
  • Automotive

Freight Forwarding Services Market Cargo Type Outlook

  • General Cargo
  • Hazardous Cargo
  • Perishable Goods
  • Heavy Equipment
  • Liquid Cargo

Freight Forwarding Services Market Service Type Outlook

  • Air Freight
  • Ocean Freight
  • Land Freight
  • Customs Brokerage
  • Logistics Management

Freight Forwarding Services Market Shipment Type Outlook

  • Full Container Load
  • Less than Container Load
  • Bulk Cargo
  • Break Bulk Cargo
  • Reefer Cargo

Freight Forwarding Services Market Transportation Mode Outlook

  • Road
  • Rail
  • Air
  • Sea
  • Intermodal

Report Scope

MARKET SIZE 2024 208.0(USD Billion)
MARKET SIZE 2025 214.39(USD Billion)
MARKET SIZE 2035 290.0(USD Billion)
COMPOUND ANNUAL GROWTH RATE (CAGR) 3.07% (2025 - 2035)
REPORT COVERAGE Revenue Forecast, Competitive Landscape, Growth Factors, and Trends
BASE YEAR 2024
Market Forecast Period 2025 - 2035
Historical Data 2019 - 2024
Market Forecast Units USD Billion
Key Companies Profiled DHL (DE), Kuehne + Nagel (CH), DB Schenker (DE), C.H. Robinson (US), Expeditors International (US), XPO Logistics (US), Panalpina (CH), Geodis (FR), Sinotrans (CN), Nippon Express (JP)
Segments Covered Service Type, End User, Shipment Type, Transportation Mode, Cargo Type
Key Market Opportunities Integration of advanced technologies enhances efficiency in the Freight Forwarding Services Market.
Key Market Dynamics Technological advancements and regulatory changes are reshaping competitive dynamics in the Freight Forwarding Services Market.
Countries Covered North America, Europe, APAC, South America, MEA

Table of Contents

  1. 1 SECTION I: EXECUTIVE SUMMARY AND KEY HIGHLIGHTS
    1. 1.1 EXECUTIVE SUMMARY
      1. 1.1.1 Market Overview
      2. 1.1.2 Key Findings
      3. 1.1.3 Market Segmentation
      4. 1.1.4 Competitive Landscape
      5. 1.1.5 Challenges and Opportunities
      6. 1.1.6 Future Outlook
  2. 2 SECTION II: SCOPING, METHODOLOGY AND MARKET STRUCTURE
    1. 2.1 MARKET INTRODUCTION
      1. 2.1.1 Definition
      2. 2.1.2 Scope of the study
        1. 2.1.2.1 Research Objective
        2. 2.1.2.2 Assumption
        3. 2.1.2.3 Limitations
    2. 2.2 RESEARCH METHODOLOGY
      1. 2.2.1 Overview
      2. 2.2.2 Data Mining
      3. 2.2.3 Secondary Research
      4. 2.2.4 Primary Research
        1. 2.2.4.1 Primary Interviews and Information Gathering Process
        2. 2.2.4.2 Breakdown of Primary Respondents
      5. 2.2.5 Forecasting Model
      6. 2.2.6 Market Size Estimation
        1. 2.2.6.1 Bottom-Up Approach
        2. 2.2.6.2 Top-Down Approach
      7. 2.2.7 Data Triangulation
      8. 2.2.8 Validation
  3. 3 SECTION III: QUALITATIVE ANALYSIS
    1. 3.1 MARKET DYNAMICS
      1. 3.1.1 Overview
      2. 3.1.2 Drivers
      3. 3.1.3 Restraints
      4. 3.1.4 Opportunities
    2. 3.2 MARKET FACTOR ANALYSIS
      1. 3.2.1 Value chain Analysis
      2. 3.2.2 Porter's Five Forces Analysis
        1. 3.2.2.1 Bargaining Power of Suppliers
        2. 3.2.2.2 Bargaining Power of Buyers
        3. 3.2.2.3 Threat of New Entrants
        4. 3.2.2.4 Threat of Substitutes
        5. 3.2.2.5 Intensity of Rivalry
      3. 3.2.3 COVID-19 Impact Analysis
        1. 3.2.3.1 Market Impact Analysis
        2. 3.2.3.2 Regional Impact
        3. 3.2.3.3 Opportunity and Threat Analysis
  4. 4 SECTION IV: QUANTITATIVE ANALYSIS
    1. 4.1 Food, Beverages & Nutrition, BY Service Type (USD Billion)
      1. 4.1.1 Air Freight
      2. 4.1.2 Ocean Freight
      3. 4.1.3 Land Freight
      4. 4.1.4 Customs Brokerage
      5. 4.1.5 Logistics Management
    2. 4.2 Food, Beverages & Nutrition, BY End User (USD Billion)
      1. 4.2.1 Manufacturing
      2. 4.2.2 Retail
      3. 4.2.3 E-commerce
      4. 4.2.4 Pharmaceutical
      5. 4.2.5 Automotive
    3. 4.3 Food, Beverages & Nutrition, BY Shipment Type (USD Billion)
      1. 4.3.1 Full Container Load
      2. 4.3.2 Less than Container Load
      3. 4.3.3 Bulk Cargo
      4. 4.3.4 Break Bulk Cargo
      5. 4.3.5 Reefer Cargo
    4. 4.4 Food, Beverages & Nutrition, BY Transportation Mode (USD Billion)
      1. 4.4.1 Road
      2. 4.4.2 Rail
      3. 4.4.3 Air
      4. 4.4.4 Sea
      5. 4.4.5 Intermodal
    5. 4.5 Food, Beverages & Nutrition, BY Cargo Type (USD Billion)
      1. 4.5.1 General Cargo
      2. 4.5.2 Hazardous Cargo
      3. 4.5.3 Perishable Goods
      4. 4.5.4 Heavy Equipment
      5. 4.5.5 Liquid Cargo
    6. 4.6 Food, Beverages & Nutrition, BY Region (USD Billion)
      1. 4.6.1 North America
        1. 4.6.1.1 US
        2. 4.6.1.2 Canada
      2. 4.6.2 Europe
        1. 4.6.2.1 Germany
        2. 4.6.2.2 UK
        3. 4.6.2.3 France
        4. 4.6.2.4 Russia
        5. 4.6.2.5 Italy
        6. 4.6.2.6 Spain
        7. 4.6.2.7 Rest of Europe
      3. 4.6.3 APAC
        1. 4.6.3.1 China
        2. 4.6.3.2 India
        3. 4.6.3.3 Japan
        4. 4.6.3.4 South Korea
        5. 4.6.3.5 Malaysia
        6. 4.6.3.6 Thailand
        7. 4.6.3.7 Indonesia
        8. 4.6.3.8 Rest of APAC
      4. 4.6.4 South America
        1. 4.6.4.1 Brazil
        2. 4.6.4.2 Mexico
        3. 4.6.4.3 Argentina
        4. 4.6.4.4 Rest of South America
      5. 4.6.5 MEA
        1. 4.6.5.1 GCC Countries
        2. 4.6.5.2 South Africa
        3. 4.6.5.3 Rest of MEA
  5. 5 SECTION V: COMPETITIVE ANALYSIS
    1. 5.1 Competitive Landscape
      1. 5.1.1 Overview
      2. 5.1.2 Competitive Analysis
      3. 5.1.3 Market share Analysis
      4. 5.1.4 Major Growth Strategy in the Food, Beverages & Nutrition
      5. 5.1.5 Competitive Benchmarking
      6. 5.1.6 Leading Players in Terms of Number of Developments in the Food, Beverages & Nutrition
      7. 5.1.7 Key developments and growth strategies
        1. 5.1.7.1 New Product Launch/Service Deployment
        2. 5.1.7.2 Merger & Acquisitions
        3. 5.1.7.3 Joint Ventures
      8. 5.1.8 Major Players Financial Matrix
        1. 5.1.8.1 Sales and Operating Income
        2. 5.1.8.2 Major Players R&D Expenditure. 2023
    2. 5.2 Company Profiles
      1. 5.2.1 DHL (DE)
        1. 5.2.1.1 Financial Overview
        2. 5.2.1.2 Products Offered
        3. 5.2.1.3 Key Developments
        4. 5.2.1.4 SWOT Analysis
        5. 5.2.1.5 Key Strategies
      2. 5.2.2 Kuehne + Nagel (CH)
        1. 5.2.2.1 Financial Overview
        2. 5.2.2.2 Products Offered
        3. 5.2.2.3 Key Developments
        4. 5.2.2.4 SWOT Analysis
        5. 5.2.2.5 Key Strategies
      3. 5.2.3 DB Schenker (DE)
        1. 5.2.3.1 Financial Overview
        2. 5.2.3.2 Products Offered
        3. 5.2.3.3 Key Developments
        4. 5.2.3.4 SWOT Analysis
        5. 5.2.3.5 Key Strategies
      4. 5.2.4 C.H. Robinson (US)
        1. 5.2.4.1 Financial Overview
        2. 5.2.4.2 Products Offered
        3. 5.2.4.3 Key Developments
        4. 5.2.4.4 SWOT Analysis
        5. 5.2.4.5 Key Strategies
      5. 5.2.5 Expeditors International (US)
        1. 5.2.5.1 Financial Overview
        2. 5.2.5.2 Products Offered
        3. 5.2.5.3 Key Developments
        4. 5.2.5.4 SWOT Analysis
        5. 5.2.5.5 Key Strategies
      6. 5.2.6 XPO Logistics (US)
        1. 5.2.6.1 Financial Overview
        2. 5.2.6.2 Products Offered
        3. 5.2.6.3 Key Developments
        4. 5.2.6.4 SWOT Analysis
        5. 5.2.6.5 Key Strategies
      7. 5.2.7 Panalpina (CH)
        1. 5.2.7.1 Financial Overview
        2. 5.2.7.2 Products Offered
        3. 5.2.7.3 Key Developments
        4. 5.2.7.4 SWOT Analysis
        5. 5.2.7.5 Key Strategies
      8. 5.2.8 Geodis (FR)
        1. 5.2.8.1 Financial Overview
        2. 5.2.8.2 Products Offered
        3. 5.2.8.3 Key Developments
        4. 5.2.8.4 SWOT Analysis
        5. 5.2.8.5 Key Strategies
      9. 5.2.9 Sinotrans (CN)
        1. 5.2.9.1 Financial Overview
        2. 5.2.9.2 Products Offered
        3. 5.2.9.3 Key Developments
        4. 5.2.9.4 SWOT Analysis
        5. 5.2.9.5 Key Strategies
      10. 5.2.10 Nippon Express (JP)
        1. 5.2.10.1 Financial Overview
        2. 5.2.10.2 Products Offered
        3. 5.2.10.3 Key Developments
        4. 5.2.10.4 SWOT Analysis
        5. 5.2.10.5 Key Strategies
    3. 5.3 Appendix
      1. 5.3.1 References
      2. 5.3.2 Related Reports
  6. 6 LIST OF FIGURES
    1. 6.1 MARKET SYNOPSIS
    2. 6.2 NORTH AMERICA MARKET ANALYSIS
    3. 6.3 US MARKET ANALYSIS BY SERVICE TYPE
    4. 6.4 US MARKET ANALYSIS BY END USER
    5. 6.5 US MARKET ANALYSIS BY SHIPMENT TYPE
    6. 6.6 US MARKET ANALYSIS BY TRANSPORTATION MODE
    7. 6.7 US MARKET ANALYSIS BY CARGO TYPE
    8. 6.8 CANADA MARKET ANALYSIS BY SERVICE TYPE
    9. 6.9 CANADA MARKET ANALYSIS BY END USER
    10. 6.10 CANADA MARKET ANALYSIS BY SHIPMENT TYPE
    11. 6.11 CANADA MARKET ANALYSIS BY TRANSPORTATION MODE
    12. 6.12 CANADA MARKET ANALYSIS BY CARGO TYPE
    13. 6.13 EUROPE MARKET ANALYSIS
    14. 6.14 GERMANY MARKET ANALYSIS BY SERVICE TYPE
    15. 6.15 GERMANY MARKET ANALYSIS BY END USER
    16. 6.16 GERMANY MARKET ANALYSIS BY SHIPMENT TYPE
    17. 6.17 GERMANY MARKET ANALYSIS BY TRANSPORTATION MODE
    18. 6.18 GERMANY MARKET ANALYSIS BY CARGO TYPE
    19. 6.19 UK MARKET ANALYSIS BY SERVICE TYPE
    20. 6.20 UK MARKET ANALYSIS BY END USER
    21. 6.21 UK MARKET ANALYSIS BY SHIPMENT TYPE
    22. 6.22 UK MARKET ANALYSIS BY TRANSPORTATION MODE
    23. 6.23 UK MARKET ANALYSIS BY CARGO TYPE
    24. 6.24 FRANCE MARKET ANALYSIS BY SERVICE TYPE
    25. 6.25 FRANCE MARKET ANALYSIS BY END USER
    26. 6.26 FRANCE MARKET ANALYSIS BY SHIPMENT TYPE
    27. 6.27 FRANCE MARKET ANALYSIS BY TRANSPORTATION MODE
    28. 6.28 FRANCE MARKET ANALYSIS BY CARGO TYPE
    29. 6.29 RUSSIA MARKET ANALYSIS BY SERVICE TYPE
    30. 6.30 RUSSIA MARKET ANALYSIS BY END USER
    31. 6.31 RUSSIA MARKET ANALYSIS BY SHIPMENT TYPE
    32. 6.32 RUSSIA MARKET ANALYSIS BY TRANSPORTATION MODE
    33. 6.33 RUSSIA MARKET ANALYSIS BY CARGO TYPE
    34. 6.34 ITALY MARKET ANALYSIS BY SERVICE TYPE
    35. 6.35 ITALY MARKET ANALYSIS BY END USER
    36. 6.36 ITALY MARKET ANALYSIS BY SHIPMENT TYPE
    37. 6.37 ITALY MARKET ANALYSIS BY TRANSPORTATION MODE
    38. 6.38 ITALY MARKET ANALYSIS BY CARGO TYPE
    39. 6.39 SPAIN MARKET ANALYSIS BY SERVICE TYPE
    40. 6.40 SPAIN MARKET ANALYSIS BY END USER
    41. 6.41 SPAIN MARKET ANALYSIS BY SHIPMENT TYPE
    42. 6.42 SPAIN MARKET ANALYSIS BY TRANSPORTATION MODE
    43. 6.43 SPAIN MARKET ANALYSIS BY CARGO TYPE
    44. 6.44 REST OF EUROPE MARKET ANALYSIS BY SERVICE TYPE
    45. 6.45 REST OF EUROPE MARKET ANALYSIS BY END USER
    46. 6.46 REST OF EUROPE MARKET ANALYSIS BY SHIPMENT TYPE
    47. 6.47 REST OF EUROPE MARKET ANALYSIS BY TRANSPORTATION MODE
    48. 6.48 REST OF EUROPE MARKET ANALYSIS BY CARGO TYPE
    49. 6.49 APAC MARKET ANALYSIS
    50. 6.50 CHINA MARKET ANALYSIS BY SERVICE TYPE
    51. 6.51 CHINA MARKET ANALYSIS BY END USER
    52. 6.52 CHINA MARKET ANALYSIS BY SHIPMENT TYPE
    53. 6.53 CHINA MARKET ANALYSIS BY TRANSPORTATION MODE
    54. 6.54 CHINA MARKET ANALYSIS BY CARGO TYPE
    55. 6.55 INDIA MARKET ANALYSIS BY SERVICE TYPE
    56. 6.56 INDIA MARKET ANALYSIS BY END USER
    57. 6.57 INDIA MARKET ANALYSIS BY SHIPMENT TYPE
    58. 6.58 INDIA MARKET ANALYSIS BY TRANSPORTATION MODE
    59. 6.59 INDIA MARKET ANALYSIS BY CARGO TYPE
    60. 6.60 JAPAN MARKET ANALYSIS BY SERVICE TYPE
    61. 6.61 JAPAN MARKET ANALYSIS BY END USER
    62. 6.62 JAPAN MARKET ANALYSIS BY SHIPMENT TYPE
    63. 6.63 JAPAN MARKET ANALYSIS BY TRANSPORTATION MODE
    64. 6.64 JAPAN MARKET ANALYSIS BY CARGO TYPE
    65. 6.65 SOUTH KOREA MARKET ANALYSIS BY SERVICE TYPE
    66. 6.66 SOUTH KOREA MARKET ANALYSIS BY END USER
    67. 6.67 SOUTH KOREA MARKET ANALYSIS BY SHIPMENT TYPE
    68. 6.68 SOUTH KOREA MARKET ANALYSIS BY TRANSPORTATION MODE
    69. 6.69 SOUTH KOREA MARKET ANALYSIS BY CARGO TYPE
    70. 6.70 MALAYSIA MARKET ANALYSIS BY SERVICE TYPE
    71. 6.71 MALAYSIA MARKET ANALYSIS BY END USER
    72. 6.72 MALAYSIA MARKET ANALYSIS BY SHIPMENT TYPE
    73. 6.73 MALAYSIA MARKET ANALYSIS BY TRANSPORTATION MODE
    74. 6.74 MALAYSIA MARKET ANALYSIS BY CARGO TYPE
    75. 6.75 THAILAND MARKET ANALYSIS BY SERVICE TYPE
    76. 6.76 THAILAND MARKET ANALYSIS BY END USER
    77. 6.77 THAILAND MARKET ANALYSIS BY SHIPMENT TYPE
    78. 6.78 THAILAND MARKET ANALYSIS BY TRANSPORTATION MODE
    79. 6.79 THAILAND MARKET ANALYSIS BY CARGO TYPE
    80. 6.80 INDONESIA MARKET ANALYSIS BY SERVICE TYPE
    81. 6.81 INDONESIA MARKET ANALYSIS BY END USER
    82. 6.82 INDONESIA MARKET ANALYSIS BY SHIPMENT TYPE
    83. 6.83 INDONESIA MARKET ANALYSIS BY TRANSPORTATION MODE
    84. 6.84 INDONESIA MARKET ANALYSIS BY CARGO TYPE
    85. 6.85 REST OF APAC MARKET ANALYSIS BY SERVICE TYPE
    86. 6.86 REST OF APAC MARKET ANALYSIS BY END USER
    87. 6.87 REST OF APAC MARKET ANALYSIS BY SHIPMENT TYPE
    88. 6.88 REST OF APAC MARKET ANALYSIS BY TRANSPORTATION MODE
    89. 6.89 REST OF APAC MARKET ANALYSIS BY CARGO TYPE
    90. 6.90 SOUTH AMERICA MARKET ANALYSIS
    91. 6.91 BRAZIL MARKET ANALYSIS BY SERVICE TYPE
    92. 6.92 BRAZIL MARKET ANALYSIS BY END USER
    93. 6.93 BRAZIL MARKET ANALYSIS BY SHIPMENT TYPE
    94. 6.94 BRAZIL MARKET ANALYSIS BY TRANSPORTATION MODE
    95. 6.95 BRAZIL MARKET ANALYSIS BY CARGO TYPE
    96. 6.96 MEXICO MARKET ANALYSIS BY SERVICE TYPE
    97. 6.97 MEXICO MARKET ANALYSIS BY END USER
    98. 6.98 MEXICO MARKET ANALYSIS BY SHIPMENT TYPE
    99. 6.99 MEXICO MARKET ANALYSIS BY TRANSPORTATION MODE
    100. 6.100 MEXICO MARKET ANALYSIS BY CARGO TYPE
    101. 6.101 ARGENTINA MARKET ANALYSIS BY SERVICE TYPE
    102. 6.102 ARGENTINA MARKET ANALYSIS BY END USER
    103. 6.103 ARGENTINA MARKET ANALYSIS BY SHIPMENT TYPE
    104. 6.104 ARGENTINA MARKET ANALYSIS BY TRANSPORTATION MODE
    105. 6.105 ARGENTINA MARKET ANALYSIS BY CARGO TYPE
    106. 6.106 REST OF SOUTH AMERICA MARKET ANALYSIS BY SERVICE TYPE
    107. 6.107 REST OF SOUTH AMERICA MARKET ANALYSIS BY END USER
    108. 6.108 REST OF SOUTH AMERICA MARKET ANALYSIS BY SHIPMENT TYPE
    109. 6.109 REST OF SOUTH AMERICA MARKET ANALYSIS BY TRANSPORTATION MODE
    110. 6.110 REST OF SOUTH AMERICA MARKET ANALYSIS BY CARGO TYPE
    111. 6.111 MEA MARKET ANALYSIS
    112. 6.112 GCC COUNTRIES MARKET ANALYSIS BY SERVICE TYPE
    113. 6.113 GCC COUNTRIES MARKET ANALYSIS BY END USER
    114. 6.114 GCC COUNTRIES MARKET ANALYSIS BY SHIPMENT TYPE
    115. 6.115 GCC COUNTRIES MARKET ANALYSIS BY TRANSPORTATION MODE
    116. 6.116 GCC COUNTRIES MARKET ANALYSIS BY CARGO TYPE
    117. 6.117 SOUTH AFRICA MARKET ANALYSIS BY SERVICE TYPE
    118. 6.118 SOUTH AFRICA MARKET ANALYSIS BY END USER
    119. 6.119 SOUTH AFRICA MARKET ANALYSIS BY SHIPMENT TYPE
    120. 6.120 SOUTH AFRICA MARKET ANALYSIS BY TRANSPORTATION MODE
    121. 6.121 SOUTH AFRICA MARKET ANALYSIS BY CARGO TYPE
    122. 6.122 REST OF MEA MARKET ANALYSIS BY SERVICE TYPE
    123. 6.123 REST OF MEA MARKET ANALYSIS BY END USER
    124. 6.124 REST OF MEA MARKET ANALYSIS BY SHIPMENT TYPE
    125. 6.125 REST OF MEA MARKET ANALYSIS BY TRANSPORTATION MODE
    126. 6.126 REST OF MEA MARKET ANALYSIS BY CARGO TYPE
    127. 6.127 KEY BUYING CRITERIA OF FOOD, BEVERAGES & NUTRITION
    128. 6.128 RESEARCH PROCESS OF MRFR
    129. 6.129 DRO ANALYSIS OF FOOD, BEVERAGES & NUTRITION
    130. 6.130 DRIVERS IMPACT ANALYSIS: FOOD, BEVERAGES & NUTRITION
    131. 6.131 RESTRAINTS IMPACT ANALYSIS: FOOD, BEVERAGES & NUTRITION
    132. 6.132 SUPPLY / VALUE CHAIN: FOOD, BEVERAGES & NUTRITION
    133. 6.133 FOOD, BEVERAGES & NUTRITION, BY SERVICE TYPE, 2024 (% SHARE)
    134. 6.134 FOOD, BEVERAGES & NUTRITION, BY SERVICE TYPE, 2024 TO 2035 (USD Billion)
    135. 6.135 FOOD, BEVERAGES & NUTRITION, BY END USER, 2024 (% SHARE)
    136. 6.136 FOOD, BEVERAGES & NUTRITION, BY END USER, 2024 TO 2035 (USD Billion)
    137. 6.137 FOOD, BEVERAGES & NUTRITION, BY SHIPMENT TYPE, 2024 (% SHARE)
    138. 6.138 FOOD, BEVERAGES & NUTRITION, BY SHIPMENT TYPE, 2024 TO 2035 (USD Billion)
    139. 6.139 FOOD, BEVERAGES & NUTRITION, BY TRANSPORTATION MODE, 2024 (% SHARE)
    140. 6.140 FOOD, BEVERAGES & NUTRITION, BY TRANSPORTATION MODE, 2024 TO 2035 (USD Billion)
    141. 6.141 FOOD, BEVERAGES & NUTRITION, BY CARGO TYPE, 2024 (% SHARE)
    142. 6.142 FOOD, BEVERAGES & NUTRITION, BY CARGO TYPE, 2024 TO 2035 (USD Billion)
    143. 6.143 BENCHMARKING OF MAJOR COMPETITORS
  7. 7 LIST OF TABLES
    1. 7.1 LIST OF ASSUMPTIONS
  8. 7.1.1
    1. 7.2 North America MARKET SIZE ESTIMATES; FORECAST
      1. 7.2.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.2.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.2.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.2.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.2.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    2. 7.3 US MARKET SIZE ESTIMATES; FORECAST
      1. 7.3.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.3.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.3.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.3.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.3.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    3. 7.4 Canada MARKET SIZE ESTIMATES; FORECAST
      1. 7.4.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.4.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.4.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.4.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.4.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    4. 7.5 Europe MARKET SIZE ESTIMATES; FORECAST
      1. 7.5.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.5.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.5.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.5.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.5.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    5. 7.6 Germany MARKET SIZE ESTIMATES; FORECAST
      1. 7.6.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.6.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.6.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.6.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.6.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    6. 7.7 UK MARKET SIZE ESTIMATES; FORECAST
      1. 7.7.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.7.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.7.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.7.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.7.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    7. 7.8 France MARKET SIZE ESTIMATES; FORECAST
      1. 7.8.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.8.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.8.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.8.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.8.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    8. 7.9 Russia MARKET SIZE ESTIMATES; FORECAST
      1. 7.9.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.9.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.9.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.9.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.9.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    9. 7.10 Italy MARKET SIZE ESTIMATES; FORECAST
      1. 7.10.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.10.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.10.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.10.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.10.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    10. 7.11 Spain MARKET SIZE ESTIMATES; FORECAST
      1. 7.11.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.11.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.11.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.11.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.11.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    11. 7.12 Rest of Europe MARKET SIZE ESTIMATES; FORECAST
      1. 7.12.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.12.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.12.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.12.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.12.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    12. 7.13 APAC MARKET SIZE ESTIMATES; FORECAST
      1. 7.13.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.13.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.13.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.13.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.13.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    13. 7.14 China MARKET SIZE ESTIMATES; FORECAST
      1. 7.14.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.14.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.14.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.14.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.14.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    14. 7.15 India MARKET SIZE ESTIMATES; FORECAST
      1. 7.15.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.15.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.15.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.15.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.15.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    15. 7.16 Japan MARKET SIZE ESTIMATES; FORECAST
      1. 7.16.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.16.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.16.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.16.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.16.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    16. 7.17 South Korea MARKET SIZE ESTIMATES; FORECAST
      1. 7.17.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.17.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.17.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.17.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.17.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    17. 7.18 Malaysia MARKET SIZE ESTIMATES; FORECAST
      1. 7.18.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.18.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.18.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.18.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.18.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    18. 7.19 Thailand MARKET SIZE ESTIMATES; FORECAST
      1. 7.19.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.19.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.19.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.19.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.19.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    19. 7.20 Indonesia MARKET SIZE ESTIMATES; FORECAST
      1. 7.20.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.20.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.20.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.20.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.20.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    20. 7.21 Rest of APAC MARKET SIZE ESTIMATES; FORECAST
      1. 7.21.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.21.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.21.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.21.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.21.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    21. 7.22 South America MARKET SIZE ESTIMATES; FORECAST
      1. 7.22.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.22.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.22.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.22.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.22.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    22. 7.23 Brazil MARKET SIZE ESTIMATES; FORECAST
      1. 7.23.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.23.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.23.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.23.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.23.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    23. 7.24 Mexico MARKET SIZE ESTIMATES; FORECAST
      1. 7.24.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.24.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.24.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.24.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.24.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    24. 7.25 Argentina MARKET SIZE ESTIMATES; FORECAST
      1. 7.25.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.25.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.25.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.25.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.25.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    25. 7.26 Rest of South America MARKET SIZE ESTIMATES; FORECAST
      1. 7.26.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.26.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.26.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.26.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.26.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    26. 7.27 MEA MARKET SIZE ESTIMATES; FORECAST
      1. 7.27.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.27.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.27.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.27.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.27.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    27. 7.28 GCC Countries MARKET SIZE ESTIMATES; FORECAST
      1. 7.28.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.28.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.28.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.28.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.28.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    28. 7.29 South Africa MARKET SIZE ESTIMATES; FORECAST
      1. 7.29.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.29.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.29.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.29.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.29.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    29. 7.30 Rest of MEA MARKET SIZE ESTIMATES; FORECAST
      1. 7.30.1 BY SERVICE TYPE, 2025-2035 (USD Billion)
      2. 7.30.2 BY END USER, 2025-2035 (USD Billion)
      3. 7.30.3 BY SHIPMENT TYPE, 2025-2035 (USD Billion)
      4. 7.30.4 BY TRANSPORTATION MODE, 2025-2035 (USD Billion)
      5. 7.30.5 BY CARGO TYPE, 2025-2035 (USD Billion)
    30. 7.31 PRODUCT LAUNCH/PRODUCT DEVELOPMENT/APPROVAL
  9. 7.31.1
    1. 7.32 ACQUISITION/PARTNERSHIP
  10. 7.32.1

FAQs

What is the current valuation of the Freight Forwarding Services Market?

The Freight Forwarding Services Market was valued at 208.0 USD Billion in 2024.

What is the projected market valuation for 2035?

The market is projected to reach a valuation of 290.0 USD Billion by 2035.

What is the expected CAGR for the Freight Forwarding Services Market from 2025 to 2035?

The expected CAGR for the market during the forecast period 2025 - 2035 is 3.07%.

Which service type segment has the highest projected valuation?

The Ocean Freight segment is projected to reach between 70.0 and 100.0 USD Billion.

What are the key players in the Freight Forwarding Services Market?

Key players include DHL, Kuehne + Nagel, DB Schenker, and C.H. Robinson, among others.

How does the Manufacturing sector contribute to the market?

The Manufacturing sector is projected to contribute between 60.0 and 80.0 USD Billion.

What is the valuation range for the Air Freight segment?

The Air Freight segment is expected to range from 60.0 to 80.0 USD Billion.

What is the projected valuation for the Less than Container Load shipment type?

The Less than Container Load shipment type is projected to reach between 40.0 and 60.0 USD Billion.

Which transportation mode is expected to have the highest valuation?

The Road transportation mode is projected to reach between 60.0 and 80.0 USD Billion.

What is the expected valuation for Hazardous Cargo by 2035?

The Hazardous Cargo segment is projected to reach between 30.0 and 40.0 USD Billion by 2035.

Author
Author
Author Profile
Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author
Co-Author Profile
Garvit Vyas LinkedIn Vice President - Operations
Garvit Vyas is a Research Analyst with experience in working across multiple industry domains in the market research sector. Over the past four years, he has been actively involved in analyzing diverse markets, gathering industry insights, and contributing to the development of comprehensive research reports. His work includes studying market trends, evaluating competitive landscapes, and supporting data-driven business insights. In the early phase of his career, Garvit worked on cross-domain research projects, which helped him build a strong foundation in market analysis, data interpretation, and industry intelligence across various sectors. Later, he transitioned into the Quality Control (QC) function, where he focuses on reviewing and refining research reports and marketing collaterals to ensure accuracy, consistency, and high editorial standards. His responsibilities include validating research data, improving report structure, and maintaining the overall quality of published content. Garvit is committed to maintaining strong research integrity and delivering reliable insights that support informed business decision-making.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.