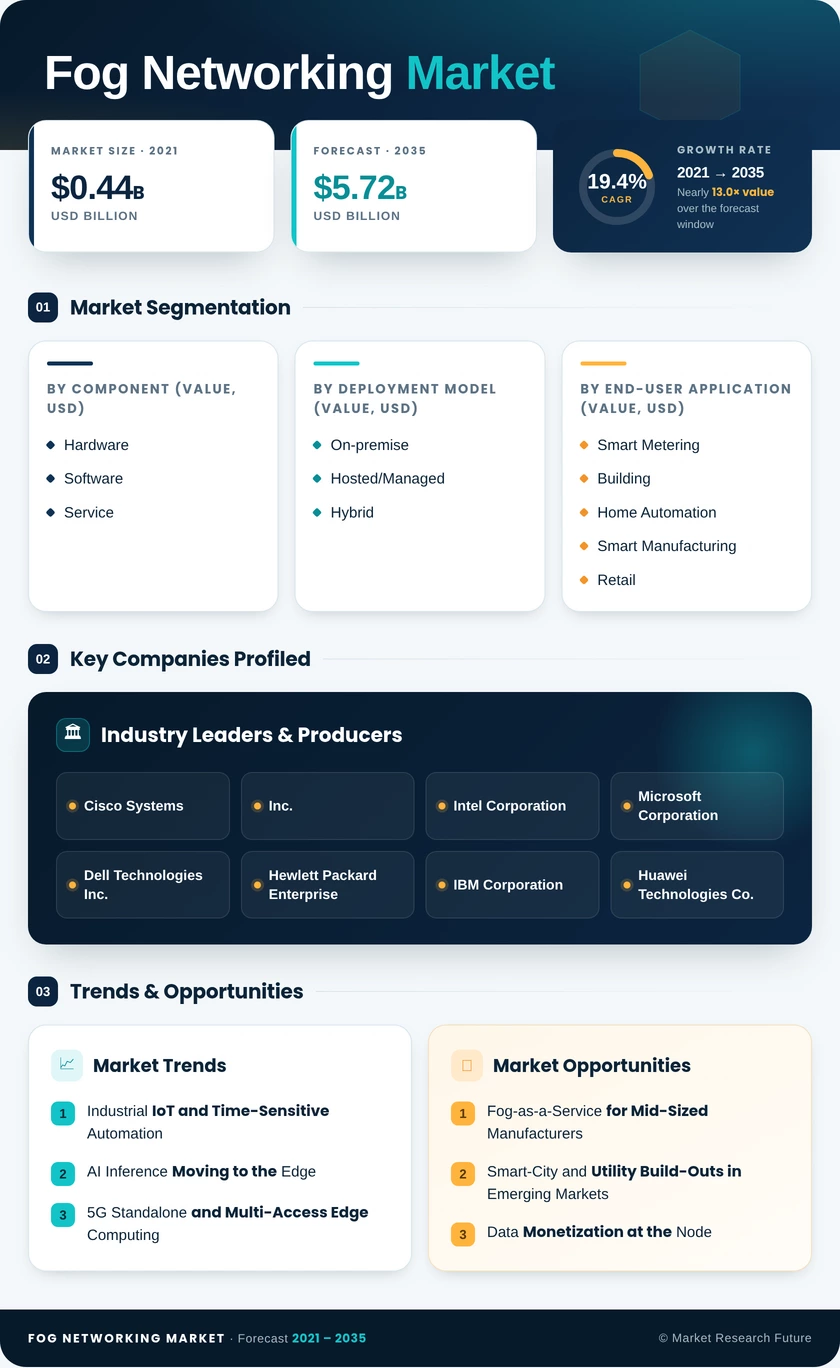
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Component (Value, USD) | Hardware, Software, Service | Hardware (61.2% share) | Software (24.3% CAGR) |
| By Deployment Model (Value, USD) | On-premise, Hosted/Managed, Hybrid | On-premise (42.3% share) | Hosted/Managed (23.6% CAGR) |
| By End-user Application (Value, USD) | Smart Metering, Building and Home Automation, Smart Manufacturing, Retail, Security and Emergencies, Healthcare, Business and Financial Services, Connected Vehicles | Smart Manufacturing (27.4% share) | Connected Vehicles (25.9% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America (38.6%) | Middle East & Africa (23.5% CAGR) |
Market Segmentation Overview
By Component (Value, USD)
| Sub-Segment | Key Trend |
|---|---|
| Hardware | Fog gateways and GPU-equipped micro-servers anchor first-wave installations. |
| Software | Container orchestration and zero-trust security shift to subscription licensing |
| Service | Integrators and managed providers fill the edge-skills gap. |
Hardware leads with a 61.2% share because no fog deployment starts without physical nodes, and fog gateways remain the first purchase for translating legacy field protocols. Software grows fastest at a 24.3% CAGR as installed fleets require remote orchestration, model updates, and security policy enforcement across hundreds of sites. Service demand rises alongside, since few operators can staff cutover and patching internally.
By Deployment Model (Value, USD)
| Sub-Segment | Key Trend |
|---|---|
| On-premise | Data-localization rules keep regulated workloads inside secured facilities |
| Hosted/Managed | Telecom operators and cloud providers sell fog-as-a-service bundles. |
| Hybrid | Local control combined with cloud-based fleet analytics |
On-premise leads with a 42.3% share because healthcare, defense, and utility buyers face strict residency and latency requirements under rules such as the EU Data Act. Hosted/Managed grows fastest at a 23.6% CAGR, as mid-sized manufacturers and retailers prefer monthly fees over capital purchases. Hybrid deployments bridge both, keeping control loops local while sending aggregated data to cloud analytics.
By End-user Application (Value, USD)
| Sub-Segment | Key Trend |
|---|---|
| Smart Metering | National rollouts embed analytics in data concentrators |
| Building and Home Automation | Occupancy-driven HVAC and lighting control |
| Smart Manufacturing | Machine vision and predictive maintenance on the plant floor |
| Retail | In-store video analytics and cashierless checkout |
| Security and Emergencies | Local video processing for public-safety response |
| Healthcare | Bedside gateways triage device telemetry |
| Business and Financial Services | Branch-level fraud screening and low-latency processing |
| Connected Vehicles | Roadside units fuse sensor feeds for V2X safety messages. |
Smart Manufacturing leads with a 27.4% share, since inspection lines and robotic cells generate data volumes too large and time-sensitive to send to the cloud. Connected Vehicles grow fastest at a 25.9% CAGR, driven by vehicle-road-cloud pilots in China and C-V2X corridor trials in North America. Smart Metering and Healthcare add steady demand as utilities and hospitals move first-pass analytics to local gateways.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA