Fluorspar Market (2026 - 2035)

ID: MRFR/CnM/4574-HCR 100 Pages Priya Nagrale Last Updated: September 18, 2026
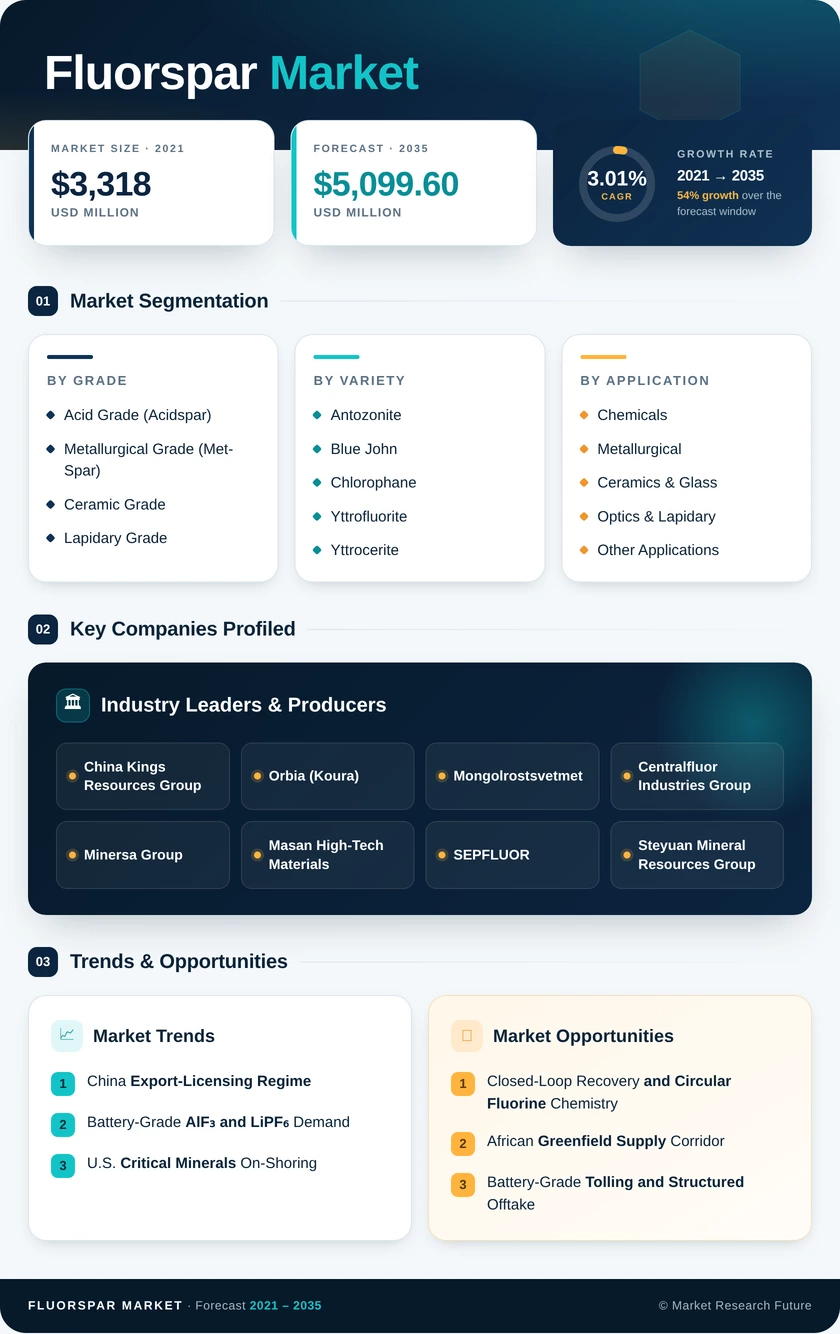
Fluorspar Market Research Report Information By Grade (Acid Grade (Acidspar), Metallurgical Grade (Met-Spar), Ceramic Grade, and Lapidary Grade), By Variety (Antozonite, Blue John, Chlorophane, Yttrofluorite, Yttrocerite, and Other Varieties), By Application (Chemicals, Metallurgical, Ceramics & Glass, Optics & Lapidary, and Other Applications), and By End-Use Industry (Chemical Processing, Iron & Steel, Aluminium Smelting, Glass & Ceramics, Electronics & Semiconductors, and Other End Uses) – Forecast Till 2035.
Fluorspar Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)3.01%
2025 Market SizeUSD 3,792.0 Million
2035 Market SizeUSD 5,099.6 Million
Key Players
China Kings Resources Group
Orbia
Mongolrostsvetmet
Centralfluor Industries Group
Minersa Group
Masan High-Tech Materials
Opportunities
  • Closed-Loop Recovery and Circular Fluorine Chemistry
  • African Greenfield Supply Corridor
  • Battery-Grade Tolling and Structured Offtake
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Takeaways | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Value (USD Million) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Market Dynamics — Drivers | |
    1. 4.1 China Export-Licensing Regime | |
    2. 4.2 Battery-Grade AlF₃ and LiPF₆ Demand | |
    3. 4.3 U.S. Critical Minerals On-Shoring | |
    4. 4.4 Gulf Aluminium Smelter Expansion | |
    5. 4.5 Electric-Arc Furnace Buildout | |
    6. 4.6 Kigali Refrigerant Transition | |
    7. 4.7 Semiconductor Etchant Demand | |
  5. 5 Market Dynamics — Restraints | |
    1. 5.1 Steel Sector Overcapacity | |
    2. 5.2 Permitting and Water-Discharge Limits | |
    3. 5.3 Synthetic and Recycled Fluoride Substitution | |
    4. 5.4 PFAS Regulatory Pressure Downstream | |
    5. 5.5 Resource Nationalism and Reserve Concentration | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Closed-Loop Recovery and Circular Fluorine Chemistry | |
    2. 6.2 African Greenfield Supply Corridor | |
    3. 6.3 Battery-Grade Tolling and Structured Offtake | |
    4. 6.4 Assay Provenance and Traceability Data Services | |
    5. 6.5 Specialty Optics and Collector-Grade Niche | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) | |
    1. 8.1 Electrification Supercycle and Fluorine Intensity | |
    2. 8.2 Supply-Chain De-Risking and Strategic Stockpiling | |
    3. 8.3 ESG, Tailings and Fluoride Discharge Disclosure | |
    4. 8.4 Ore Sorting, Sensor Systems and Process Digitalisation | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Grade | | |
      1. 9.1.1 Acid Grade (Acidspar) | | |
      2. 9.1.2 Metallurgical Grade (Met-Spar) | | |
      3. 9.1.3 Ceramic Grade | | |
      4. 9.1.4 Lapidary Grade | |
    2. 9.2 By Variety | | |
      1. 9.2.1 Antozonite | | |
      2. 9.2.2 Blue John | | |
      3. 9.2.3 Chlorophane | | |
      4. 9.2.4 Yttrofluorite | | |
      5. 9.2.5 Yttrocerite | | |
      6. 9.2.6 Other Varieties | |
    3. 9.3 By Application | | |
      1. 9.3.1 Chemicals | | |
      2. 9.3.2 Metallurgical | | |
      3. 9.3.3 Ceramics & Glass | | |
      4. 9.3.4 Optics & Lapidary | | |
      5. 9.3.5 Other Applications | |
    4. 9.4 By End-Use Industry | | |
      1. 9.4.1 Chemical Processing | | |
      2. 9.4.2 Iron & Steel | | |
      3. 9.4.3 Aluminium Smelting | | |
      4. 9.4.4 Glass & Ceramics | | |
      5. 9.4.5 Electronics & Semiconductors | | |
      6. 9.4.6 Other End Uses | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 China Kings Resources Group | | |
      2. 10.3.2 Orbia (Koura) | | |
      3. 10.3.3 Mongolrostsvetmet | | |
      4. 10.3.4 Centralfluor Industries Group | | |
      5. 10.3.5 Minersa Group | | |
      6. 10.3.6 Masan High-Tech Materials | | |
      7. 10.3.7 SEPFLUOR | | |
      8. 10.3.8 Steyuan Mineral Resources Group | | |
      9. 10.3.9 Canada Fluorspar Inc. | | |
      10. 10.3.10 British Fluorspar | | |
      11. 10.3.11 MongolCzech Metal | | |
      12. 10.3.12 Ares Strategic Mining | |
  11. 11 Recent Developments & News | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Valuation Currency & Conversion Basis | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | | LIST OF FIGURES

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By GradeAcid Grade (Acidspar); Metallurgical Grade (Met-Spar); Ceramic Grade; Lapidary GradeAcid Grade (Acidspar)Lapidary Grade
By VarietyAntozonite; Blue John; Chlorophane; Yttrofluorite; Yttrocerite; Other VarietiesAntozoniteYttrocerite
By ApplicationChemicals; Metallurgical; Ceramics & Glass; Optics & Lapidary; Other ApplicationsChemicalsMetallurgical
By End-Use IndustryChemical Processing; Iron & Steel; Aluminium Smelting; Glass & Ceramics; Electronics & Semiconductors; Other End UsesChemical ProcessingElectronics & Semiconductors
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Grade

Sub-SegmentKey Trend
Acid Grade (Acidspar)Specification tightening toward sub-3 ppm arsenic for electrochemical applications
Metallurgical Grade (Met-Spar)Declining flux intensity per tonne of liquid steel as slag practice improves
Ceramic GradeStable demand from enamel and opal glass with limited price elasticity
Lapidary GradeRising collector and specialty-optics procurement lifting per-kilogram realisation


Grade segmentation is the most commercially consequential split in this study because it maps directly onto realised pricing. Acidspar's premium over flux material has widened since 2023 as battery and semiconductor buyers competed for a narrow pool of qualified mines, and that spread is expected to persist through 2035.

By Variety

Sub-SegmentKey Trend
AntozonitePreferred beneficiation feed for chemical conversion routes
Blue JohnSustained decorative and optical demand at high per-unit realisation
ChlorophaneResearch and thermoluminescent applications expanding slowly
YttrofluoriteInterest tied to rare-earth co-recovery economics
YttroceriteNiche optics and laboratory-grade procurement growing steadily
Other VarietiesGeneral industrial conversion feedstock


Varietal composition governs impurity profile and therefore downstream suitability, which is why buyers increasingly specify origin as well as assay. Rare-earth-bearing varieties attract separate attention where co-recovery flowsheets can be justified against additional processing capital.

By Application

Sub-SegmentKey Trend
ChemicalsElectrolyte salts and fourth-generation refrigerants adding specification-premium volume
MetallurgicalGulf and South Asian smelter additions offsetting steel-sector softness
Ceramics & GlassSteady baseload consumption with low sensitivity to cycle
Optics & LapidaryLithography and infrared window demand supporting premium pricing
Other ApplicationsCement, welding and treatment chemistry providing residual outlets


Application mix explains the divergence between tonnage growth and value growth across the forecast. Chemical conversion absorbs the great majority of premium-specification material, while metallurgical uses supply volume stability without contributing proportionally to margin.

By End-Use Industry

Sub-SegmentKey Trend
Chemical ProcessingSimultaneous exposure to refrigerant, polymer and battery salt demand
Iron & SteelSlow share erosion on improving slag efficiency and overcapacity
Aluminium SmeltingContracted offtake growth tracking Gulf and Indian capacity additions
Glass & CeramicsIncremental growth from container and opacified enamel output
Electronics & SemiconductorsFastest-growing outlet with the highest qualification barrier
Other End UsesDiversified low-volume consumption across construction and treatment


End-use segmentation reveals where pricing power actually sits. Chemical processing and electronics buyers accept premium pricing because substitution is unavailable at their specification; steel and construction outlets remain price-takers and set the floor for commodity-grade material.

By Geography

Sub-SegmentKey Trend
North AmericaFederal credits and defence procurement accelerating domestic supply development
EuropeCritical Raw Materials Act benchmarks driving recycling and partnership sourcing
Asia-PacificExport licensing and electrolyte capacity reshaping regional trade flows
South AmericaBrownfield restart economics dominating over new discovery
Middle East & AfricaGulf smelter demand pulling African greenfield supply forward


Geographic structure remains unusually concentrated, with Asia-Pacific holding roughly seven in every ten tonnes consumed. Policy — export licensing in Asia, extraction benchmarks in Europe, production credits in North America — now shapes regional trajectories more decisively than resource endowment does.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.