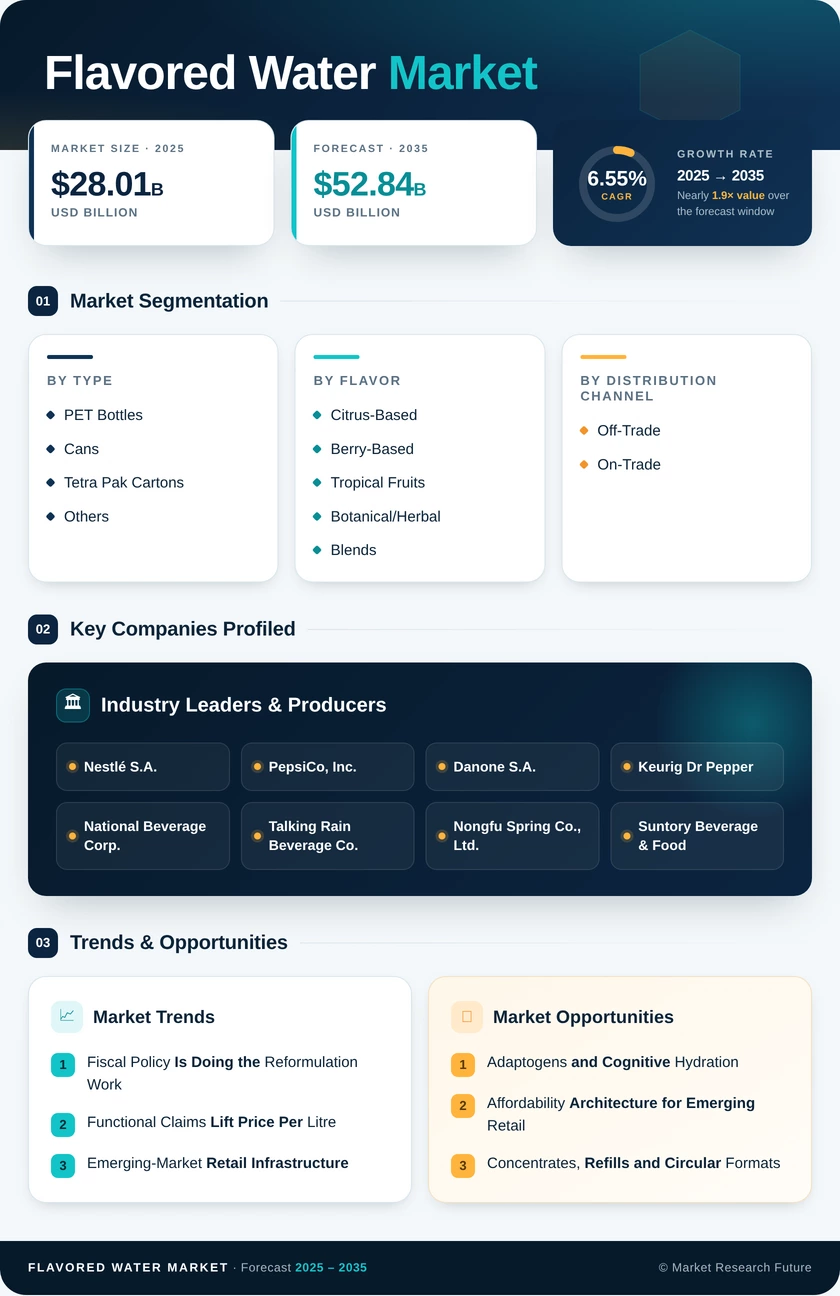
Flavored Water Market (2026 - 2035)

ID: MRFR/FnB/4025-CR 150 Pages Pradeep Nandi Last Updated: September 15, 2026
Flavored Water Market Size, Share, Industry Trend & Analysis Research Report Information By Product Type (Still, Sparkling), By Flavor (Citrus-Based, Berry-Based, Tropical Fruits, Botanical/Herbal, Blends), By Packaging Type (PET Bottles, Cans, Tetra Pak Cartons, Others), By Distribution Channel (On-Trade, Off-Trade), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) – Forecast Till 2035
Flavored Water Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.55%
2025 Market SizeUSD 28.01 Billion
2035 Market SizeUSD 52.84 Billion
Key Players
Nestlé S.A.
PepsiCo, Inc.
Danone S.A.
Keurig Dr Pepper
National Beverage Corp.
Talking Rain Beverage Co.
Opportunities
  • Adaptogens and Cognitive Hydration
  • Affordability Architecture for Emerging Retail
  • Concentrates, Refills and Circular Formats
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways |
    1. 2.1 Key Findings by Product Type |
    2. 2.2 Key Findings by Flavor, Packaging & Channel |
    3. 2.3 Key Findings by Geography
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2025) |
    2. 3.2 Current & Forecast Market Size (2026–2035) |
    3. 3.3 Market Size by Revenue (USD Billion) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Market Drivers Analysis |
    1. 4.1 Fiscal Policy and Sugar Levy Reformulation |
    2. 4.2 Functional Claims and Price-Per-Litre Uplift |
    3. 4.3 Emerging-Market Retail Infrastructure |
    4. 4.4 Packaging Economics and Circularity Rules
  5. 5 Market Restraints Analysis |
    1. 5.1 Sweetener Safety Scrutiny and Consumer Trust |
    2. 5.2 Resin and Aluminum Input Cost Volatility |
    3. 5.3 Private-Label Price Compression
  6. 6 Market Opportunity Analysis |
    1. 6.1 Adaptogens and Cognitive Hydration |
    2. 6.2 Affordability Architecture for Emerging Retail |
    3. 6.3 Concentrates, Refills and Circular Formats |
    4. 6.4 Retail Media and First-Party Data Monetization |
    5. 6.5 On-Trade Non-Alcoholic Occasions
  7. 7 Regional Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 AI-Native Flavor Development |
    2. 8.2 Subscription and Platform Economics |
    3. 8.3 Packaging Circularity Supercycle |
    4. 8.4 Water Stewardship Under Disclosure Pressure
  9. 9 Segmentation Analysis |
    1. 9.1 By Product Type | |
      1. 9.1.1 Still | |
      2. 9.1.2 Sparkling |
    2. 9.2 By Flavor | |
      1. 9.2.1 Citrus-Based | |
      2. 9.2.2 Berry-Based | |
      3. 9.2.3 Tropical Fruits | |
      4. 9.2.4 Botanical/Herbal | |
      5. 9.2.5 Blends |
    3. 9.3 By Packaging Type | |
      1. 9.3.1 PET Bottles | |
      2. 9.3.2 Cans | |
      3. 9.3.3 Tetra Pak Cartons | |
      4. 9.3.4 Others |
    4. 9.4 By Distribution Channel | |
      1. 9.4.1 On-Trade | |
      2. 9.4.2 Off-Trade
  10. 10 Competitive Landscape |
    1. 10.1 Market Share Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Nestlé S.A. | |
      2. 10.3.2 The Coca-Cola Company | |
      3. 10.3.3 PepsiCo, Inc. | |
      4. 10.3.4 Danone S.A. | |
      5. 10.3.5 Keurig Dr Pepper Inc. | |
      6. 10.3.6 National Beverage Corp. | |
      7. 10.3.7 Talking Rain Beverage Company | |
      8. 10.3.8 Nongfu Spring Co., Ltd. | |
      9. 10.3.9 Suntory Beverage & Food Ltd. | |
      10. 10.3.10 Primo Brands Corporation | |
      11. 10.3.11 Hint, Inc. | |
      12. 10.3.12 Spindrift Beverage Co.
  11. 11 Recent Developments & News
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Citations |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources and Citations
  14. 14 Frequently Asked Questions (FAQs)
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Flavored Water Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Global Market Size, by Product Type, 2021–2035 (USD Billion) |
  21. TABLE 6 Global Market Size, by Flavor, 2021–2035 (USD Billion) |
  22. TABLE 7 Global Market Size, by Packaging Type, 2021–2035 (USD Billion) |
  23. TABLE 8 Global Market Size, by Distribution Channel, 2021–2035 (USD Billion) |
  24. TABLE 9 Global Market Size, by Region, 2021–2035 (USD Billion) |
  25. TABLE 10 North America Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Europe Market Size, by Country, 2021–2035 (USD Billion) |
  27. TABLE 12 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) |
  28. TABLE 13 South America Market Size, by Country, 2021–2035 (USD Billion) |
  29. TABLE 14 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) |
  30. TABLE 15 North America Market Size, by Product Type, 2021–2035 (USD Billion) |
  31. TABLE 16 North America Market Size, by Packaging Type, 2021–2035 (USD Billion) |
  32. TABLE 17 Europe Market Size, by Flavor, 2021–2035 (USD Billion) |
  33. TABLE 18 Europe Market Size, by Distribution Channel, 2021–2035 (USD Billion) |
  34. TABLE 19 Asia-Pacific Market Size, by Product Type, 2021–2035 (USD Billion) |
  35. TABLE 20 Asia-Pacific Market Size, by Packaging Type, 2021–2035 (USD Billion) |
  36. TABLE 21 South America Market Size, by Flavor, 2021–2035 (USD Billion) |
  37. TABLE 22 Middle East & Africa Market Size, by Distribution Channel, 2021–2035 (USD Billion) |
  38. TABLE 23 Competitive Benchmarking Matrix, 2026 |
  39. TABLE 24 Company Profiles – Key Players |
  40. TABLE 25 Recent Developments & Strategic Announcements, 2023–2025 |
  41. TABLE 26 Report Scope & Methodology Summary |
  42. TABLE 27 Detailed Sources and Citations Index
  43. 16 LIST OF FIGURES |
  44. FIGURE 1 Market Dynamics — Drivers, Restraints and Opportunities Framework |
  45. FIGURE 2 Industry Value Chain Analysis — Ingredients to Retail Shelf |
  46. FIGURE 3 Porter's Five Forces Analysis |
  47. FIGURE 4 Global Market Size Trend and Forecast, 2021–2035 (USD Billion) |
  48. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 |
  49. FIGURE 6 Revenue Share by Product Type, 2025 vs 2035 |
  50. FIGURE 7 Revenue Share by Flavor, 2025 |
  51. FIGURE 8 Revenue Share by Packaging Type, 2025 vs 2035 |
  52. FIGURE 9 Revenue Share by Distribution Channel, 2025 |
  53. FIGURE 10 Regional Revenue Share Distribution, 2025 |
  54. FIGURE 11 Regional CAGR Comparison, 2026–2035 |
  55. FIGURE 12 Country-Level Growth Heat Map |
  56. FIGURE 13 Competitive Landscape Positioning Matrix |
  57. FIGURE 14 Top-5 Player Revenue Share Concentration, 2026 |
  58. FIGURE 15 Packaging Circularity and Recycled Content Outlook, 2026–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
Product TypeStill, SparklingSparklingSparkling
FlavorCitrus-Based, Berry-Based, Tropical Fruits, Botanical/Herbal, BlendsCitrus-BasedBotanical/Herbal
Packaging TypePET Bottles, Cans, Tetra Pak Cartons, OthersPET BottlesCans
Distribution ChannelOn-Trade, Off-TradeOff-TradeOn-Trade
GeographyNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Product Type

Sub-SegmentKey Trend
StillMultipack family formats and small-format affordability SKUs in emerging retail
SparklingAdult soda replacement, premium cold-vault placement and caffeinated line extensions


Carbonation carries the category's premium economics, while still formats absorb volume growth where price sensitivity governs purchase. Bottlers increasingly run both from shared filling infrastructure to hedge demand mix shifts.

By Flavor

Sub-SegmentKey Trend
Citrus-BasedDefault carrier for reformulated zero-sugar bases due to bitterness masking
Berry-BasedAntioxidant positioning and strong colour-led shelf standout
Tropical FruitsSeasonal activation and younger demographic recruitment
Botanical/HerbalAlcohol moderation occasions and adult sophistication cues
BlendsLimited-edition rotation used to defend shelf facings


Flavor architecture is now a portfolio decision rather than a single-SKU bet. Leading brands anchor volume on citrus and berry, then rotate tropical and blend variants to sustain novelty without cannibalizing core listings.

By Packaging Type

Sub-SegmentKey Trend
PET BottlesRecycled-content mandates and tethered-closure redesign across Europe
CansRecyclability credentials, lighter transport weight and challenger-brand launches
Tetra Pak CartonsAmbient distribution advantage in cold-chain-limited geographies
OthersGlass in hospitality channels; pouches in children's hydration


Packaging strategy has become a compliance and cost discipline as much as a branding one. Multi-year rPET and aluminum sheet contracts increasingly separate scaled bottlers from spot-exposed challengers.

By Distribution Channel

Sub-SegmentKey Trend
On-TradeRestaurant, bar and hotel non-alcoholic programs expanding beyond soda guns
Off-TradeDiscounter private label, convenience impulse chilled and e-commerce subscription


Off-trade sets the volume baseline through grocery and convenience breadth. On-trade contributes disproportionate margin and brand-building value, particularly where premium botanical variants serve moderation-driven occasions.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.