Segmentation Quick Reference
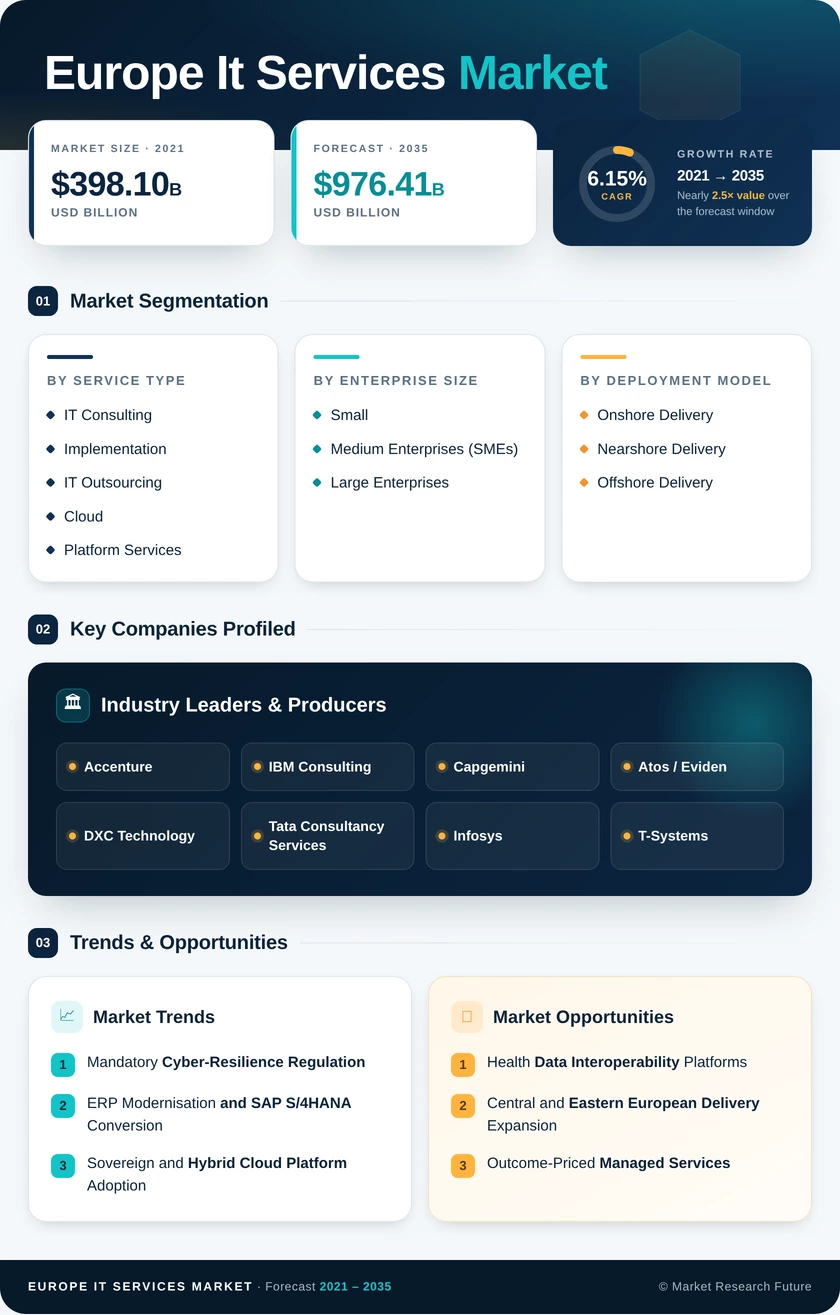
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Service Type | IT Consulting and Implementation; IT Outsourcing; Cloud and Platform Services; Managed Security Services; Business Process Services | Cloud and Platform Services (31.2% share, 2025) | Managed Security Services (7.23% CAGR) |
| By Enterprise Size | Small and Medium Enterprises (SMEs); Large Enterprises | Large Enterprises (USD 285.30 Billion, 2025) | Small and Medium Enterprises (SMEs) (7.49% CAGR) |
| By Deployment Model | Onshore Delivery; Nearshore Delivery; Offshore Delivery | Nearshore Delivery (42.6% share, 2025) | Offshore Delivery (7.55% CAGR) |
| By End-User Vertical | BFSI; Manufacturing; Government; Healthcare; Retail; Telecom; Other Verticals | BFSI (22.4% share, 2025) | Healthcare (7.40% CAGR) |
| By Country | United Kingdom; Germany; France; Italy; Spain; Rest of Europe | United Kingdom (24.6% share, 2025) | Spain (6.62% CAGR) |
Market Segmentation Overview
By Service Type
| Sub-Segment | Key Trend |
| IT Consulting and Implementation | SAP conversion deadlines and ESG platform builds sustain advisory pipelines |
| IT Outsourcing | Automation reshapes pricing away from headcount-based models |
| Cloud and Platform Services | Sovereign region migration extends beyond simple lift-and-shift |
| Managed Security Services | Regulatory monitoring duties convert pilots into permanent opex |
| Business Process Services | Document-extraction models absorb transactional workload |
Cloud and Platform Services holds the largest position because European enterprises are still midway through migrating estates into jurisdictionally partitioned regions, work that generates both project and run-state revenue. Managed Security Services grows fastest since NIS2 and DORA made continuous threat monitoring a legal duty rather than a budget line subject to annual review. IT Consulting and Implementation remains tightly coupled to the SAP maintenance horizon, while IT Outsourcing and Business Process Services increasingly compete for the same automated back-office scope.
By Enterprise Size
| Sub-Segment | Key Trend |
| Small and Medium Enterprises (SMEs) | Voucher schemes fund software but leave integration work chargeable |
| Large Enterprises | Multi-country agreements renew with productivity-linked pricing |
Large Enterprises supply the bulk of revenue through multi-year global support agreements that renew on predictable cycles, but Small and Medium Enterprises (SMEs) expand considerably faster from a narrower base. National subsidy programmes in Germany and Spain cover licensing costs while leaving data migration, integration and cyber-posture assessment unfunded — chargeable work that has finally made the smaller-firm tier commercially attractive to established providers offering modular catalogues.
By Deployment Model
| Sub-Segment | Key Trend |
| Onshore Delivery | Regulated and classified workloads cannot legally relocate |
| Nearshore Delivery | GDPR-native Central European centres bridge cost and compliance |
| Offshore Delivery | EU-resident data enclaves preserve arbitrage within legal limits |
Nearshore Delivery leads because Polish and Romanian centres sit inside EU jurisdiction while pricing far below Western European alternatives, resolving the tension regulated buyers face. Offshore Delivery grows fastest as providers establish EU-resident data enclaves and collaboration tooling erodes time-zone friction on commodity maintenance. Onshore Delivery holds a durable floor: transfer-impact rules ensure a category of sensitive workloads that no amount of cost pressure can move offshore.
By End-User Vertical
| Sub-Segment | Key Trend |
| BFSI | Third-party ICT risk registers drive contract remediation programmes |
| Manufacturing | Data-space onboarding creates repeatable supplier integration work |
| Government | Recovery fund deadlines compress tender and delivery timelines |
| Healthcare | Cross-border record interoperability forces deferred system upgrades |
| Retail | Unified commerce platforms replace fragmented channel systems |
| Telecom | Network function virtualisation sustains engineering services demand |
| Other Verticals | Energy and logistics modernisation broadens the addressable base |
BFSI dominates because financial supervisors imposed operational resilience obligations earlier and more prescriptively than any other sector regulator, generating audit-driven remediation across every European banking group. Healthcare grows fastest as interoperability mandates compel hospital estates to replace clinical systems that had been deferred through a decade of budget constraint. Manufacturing spending remains rate-sensitive and Government spending procurement-constrained, so neither converts strong policy support into equally strong near-term revenue.
By Country
| Sub-Segment | Key Trend |
| United Kingdom | Financial concentration sustains resilience and reporting demand |
| Germany | Manufacturing ERP conversion volume anchors integrator pipelines |
| France | Qualification schemes make sovereign hosting a tender prerequisite |
| Italy | Recovery plan funding drives public administration modernisation |
| Spain | Voucher programmes accelerate smaller-firm technology adoption |
| Rest of Europe | Central European delivery capacity and Nordic platform engineering |
The United Kingdom leads despite sitting outside the EU regulatory perimeter, because London's density of financial institutions generates resilience, reporting and cloud migration demand that no other national market matches. Germany follows on sheer ERP conversion volume across its manufacturing base. Spain grows fastest, propelled by voucher-funded adoption among smaller firms — growth that depends on public disbursement continuing rather than on organic private capex.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA