Elderly Care Services Market Size, Share - Trends and Forecast (2026 - 2035)

Elderly Care Services Market Size, Share and Research Report By Service Type (Home Care, Adult Care, Institutional Care), By Sector (Public, Private) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/PS/64765-HCR 200 Pages Rahul Gotadki, Garvit Vyas Last Updated: September 30, 2026
Elderly Care Services Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.4%
2025 Market SizeUSD 1.280 Billion
2035 Market SizeUSD 2.614 Billion
Key Players
Home Instead, Inc.
Brookdale Senior Living Inc.
Sunrise Senior Living
Amedisys, Inc.
Clariane SE
emeis
Opportunities
  • Formal Care Capacity in Emerging Markets
  • Data-Driven Platforms and Subscription Care Models
  • Specialized Dementia and Memory Care

Elderly Care Services Market Summary

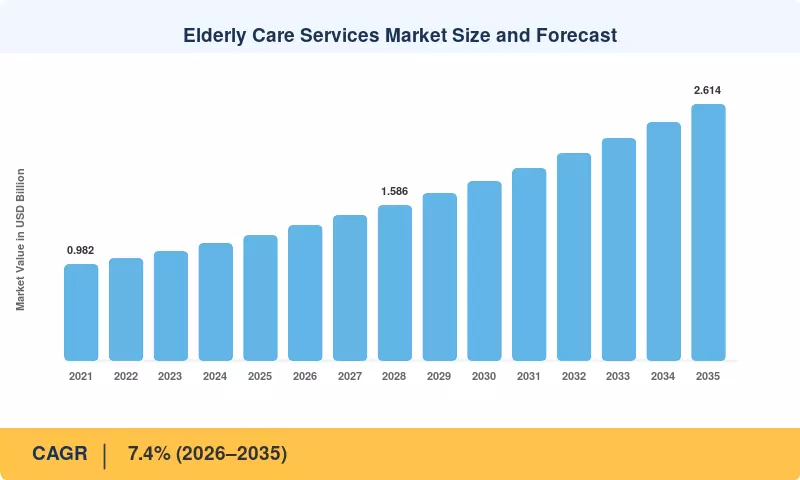
The Elderly Care Services Market was valued at USD 1.28 billion in 2025 and is projected to grow from USD 1.375 billion in 2026 to USD 2.61 billion by 2035, a CAGR of 7.4% over the forecast period. Two policy catalysts anchor this trajectory. In April 2024, the U.S. Centers for Medicare & Medicaid Services (CMS) finalized its Medicaid Access Rule, which requires 80% of home and community-based services (HCBS) payments to flow to direct care worker compensation [5]. China's January 2024 State Council guideline on the silver economy added incentives for community eldercare capacity and smart care products [12].

Care delivery itself is being rebuilt. Paper-based care plans, fixed-schedule visits, and facility-centric models are giving way to electronic visit verification, remote vital-sign monitoring, fall-detection sensors, and telehealth check-ins that let providers stretch scarce staff across more clients. Public money is funding the shift: the American Rescue Plan Act channelled roughly USD 12.7 billion in enhanced federal Medicaid matching funds into HCBS expansion, much of it directed at workforce and technology upgrades [23].

North America holds the largest position with a 38.5% share in 2025, supported by Medicaid waiver programs and a deep private-pay senior housing base. Asia-Pacific is the fastest-growing region at a 9.1% CAGR as China, Japan, and India scale formal care capacity, while Europe ranks second with a 27.0% share, backed by statutory long-term care insurance in Germany and national social care funding in the United Kingdom [15][16]. Over the next decade, the Elderly Care Services Market will reward providers that combine home-based delivery with clinical capability and data-driven care coordination.

Key Report Takeaways

• By Service Type

  • Home Care leads the Elderly Care Services Market with a 46.5% share in 2025, reflecting a strong preference among seniors for receiving support at home.
  • Adult Care is the fastest-growing service type, expanding at an 8.6% CAGR through 2035 as adult day programs offer lower-cost daytime supervision.
  • Institutional Care generated USD 0.488 billion in 2025, anchored by nursing homes, assisted living, and hospice capacity.

• By Sector

  • The Private sector accounts for 63.5% of the Elderly Care Services Market, driven by private-pay senior housing and franchised home care networks.
  • The Public sector is forecast to grow at a 7.9% CAGR, supported by expanding long-term care insurance and Medicaid HCBS budgets.

• By Region

  • North America holds a 38.5% share, the largest of any region.
  • Asia-Pacific is the fastest-growing region, advancing at a 9.1% CAGR.
  • Europe accounts for a 27.0% share, supported by statutory care insurance systems.

Market Size and Forecast (2021–2035)

Market Research Future built the historical series from provider filings, public payer expenditure data from CMS, the OECD, and national health ministries, and primary interviews with care operators, then modelled the forecast against demographic projections from the United Nations and the World Health Organization [1][2][10]. The Elderly Care Services Market series below captures revenue from home, adult, and institutional care services across public and private sectors.
Elderly Care Services Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Accelerating growth of the older population ~+1.6% Global; strongest in Japan, Europe, China Long-term (≥4 yr)
Rising chronic disease burden ~+1.3% North America, Europe Medium-term (2–4 yr)
Shift toward home- and community-based care ~+1.2% North America, Europe Short-term (≤2 yr)
Public long-term care financing reforms ~+1.0% Europe, Asia-Pacific Medium-term (2–4 yr)
Digital health and remote monitoring integration ~+0.8% Global Medium-term (2–4 yr)
Growth of affluent, private-pay seniors ~+0.6% North America, Middle East and Africa Long-term (≥4 yr)


Accelerating Growth of the Older Population

According to WHO projections, one in six people globally will be 60 years of age or older by 2030, and by 2050, this group would number 2.1 billion, while the number of persons 80 years of age or older will triple to 426 million [1]. By the late 2070s, the number of persons over 65 will surpass that of those under 18, according to the UN World Population Prospects 2024 [2]. Longer lifespans increase the number of years that elders require assistance with everyday tasks, increasing demand at all service levels.


Rising Chronic Disease Burden

It is chronic sickness that turns aging into a need for compensated care. According to the National Council on Aging, 78.7% of persons 60 years of age and older manage two or more chronic conditions, and 94.9% of them have at least one [4]. The American Diabetes Association reports that 29.2% of Americans 65 and older have diabetes alone [3]. Families find it difficult to provide medication administration, wound care, and monitoring due to multimorbidity, which forces households to seek professional services.


Shift Toward Home- and Community-Based Care

An AARP survey found that 77% of adults aged 50 and older want to remain in their homes long term [9]. Payers support this on cost grounds: HCBS now represents more than half of Medicaid long-term services spending. The CMS Access Rule's requirement that 80% of HCBS payments fund direct care compensation, effective in 2030, is designed to stabilize the workforce that home-based delivery depends on [5].

Public Long-Term Care Financing Reforms

Germany's Care Support and Relief Act raised the statutory long-term care insurance contribution rate to 3.4% of gross wages from July 2023, expanding funding for home care allowances [15]. Japan's 2024 long-term care fee revision lifted provider reimbursement by 1.59%, with a focus on care worker pay [11]. In the United Kingdom, the 2022 Autumn Statement committed up to GBP 7.5 billion over two years for adult social care [16]. Each program widens the pool of funded service users.

Digital Health and Remote Monitoring Integration

Remote monitoring allows each caregiver to supervise more clients safely. China's January 2024 silver economy guideline explicitly promotes smart eldercare devices, including wearable monitors and home safety sensors [12]. In the United States, the CMS GUIDE Model, launched in July 2024, pays participating providers a monthly per-beneficiary amount for dementia care that includes a 24/7 support line and caregiver training [17]. Payment structures like these reward continuous, technology-enabled engagement over episodic visits.

Growth of Affluent, Private-Pay Seniors

Household wealth concentrated among older cohorts supports premium care. CareScout's 2024 Cost of Care Survey placed the U.S. national median for assisted living at about USD 70,800 per year and a private nursing home room at roughly USD 127,750, costs that a growing share of retirees cover through savings, home equity, and long-term care insurance [8]. Operators such as Brookdale have expanded tiered care-level pricing to capture this spending [22].

Restraints Impact Analysis

Restraint impact values represent estimated directional drag on the Elderly Care Services Market CAGR. They are not additive, and several restraints interact with the drivers described above.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Care workforce shortages and wage inflation ~-1.1% Global Long-term (≥4 yr)
High out-of-pocket care costs ~-0.8% North America, Europe Medium-term (2–4 yr)
Reimbursement pressure and public budget constraints ~-0.7% Europe, North America Medium-term (2–4 yr)
Regulatory compliance and staffing mandates ~-0.5% North America, Europe Short-term (≤2 yr)
Preference for informal family care in emerging markets ~-0.4% Asia-Pacific, Middle East and Africa, South America Long-term (≥4 yr)


Care Workforce Shortages and Wage Inflation

Through 2033, the U.S. Bureau of Labor Statistics estimates that there will be around 700,000 yearly positions for personal care and home health aides, the majority of which will be produced by turnover [7]. According to PHI, the median direct care wage is between USD 16 and USD 17 per hour, making it challenging for recruiters to compete with retail and logistics companies [24]. Agencies are forced to turn down referrals due to staffing shortages, which limits revenue even in situations where demand is present.


High Out-of-Pocket Care Costs

Families soon deplete their funds. A two-year care episode can cost more than USD 150,000 at CareScout's stated median of roughly USD 77,800 annually for a full-time home health aide [8]. Because only a tiny percentage of older persons are covered by private long-term care insurance, price sensitivity restricts the number of service hours households can purchase and pushes demand back toward unpaid family care.


Regulatory Compliance and Staffing Mandates

Compliance obligations remain volatile. The CMS minimum staffing rule, finalized in April 2024, required 3.48 total nurse staffing hours per resident day and carried an estimated cost of about USD 43 billion over ten years before a federal court vacated it in April 2025 [6]. In France, the 2022 care-home scandal at Orpea triggered stricter inspections and a restructuring completed under the emeis name [21].

Preference for Informal Family Care in Emerging Markets

Cultural norms slow formal adoption. The UNFPA India Ageing Report 2023 projects the share of Indians aged 60 and above rising from 10.5% in 2022 to 20.8% by 2050, yet most elderly support remains family-provided [14]. Strong filial expectations, thin insurance coverage, and stigma around residential facilities delay paid service uptake across South Asia, parts of the Middle East, and South America.

Elderly Care Services Market Opportunities

The following opportunities represent the most actionable white space in the Elderly Care Services Market for providers and investors.

Formal Care Capacity in Emerging Markets

India's older population is set to roughly double as a share of the total by 2050 [14], yet organized assisted living and home nursing supply remains concentrated in a handful of metros. GCC states are also building capacity, advancing at a 9.8% CAGR as governments fund home healthcare programs and invite private operators. Early entrants that pair caregiver training academies with branded service standards can win share before consolidation begins.

Data-Driven Platforms and Subscription Care Models

Remote monitoring generates continuous data on mobility, sleep, and medication adherence. Providers can package this into subscription tiers, sell risk insights to Medicare Advantage plans, or share in savings when hospitalizations fall. Membership-based aging in place solutions that bundle sensors, on-call nursing, and home modification create recurring revenue less exposed to occupancy cycles.

Specialized Dementia and Memory Care

The GUIDE Model created a new reimbursement path for comprehensive dementia care, including up to USD 2,500 per year in respite services for eligible beneficiaries [17]. Providers with memory care units, dementia-trained staff, and care navigation teams can position themselves for referral flows from health systems participating in the model.

Respite and Family Caregiver Programs

Unpaid family caregivers remain the backbone of elderly support, and their burnout drives premature facility admissions. Structured caregiver support services, including short respite stays, adult day programs, and skills training, let providers monetize demand that currently sits outside the paid economy. Adult Care's 8.6% CAGR shows that payers and families are already funding this bridge between home and institution.

Public-Private Partnerships in China

China had about 297 million residents aged 60 and older at the end of 2023, 21.1% of its population [13]. Local governments increasingly contract private operators to run community eldercare centers and embedded neighborhood care stations under the 2024 silver economy guideline [12]. Operators that can standardize protocols across hundreds of small sites stand to gain as China holds the largest share of Asia-Pacific demand.

Elderly Care Services Market Future Outlook

Four structural themes will define the Elderly Care Services Market through 2035.

AI-Enabled Monitoring and Predictive Care

Predictive analytics will move from pilot to standard practice. Models trained on sensor, medication, and visit data can flag fall risk, dehydration, or infection days before an emergency admission. With WHO projecting the 80-plus population to triple by 2050 [1], providers cannot scale headcount at the same pace, so software that prioritizes caregiver attention toward the highest-risk clients will become a core operating asset rather than an add-on.

Workforce Redesign and Care Worker Productivity

BLS projects employment of home health and personal care aides to grow 21% between 2023 and 2033, far faster than the all-occupation average [7]. Operators will respond with career ladders, micro-credentials, and automated scheduling that reduces unpaid travel time. Countries facing the steepest labor gaps, including Japan and Germany, will also widen immigration pathways for care workers, reshaping recruitment strategies across multinational providers.

Long-Term Care Financing Reform

Long-term care already absorbs about 1.8% of GDP across OECD countries, and that share is rising [10]. Governments will keep adjusting contribution rates, co-payments, and eligibility rules; Germany raised its care insurance rate again in January 2025 [15]. Expect more hybrid models that combine public entitlement with private top-up insurance, widening the paying customer base for premium services.

Age-Friendly Housing and Community-Integrated Care

Housing and care are converging. Senior housing owners such as Welltower increasingly partner with operators on profit-sharing structures tied to community performance [25], while municipalities design neighborhoods with embedded care stations. As the UN projects older adults to become a larger share of every region's population through the century [2], mixed-use developments that combine independent living, clinics, and day programs will gain ground.

Regional Market Share Analysis

Region Key Metric Primary Investment Themes
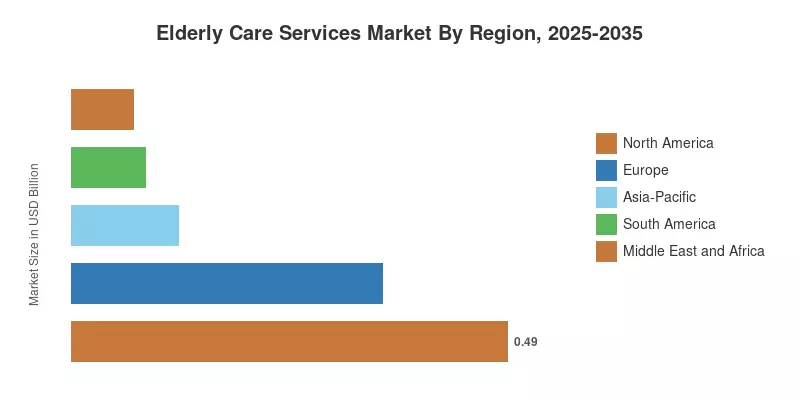
North America 38.5% share Medicaid HCBS expansion, private-pay senior housing, franchised home care
Europe 27.0% share Statutory care insurance, home care allowances, care-home consolidation
Asia-Pacific 9.1% CAGR Silver economy policy, long-term care insurance reform, community eldercare stations
South America USD 0.083 Billion Urban private residential care, social security pilot programs
Middle East and Africa 5.5% share GCC home healthcare programs, private sector entry
Total USD 1.280 Billion —

Regional demand in the Elderly Care Services Market tracks three variables: the pace of population ageing, the depth of public long-term care financing, and household ability to pay privately.


North America

Country Key Metric Key Driver
United States 81.0% of regional share Medicaid HCBS waivers, Medicare Advantage supplemental benefits
Canada 7.8% CAGR Provincial home care funding, long-term care bed expansion
Mexico USD 0.035 Billion Rising urban middle class, private residential care


Medicaid is the largest single payer for long-term services in the United States, and the Access Rule's wage pass-through requirement reshapes agency economics ahead of its 2030 effective date [5]. Medicare Advantage plans have offered in-home support as a supplemental benefit since 2019, opening a second funded channel. Canada's growth reflects provincial commitments such as Ontario's plan to add 30,000 long-term care beds by 2028, while Mexico's demand concentrates in private residential care serving urban families.

Europe

Country Key Metric Key Driver
Germany 24.5% of regional share Statutory long-term care insurance, home care allowances
United Kingdom 7.1% CAGR Adult social care funding, private-pay care homes
France USD 0.052 Billion APA dependency allowance, strengthened care-home oversight
Italy 12.0% of regional share Very old population structure, reform of elderly care law
Spain 6.8% CAGR Dependency Law funding, regional home care programs
Rest of Europe 22.0% of regional share Municipal home care models, capacity gaps in Central Europe


Germany's contribution-funded system gives it the deepest pool of financed demand in Europe, reinforced by the 2023 Care Support and Relief Act [15]. Italy passed Law 33/2023 to reorganize services for non-self-sufficient older adults, and the United Kingdom continues to channel ring-fenced grants into adult social care [16]. French operators Clariane and emeis are divesting non-core assets and investing in quality systems after years of regulatory scrutiny [20][21].

Asia-Pacific

Country Key Metric Key Driver
China 34.0% of regional share Silver economy guideline, community eldercare stations
Japan USD 0.078 Billion Long-term care insurance system, 2024 fee revision
India 11.6% CAGR Rapid ageing, urban nuclear families, organized home nursing
Australia 8.5% of regional share New Aged Care Act, Support at Home program
South Korea 9.4% CAGR Long-term care insurance expansion, super-aged demographics
Rest of Asia-Pacific 12.0% of regional share Emerging private operators, national eldercare plans


China combines the largest older population with explicit state backing for private eldercare investment [12][13]. Japan's mature insurance system funds a broad provider base, with reimbursement reset every three years [11]. South Korea crossed the threshold of a super-aged society in December 2024, and Australia's Aged Care Act, passed in November 2024, replaces legacy home care packages with the Support at Home program. India remains the region's fastest-developing formal market as organized home nursing scales [14].

South America

Country Key Metric Key Driver
Brazil 58.0% of regional share Largest older population in the region, private health plan coverage
Argentina 6.9% CAGR PAMI retiree health insurance, urban residential care
Rest of South America USD 0.019 Billion Early private residential care, public pilot programs


Brazil's 2022 census counted about 32 million residents aged 60 and older, and the Statute of Older Persons sets licensing requirements for long-stay institutions that favor professionalized operators. Argentina's PAMI, the national health insurer for retirees, finances home care and residential placements, although currency volatility constrains provider pricing. Elsewhere in the region, formal services remain concentrated in capital cities.

Middle East and Africa

Country Key Metric Key Driver
GCC 9.8% CAGR Government home healthcare programs, private sector participation
South Africa 24.0% of regional share Private retirement villages, Older Persons Act framework
Rest of Middle East and Africa USD 0.023 Billion Early-stage formal care, NGO-led services


GCC health strategies prioritize home healthcare and long-term care capacity to free acute hospital beds occupied by elderly patients, and public-private partnership frameworks are drawing international operators. South Africa's Older Persons Act of 2006 governs residential facilities and community-based care, with private retirement villages serving higher-income households. Across the rest of the region, faith-based and non-governmental organizations still deliver most formal services.

Elderly Care Services Market By Region, 2025-2035

Elderly Care Services Market Segmentation

By Service Type

The Elderly Care Services Market is segmented by service type into Home Care, Adult Care, and Institutional Care.

Segment Key Metric Primary Demand Driver
Home Care 46.5% share Senior preference for independent living, HCBS funding
Adult Care 8.6% CAGR Low-cost daytime supervision, family caregiver relief
Institutional Care USD 0.488 Billion High-acuity needs, dementia and end-of-life care


Home Care leads because it costs payers less than residential placement and matches what most seniors want. Adult Care grows fastest as day centers provide supervision and therapy while families work. Institutional Care covers Assisted Living Care, Independent Senior Living Care, Nursing Homes, Hospice and Palliative Care, Respite Care, Hospital Based Care, and Others; nursing homes and assisted living generate most of its revenue, while hospice demand rises with end-of-life care planning.

By Sector

By sector, the Elderly Care Services Market divides into Public and Private providers and funding channels.

Segment Key Metric Primary Demand Driver
Public 7.9% CAGR Long-term care insurance expansion, Medicaid HCBS budgets, government eldercare centers
Private 63.5% share Private-pay senior housing, franchised home care, premium services


Private operators dominate because assisted living, franchised in-home care, and premium memory care rely mainly on private payment and commercial insurance. Public delivery grows faster as governments in Japan, China, South Korea, and Germany widen entitlements and fund community care stations. Many public programs contract private providers, so growth in public funding also supports private operators through service contracts.

Competitive Benchmarking

The Elderly Care Services Market shows medium concentration. Market Research Future estimates a Herfindahl-Hirschman Index in the 700–900 range, with the five largest operators holding roughly 24–30% of revenue. Scale players lead in U.S. senior living and European nursing homes, while home care remains fragmented across thousands of local agencies and franchisees, keeping acquisition activity steady.

Company Est. Revenue Share Range Key Offerings for Elderly Care Services Market Strategic Positioning
Home Instead, Inc. ~6–9% Non-medical in-home care, companionship, dementia care Global franchise network in more than a dozen countries, backed by Honor's technology platform
Brookdale Senior Living Inc. ~5–8% Independent living, assisted living, memory care Largest U.S. senior living operator by community count
Sunrise Senior Living ~4–7% Assisted living, memory care, respite stays Hospitality-led premium communities in the U.S., Canada, and the U.K.
Amedisys, Inc. ~4–6% Home health, hospice, palliative care Clinical home care leader moving into UnitedHealth Group's Optum platform
Clariane SE ~3–6% Nursing homes, specialty care, home care Europe's largest care operator, refocusing through asset disposals
emeis ~3–5% Nursing homes, assisted living, home care Restructured group rebuilding quality and governance
Addus HomeCare Corporation ~3–5% Personal care, hospice, home health Medicaid-focused personal care consolidator
BrightSpring Health Services ~2–4% Home and community-based services, pharmacy Integrated pharmacy and provider services for complex populations
Bupa ~2–4% Aged care homes, home care Strong presence in Australia, the U.K., and Spain
Sompo Care Inc. ~2–4% Nursing homes, home-visit care Leading Japanese operator using a proprietary digital care platform
Right at Home, LLC ~1–3% Franchised in-home care Franchise expansion in the U.S. and international markets


Recent News & Developments

Recent activity in the Elderly Care Services Market centers on consolidation, reimbursement reform, and policy support for home-based care.

  • UnitedHealth Group and Amedisys (June 2023): Agreed to a roughly USD 3.3 billion acquisition, signaling payer-led integration of home health and hospice; the deal cleared antitrust review in 2025 with divestitures. [18]
  • State Council of China (January 2024): Issued its first national guideline on developing the silver economy, prioritizing community eldercare and smart care products. [12]
  • emeis (March 2024): Orpea completed its financial restructuring and rebranded as emeis, pledging stronger care quality controls. [21]
  • Japan Ministry of Health, Labour and Welfare (April 2024): Implemented a 1.59% long-term care fee increase aimed at raising care worker wages. [11]
  • CMS (April 2024): Finalized the Medicaid Access Rule requiring 80% of HCBS payments to support direct care worker compensation. [5]
  • CMS (April 2024): Finalized nursing home minimum staffing standards, later vacated by a federal court in April 2025. [6]
  • CMS Innovation Center (July 2024): Launched the eight-year GUIDE Model for comprehensive dementia care and caregiver respite. [17]
  • Addus HomeCare (December 2024): Completed its acquisition of Gentiva's personal care operations for about USD 350 million, expanding its Medicaid personal care footprint. [19]

Elderly Care Services Market Report Scope

Parameter Details
Market Scope Elderly Care Services Market revenue from Home Care, Adult Care, and Institutional Care delivered across Public and Private sectors in 5 regions and 17 countries
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 7.4% (2026–2035)
Market Size checkpoints USD 1.280 Billion (2025); USD 1.375 Billion (2026); USD 1.829 Billion (2030); USD 2.614 Billion (2035)
Fastest Growing Segments Adult Care (By Service Type); Public (By Sector); Asia-Pacific (By Region)
Companies Profiled Home Instead, Brookdale Senior Living, Sunrise Senior Living, Amedisys, Clariane, emeis, Addus HomeCare, BrightSpring Health Services, Bupa, Sompo Care, Right at Home
Valuation Currency USD Billion

FAQs

How does payer mix affect provider margins in the Elderly Care Services Market?
In the Elderly Care Services Market, private-pay clients usually deliver the highest margins, while Medicaid-heavy agencies depend on state rate updates that often trail wage inflation [23]. Operators balance this exposure by adding Medicare Advantage contracts and long-term care insurance clients.
What should families evaluate when choosing an elderly care provider?
Start with licensing status, recent inspection results, and staff turnover, since caregiver continuity strongly predicts care quality. Families should also confirm how the provider handles escalating needs, such as transitions to memory care or hospice, and request written fees for add-on services.
How are real estate investment trusts shaping senior housing in the Elderly Care Services Market?
Healthcare REITs such as Welltower increasingly share community-level profits with operators instead of collecting fixed rent [25]. This gives landlords direct exposure to occupancy and pricing, encouraging them to fund renovations and data systems that improve resident retention.
What integration challenges arise when adding remote monitoring to care operations?
Workflow is the main hurdle for the Elderly Care Services Market: sensor alerts must reach staff who can act on them without overwhelming shifts. Providers also need interoperability with electronic health records and clear consent policies for resident data.
Which regulatory differences matter most for cross-border operators in the Elderly Care Services Market?
Staffing ratios, licensing categories, and reimbursement rules vary sharply by country. Japan ties provider revenue to government fee schedules revised every three years, while U.S. private-pay assisted living faces lighter state-level oversight [11]. Entry strategies must reflect these structural differences.
Are franchise or company-owned models more resilient in home care?
Franchise networks scale quickly with less capital because local owners fund recruitment and marketing. Company-owned branches offer tighter quality control and easier payer contracting, which matters more as Medicaid and Medicare Advantage plans demand standardized reporting.
How are providers in the Elderly Care Services Market using AI for staffing?
AI scheduling tools match caregiver skills, location, and client preferences, cutting travel time and missed visits. Japanese operators such as Sompo Care apply care-record analytics to redesign workflows and reduce documentation burden on staff.
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author Co-Author Profile Garvit Vyas LinkedIn Vice President - Operations
Garvit Vyas is a Research Analyst with experience in working across multiple industry domains in the market research sector. Over the past four years, he has been actively involved in analyzing diverse markets, gathering industry insights, and contributing to the development of comprehensive research reports. His work includes studying market trends, evaluating competitive landscapes, and supporting data-driven business insights. In the early phase of his career, Garvit worked on cross-domain research projects, which helped him build a strong foundation in market analysis, data interpretation, and industry intelligence across various sectors. Later, he transitioned into the Quality Control (QC) function, where he focuses on reviewing and refining research reports and marketing collaterals to ensure accuracy, consistency, and high editorial standards. His responsibilities include validating research data, improving report structure, and maintaining the overall quality of published content. Garvit is committed to maintaining strong research integrity and delivering reliable insights that support informed business decision-making.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.