Segmentation Quick Reference
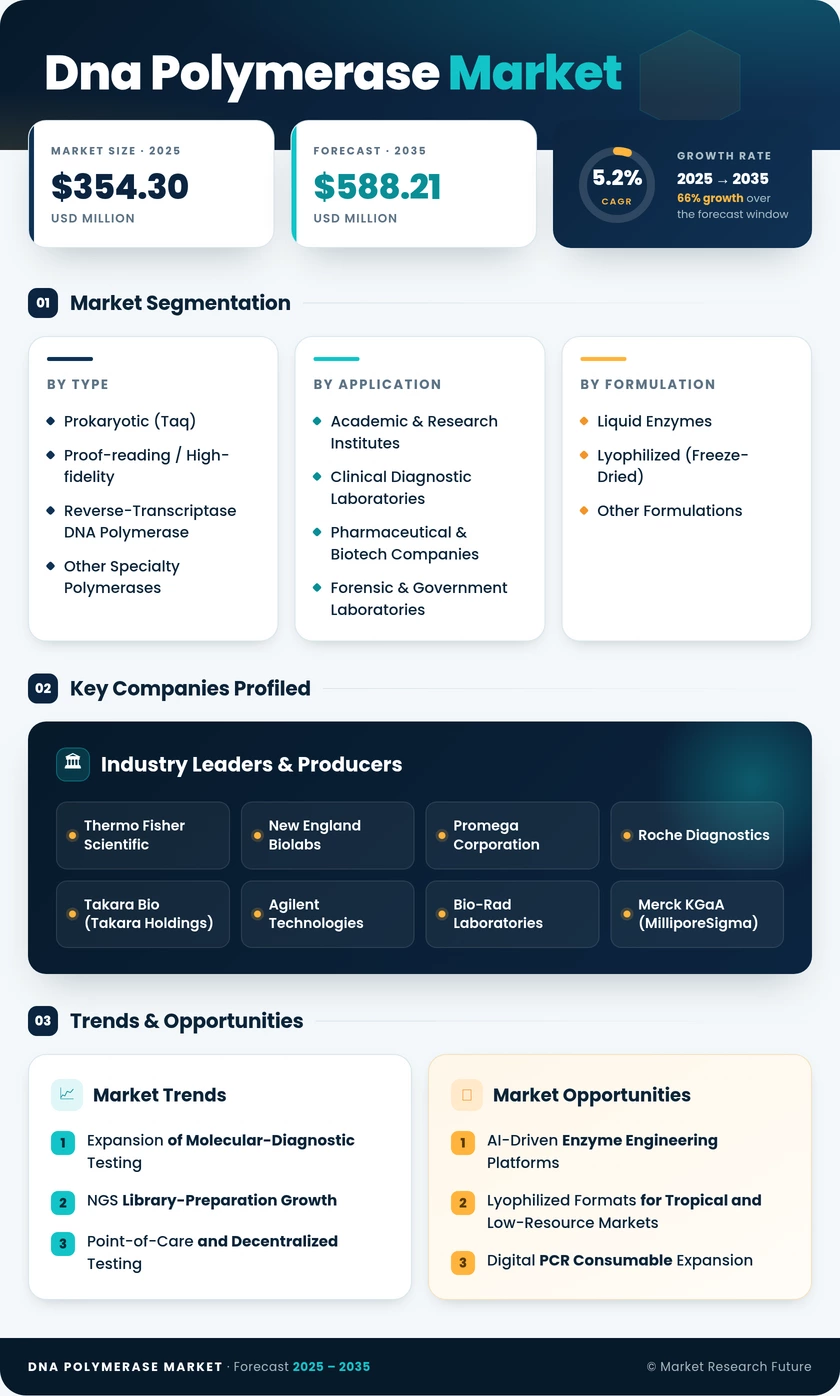
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| Product Type | Prokaryotic (Taq); Proof-reading / High-Fidelity; Reverse-Transcriptase DNA Polymerase; Other Specialty Polymerases | Prokaryotic (Taq) | Proof-reading / High-Fidelity |
| Application | Standard PCR; qPCR / Real-Time PCR; Digital PCR; DNA Sequencing & Library Prep; Other Applications | Standard PCR | Digital PCR |
| End User | Academic & Research Institutes; Clinical Diagnostic Laboratories; DNA Polymerase Market & Biotech Companies; Forensic & Government Laboratories | Academic & Research Institutes | Clinical Diagnostic Laboratories |
| Formulation | Liquid Enzymes; Lyophilized (Freeze-Dried); Other Formulations | Liquid Enzymes | Lyophilized (Freeze-Dried) |
| Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
| Prokaryotic (Taq) | Price competition from Asian generic manufacturers intensifying |
| Proof-reading / High-Fidelity | Adoption accelerating in clinical NGS library-prep workflows |
| Reverse-Transcriptase DNA Polymerase | Demand sustained by RNA-based diagnostic and gene-expression assays |
| Other Specialty Polymerases | Niche growth from isothermal amplification and strand-displacement applications |
Prokaryotic Taq polymerases remain the volume anchor of the market, while high-fidelity variants are gaining share as clinical sequencing protocols demand ultra-low error rates.
By Application
| Sub-Segment | Key Trend |
| Standard PCR | Stable high-volume demand from surveillance and routine genotyping |
| qPCR / Real-Time PCR | Sustained by viral-load monitoring and gene-expression quantification |
| Digital PCR | Rapid adoption in liquid-biopsy and rare-mutation detection |
| DNA Sequencing & Library Prep | Driven by whole-genome and whole-exome clinical sequencing scale-up |
| Other Applications | Includes cloning, site-directed mutagenesis, and forensic analysis |
Standard PCR remains the largest application by revenue, but digital PCR and sequencing-related applications are growing at rates roughly double the market average.
By End User
| Sub-Segment | Key Trend |
| Academic & Research Institutes | Largest buyer segment; price-sensitive; shifting toward multi-omics approaches |
| Clinical Diagnostic Laboratories | Fastest-growing segment; molecular-test-menu expansion drives procurement |
| DNA Polymerase Market & Biotech Companies | Quality-control and companion-diagnostic demand growing steadily |
| Forensic & Government Laboratories | DNA-profiling modernization programs driving replacement cycles |
Academic institutions purchase the highest volumes at the lowest average price points, while clinical diagnostic laboratories command higher per-unit value due to regulatory-grade requirements.
By Formulation
| Sub-Segment | Key Trend |
| Liquid Enzymes | Dominant format in cold-chain-equipped centralized laboratories |
| Lyophilized (Freeze-Dried) | Fastest-growing format; enables POC and tropical-climate deployment |
| Other Formulations | Includes bead-based and stabilized proprietary formats for field use |
Liquid enzymes will retain majority share through the forecast period, but lyophilized formats are projected to capture an increasing proportion of new-deployment revenue as point-of-care testing expands globally.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA