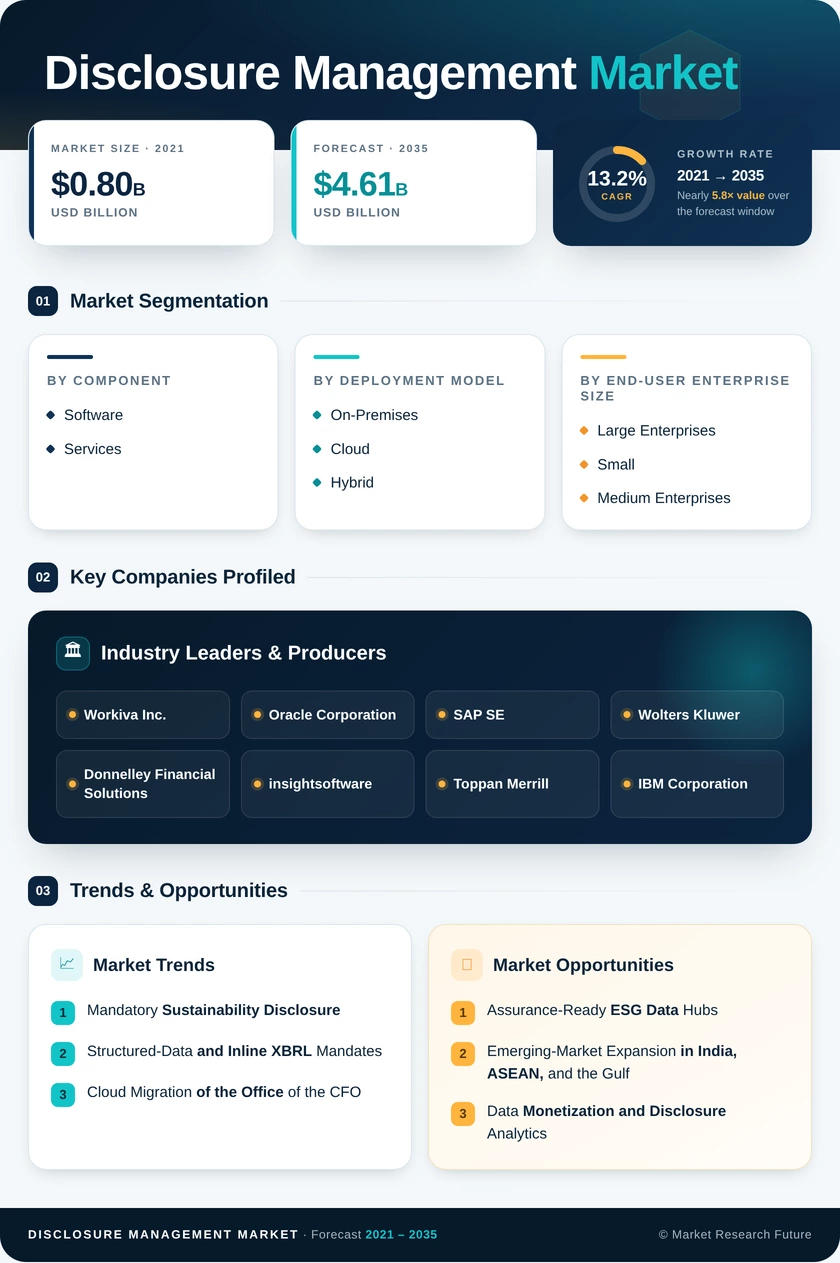
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Component | Software, Services | Software (57.2% share) | Services (13.6% CAGR) |
| By Deployment Model | On-Premises, Cloud, Hybrid | Cloud (13.9% CAGR) | Cloud (13.9% CAGR) |
| By End-User Enterprise Size | Large Enterprises, Small and Medium Enterprises | Large Enterprises (51.6% share) | Small and Medium Enterprises (14.0% CAGR) |
| By Application | Regulatory and Tax Filing, Financial Consolidation and Close, ESG Reporting, Others | Regulatory and Tax Filing (32.3% share) | ESG Reporting (14.1% CAGR) |
| By End-User Industry | BFSI, IT and Telecom, Healthcare, Manufacturing, Energy and Utilities, Government and Public Sector, Others | BFSI (36.4% share) | Energy and Utilities (14.8% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America (40.2% share) | Asia-Pacific (15.4% CAGR) |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
|---|---|
| Software | Consolidation of authoring, tagging, and review into one linked-data workspace |
| Services | Growth in taxonomy mapping, managed submissions, and advisory retainers |
Software leads the component split at a 57.2% share because every filing depends on an authoring and tagging environment that issuers license year after year. Services grow faster at a 13.6% CAGR, as each new ESRS, IFRS S2, or SEC taxonomy release creates mapping and template work that thinly staffed finance teams outsource. Vendors increasingly package both, turning implementation projects into recurring managed-service contracts.
By Deployment Model
| Sub-Segment | Key Trend |
|---|---|
| On-Premises | Retained in defense, banking, and government for hosting compliance |
| Cloud | Subscription delivery with automatic taxonomy and security updates |
| Hybrid | Connectors staging sensitive ledger data before cloud tagging |
Cloud is both the largest and fastest-growing deployment model, expanding at a 13.9% CAGR because subscriptions bundle taxonomy maintenance and enable real-time co-authoring at quarter-end. On-Premises holds a 22.6% share where regulators or internal policy bar external hosting of material non-public information. Hybrid setups act as a bridge, and their workloads should shift toward Cloud as vendors open in-region data centers.
By End-User Enterprise Size
| Sub-Segment | Key Trend |
|---|---|
| Large Enterprises | Multi-jurisdiction filing and multi-entity consolidation needs |
| Small and Medium Enterprises | Templated Inline XBRL and ESG filings on low-cost subscriptions |
Large Enterprises dominate with a 51.6% share, since multinational groups file across SEC, ESEF, and ESRS regimes and require role-based controls for hundreds of contributors. Small and Medium Enterprises grow fastest at a 14.0% CAGR as cloud pricing removes upfront licensing and regulatory requirements trickle down to smaller issuers. Vendors use land-and-expand tactics to lift contract values within this group.
By Application
| Sub-Segment | Key Trend |
|---|---|
| Regulatory and Tax Filing | Non-discretionary SEC, ESMA, and tax authority submissions |
| Financial Consolidation and Close | Direct linkage between close tools and reporting outputs |
| ESG Reporting | Pre-built ESRS, IFRS S2, and California climate templates |
| Others | Board packs, management reporting, and statutory accounts |
Regulatory and Tax Filing leads with a 32.3% share because mandated submissions recur every quarter or year regardless of economic conditions. ESG Reporting is the fastest-growing application at a 14.1% CAGR, as ISSB and ESRS adoption forces issuers to produce structured, assurance-ready sustainability data. Financial Consolidation and Close supports both by feeding validated figures directly into the reporting layer.
By End-User Industry
| Sub-Segment | Key Trend |
|---|---|
| BFSI | Overlapping securities, prudential, and insurance filings |
| IT and Telecom | Complex revenue and segment disclosures at listed growth firms |
| Healthcare | R&D and segment reporting for listed life sciences companies |
| Manufacturing | Consolidation across global subsidiaries and supply-chain data |
| Energy and Utilities | Emissions, transition plan and climate scenario disclosure |
| Government and Public Sector | Public-entity financial statements and transparency mandates |
| Others | Retail, consumer goods, and transportation reporting |
BFSI leads with a 36.4% share because banks and insurers juggle securities, prudential, and supervisory filings, often across several jurisdictions. Energy and Utilities is the fastest-growing industry at a 14.8% CAGR, as climate disclosure frameworks demand detailed emissions and transition-plan data from carbon-intensive issuers. Manufacturing and IT and Telecom add steady volume driven by multi-entity consolidation and complex revenue reporting.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA