Disclosure Management Market Summary
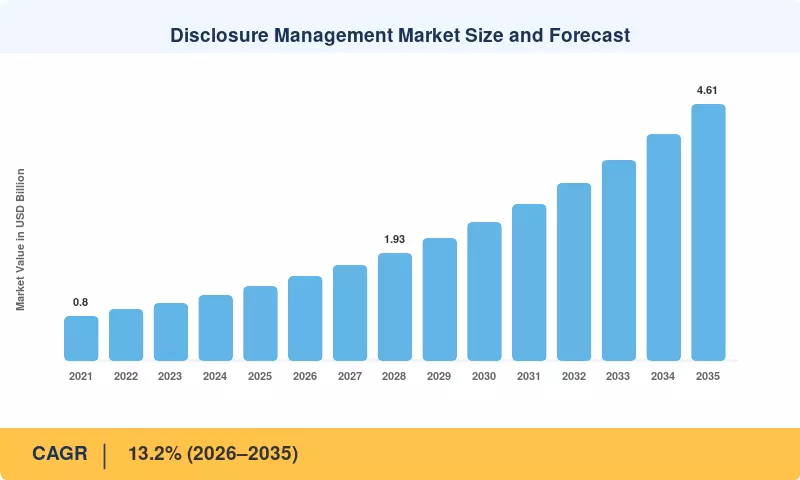
The global Disclosure Management Market was valued at $1.33 billion in 2025 and is projected to reach $1.51 billion in 2026, climbing to $4.61 billion by 2035 at a CAGR of 13.2% over 2026–2035. Two catalysts set the pace. The EU Corporate Sustainability Reporting Directive (CSRD) pushed the first wave of large issuers into audited, digitally tagged sustainability statements for financial year 2024 [4], and the ISSB's IFRS S1 and S2 standards are now being adopted or referenced across more than 30 jurisdictions [9][10]. Each mandate converts a narrative obligation into a structured-data obligation, which is precisely where disclosure platforms earn their fees.
Finance teams are retiring a reporting stack that has barely changed in two decades: Word and Excel files stitched together by email, manual tie-outs, and desktop-bound SEC filing software operated by outsourced typesetters. Cloud-native platforms replace that stack with a single linked data layer, where one change to a trial-balance figure flows automatically into the 10-K, the investor presentation, and the Inline XBRL instance. The SEC's Inline XBRL rule, fully phased in for operating companies by 2021 [1], and the EU's European Single Electronic Format (ESEF) [8] made that shift non-negotiable for listed issuers.
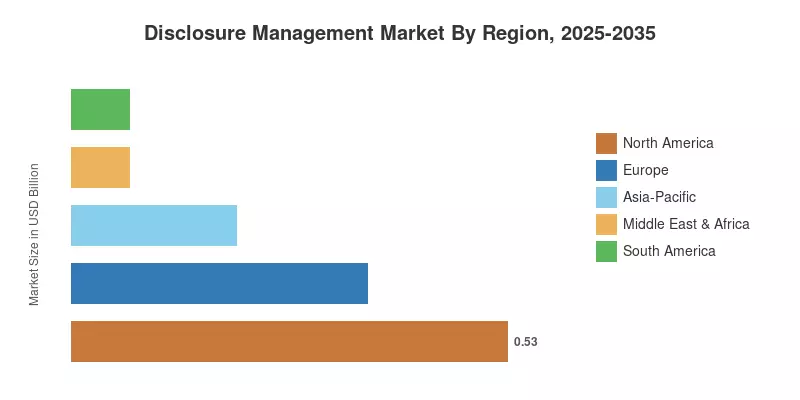
North America leads with a 40.2% revenue share in 2025, supported by the world's deepest pool of SEC registrants and early cloud adoption among corporate controllers. Asia-Pacific is the fastest-growing region at a 15.4% CAGR, driven by India's BRSR Core regime and Japan's new SSBJ standards [14][15]. Europe ranks second, as CSRD, ESRS digital tagging, and the forthcoming European Single Access Point lift demand for audit-ready reporting [7][21]. Over the next decade, competitive advantage will shift from formatting speed to data lineage and assurance readiness.
Key Report Takeaways
• By Component
- Software accounts for 57.2% of Disclosure Management Market revenue in 2025, reflecting its installed base across consolidation, tagging, and narrative editing workflows.
- Services is the faster-growing component at a 13.6% CAGR, as issuers outsource taxonomy mapping, template customization, and managed submissions.
• By Deployment Model
- Cloud is the largest and fastest-expanding deployment model, growing at a 13.9% CAGR on subscription pricing and automatic taxonomy updates.
- On-Premises retains a 22.6% share, concentrated in defense, banking, and government entities with strict hosting rules.
• By End-User Enterprise Size
- Large Enterprises contribute 51.6% of spending, because multi-entity groups require advanced controls and multi-taxonomy libraries.
- Small and Medium Enterprises advance at a 14.0% CAGR as cloud subscriptions remove upfront licensing costs.
• By Application
- Regulatory and Tax Filing holds a 32.3% share of the Disclosure Management Market, anchored by mandatory SEC and ESMA submissions.
- ESG Reporting is the fastest-growing application at a 14.1% CAGR, lifted by ISSB and ESRS adoption.
• By End-User Industry
- BFSI leads with a 36.4% share, driven by dense prudential, securities, and insurance reporting calendars.
- Energy and Utilities post the quickest growth at a 14.8% CAGR, as climate disclosure lands hardest on emissions-intensive issuers.
• By Region
- North America holds 40.2% of the Disclosure Management Market in 2025, the largest regional position.
- Asia-Pacific grows at a 15.4% CAGR, the highest of any region.
- Europe generated $0.36 billion in 2025 revenue, the second-largest regional pool.
Market Size and Forecast (2021–2035)
Market Research Future sized the Disclosure Management Market through a bottom-up build of vendor revenues drawn from annual reports and investor filings, cross-checked against a top-down estimate of issuer populations subject to SEC, ESEF, ESRS, and national filing mandates. Historical values for 2021–2024 reflect reported vendor revenue and interviews with finance and reporting leaders. The year 2025 serves as the base, and the 2026–2035 forecast applies adoption curves tied to regulatory effective dates in each region [1][4][9].





 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


