Digital Door Lock Systems Market (2026 – 2035)

ID: MRFR/SEM/3699-HCR 200 Pages Kiran Jinkalwad Last Updated: September 15, 2026
Digital Door Lock Systems Market Size, Share and Research Report By Product Type (Deadbolts, Lever Handles, Padlocks, and Others), By Technology (Biometric, Keypad/PIN, RFID/Smart Card, and Connectivity), By End-User (Residential, Commercial, Industrial, and Government), By Sales Channel (Offline and Online) And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) – Industry Forecast Till 2035
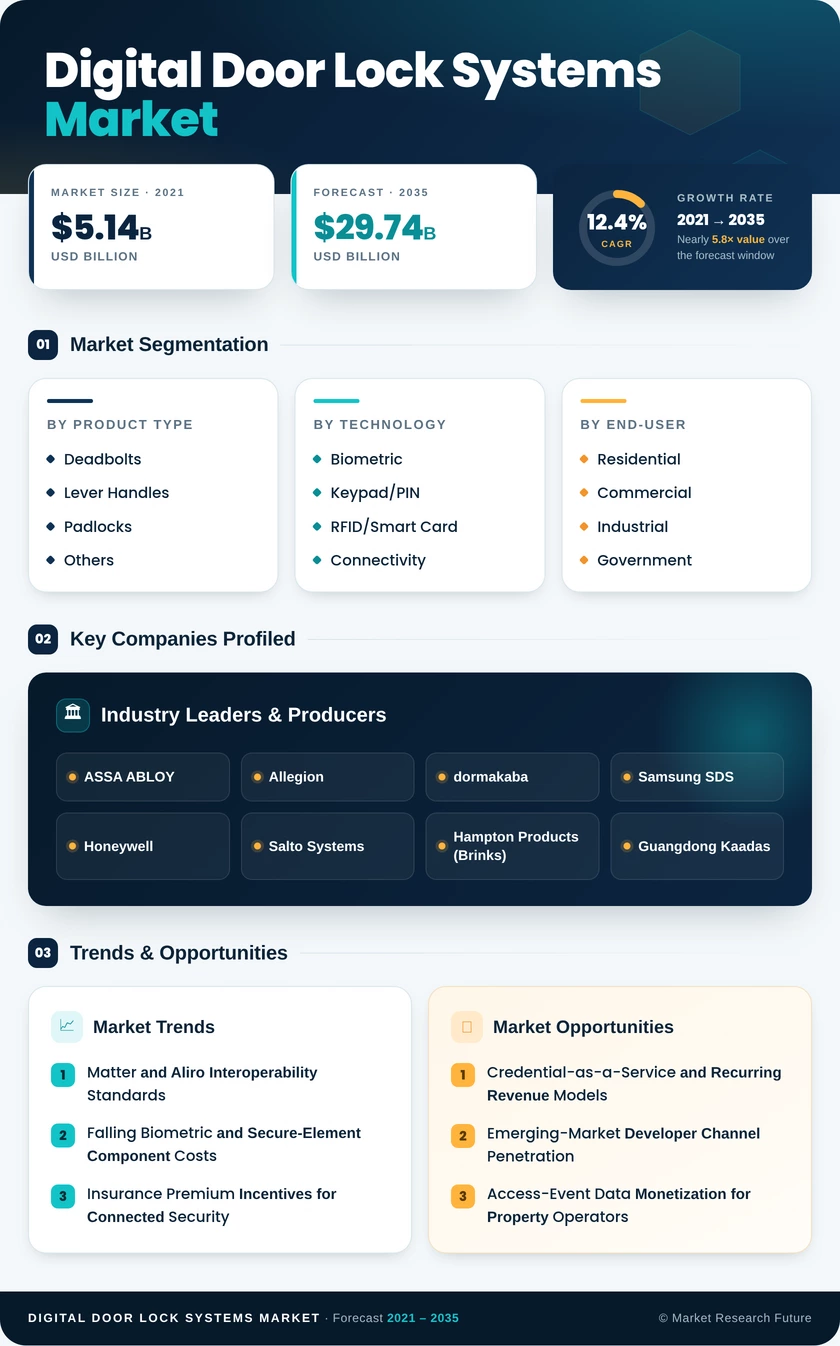
Digital Door Lock Systems Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)12.4%
2025 Market SizeUSD 8.52 Billion
2030 Market SizeUSD 15.26 Billion
2035 Market SizeUSD 29.74 Billion
Key Players
ASSA ABLOY
Allegion
dormakaba
Samsung SDS
Honeywell
Salto Systems
Opportunities
  • Credential-as-a-Service and Recurring Revenue Models
  • Emerging-Market Developer Channel Penetration
  • Access-Event Data Monetization for Property Operators
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Product Type | |
    2. 2.2 By Technology | |
    3. 2.3 By End-User | |
    4. 2.4 By Sales Channel | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Matter and Aliro Interoperability Standards | |
    2. 4.2 Falling Biometric and Secure-Element Component Costs | |
    3. 4.3 Insurance Premium Incentives for Connected Security | |
    4. 4.4 High-Density Residential Construction | |
    5. 4.5 Short-Stay Rental and Property-Management Automation | |
    6. 4.6 Enterprise Access-Audit Compliance Mandates | |
    7. 4.7 Mobile Credential Adoption in Hospitality | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Cybersecurity Vulnerabilities and Firmware Exploits | |
    2. 5.2 Battery Dependency and Power-Failure Anxiety | |
    3. 5.3 Installed-Base Mechanical Inertia and Retrofit Friction | |
    4. 5.4 Price Sensitivity in Emerging Economies | |
    5. 5.5 Fragmented Building Codes and Fire-Door Certification | |
  6. 6 Opportunities | |
    1. 6.1 Credential-as-a-Service and Recurring Revenue Models | |
    2. 6.2 Emerging-Market Developer Channel Penetration | |
    3. 6.3 Access-Event Data Monetization for Property Operators | |
    4. 6.4 Ultra-Wideband Hands-Free Entry Premiumization | |
    5. 6.5 Retrofit-Native Product Architecture | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Credential Convergence and the End of Brand Silos | |
    2. 8.2 AI-Assisted Anomaly Detection in Access Patterns | |
    3. 8.3 Energy Efficiency and Battery Chemistry Advances | |
    4. 8.4 Sustainability Reporting and Circular Hardware Design | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Product Type | | |
      1. 9.1.1 Deadbolts | | |
      2. 9.1.2 Lever Handles | | |
      3. 9.1.3 Padlocks | | |
      4. 9.1.4 Others | |
    2. 9.2 By Technology | | |
      1. 9.2.1 Biometric | | |
      2. 9.2.2 Keypad/PIN | | |
      3. 9.2.3 RFID/Smart Card | | |
      4. 9.2.4 Connectivity | |
    3. 9.3 By End-User | | |
      1. 9.3.1 Residential | | |
      2. 9.3.2 Commercial | | |
      3. 9.3.3 Industrial | | |
      4. 9.3.4 Government | |
    4. 9.4 By Sales Channel | | |
      1. 9.4.1 Offline | | |
      2. 9.4.2 Online | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Digital Door Lock Systems Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Digital Door Lock Systems Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Digital Door Lock Systems Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Digital Door Lock Systems Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Digital Door Lock Systems Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Digital Door Lock Systems Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Digital Door Lock Systems Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Digital Door Lock Systems Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Digital Door Lock Systems Market Size, by Product Type, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Digital Door Lock Systems Market Size, by Technology, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Digital Door Lock Systems Market Size, by End-User, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Digital Door Lock Systems Market Size, by Sales Channel, 2021–2035 (USD Billion) | |
  29. TABLE 15 Competitive Benchmarking Matrix, 2026 | |
  30. TABLE 16 Company Profiles – Key Players | |
  31. TABLE 17 Recent Developments & Strategic Announcements, 2023–2025 | |
  32. TABLE 18 Report Scope & Methodology Summary | |
  33. TABLE 19 Detailed Sources and Citations Index | |
  34. TABLE 20 Segmentation Quick Reference Matrix | | LIST OF FIGURES | |
  35. FIGURE 1 Market Dynamics – Drivers, Restraints, and Opportunities Overview | |
  36. FIGURE 2 Industry Value Chain Analysis – Digital Door Lock Systems | |
  37. FIGURE 3 Porter's Five Forces Analysis | |
  38. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  39. FIGURE 5 Year-over-Year Growth Rate Trend, 2022–2035 (%) | |
  40. FIGURE 6 Market Share by Product Type, 2024 (%) | |
  41. FIGURE 7 Market Share by Technology, 2024 (%) | |
  42. FIGURE 8 Market Share by End-User, 2024 (%) | |
  43. FIGURE 9 Market Share by Sales Channel, 2024 (%) | |
  44. FIGURE 10 Regional Market Share Distribution, 2024 (%) | |
  45. FIGURE 11 Regional CAGR Comparison, 2026–2035 (%) | |
  46. FIGURE 12 Competitive Landscape – Revenue Share Positioning, 2026 | |
  47. FIGURE 13 Company Strategic Positioning Matrix | |
  48. FIGURE 14 Technology Adoption Curve, 2021–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Product TypeDeadbolts, Lever Handles, Padlocks, OthersDeadbolts (35.8% share, 2024)Padlocks (14.5% CAGR)
By TechnologyBiometric, Keypad/PIN, RFID/Smart Card, ConnectivityKeypad/PIN (44.1% share, 2024)Connectivity (15.0% CAGR)
By End-UserResidential, Commercial, Industrial, GovernmentResidential (58.1% share, 2024)Industrial (15.3% CAGR)
By Sales ChannelOffline, OnlineOffline (66.5% share, 2024)Online (15.4% CAGR)


Market Segmentation Overview

By Product Type

Sub-SegmentKey Trend
DeadboltsDrop-in retrofit compatibility with standard 2⅛-inch bore preps keeps installed cost near hardware cost
Lever HandlesAccessibility code requirements sustain specification across commercial corridors and healthcare
PadlocksApp-controlled units managing hundreds of users displace mechanical gate and container locks
OthersRim and mortise bodies serve heritage doors and regional standards where tubular formats do not fit


Deadbolts lead this dimension because retrofit installation requires no carpentry, which matters most in the mature single-family stock that generates the largest replacement volume. Padlocks grow fastest as logistics and utility operators digitize distributed assets — gates, cabinets, containers — where wiring is impossible and credential revocation must happen remotely. Lever handles hold commercial position through accessibility compliance rather than technology preference, and rim and mortise formats remain a specification-driven niche tied to building age.

By Technology

Sub-SegmentKey Trend
BiometricFingerprint module costs near USD 2.40 push capability into mid-tier retail price bands
Keypad/PINSmartphone-independent operation sustains adoption across all income and age brackets
RFID/Smart CardCentralized credential auditing retains offices with existing badge infrastructure
ConnectivityMatter and Aliro certification enables multi-brand enrollment through a single application


Keypad and PIN entry leads because it requires no phone, hub, or enrollment step — decisive for rental turnover and older users. Connectivity grows fastest as Wi-Fi, Bluetooth, Z-Wave, and Thread implementations gain cross-ecosystem certification, shifting differentiation from mechanical strength to credential experience. Biometric adoption tracks sensor pricing rather than demand, while RFID and smart-card variants persist wherever badge systems already govern building access and replacement would strand that investment.

By End-User

Sub-SegmentKey Trend
ResidentialSmart-home bundles and retail distribution drive first-time adoption at scale
CommercialMulti-door scheduling and audit trails support software subscription attach
IndustrialCompliance mandates for timestamped access records accelerate mechanical key replacement
GovernmentFIPS and equivalent certification requirements narrow the qualified vendor field


Residential dominates on door count and retail accessibility, with purchase decisions driven by convenience and insurance economics rather than compliance. Industrial demand grows fastest because documented access and remote revocation are becoming audit requirements at utilities, data centers, and logistics sites — obligations mechanical keys cannot satisfy at any price. Commercial buyers sit between the two, valuing scheduling and integration, while government procurement concentrates among certified incumbents.

By Sales Channel

Sub-SegmentKey Trend
OfflinePhysical product assessment and bundled same-day installation retain time-sensitive buyers
OnlineDirect-to-consumer pricing, tutorial content, and subscription attach at checkout drive share gains


Offline retains the majority because buyers want to handle the hardware and, for commercial projects, need installation contracted alongside purchase. Online grows faster as brands sell direct, attach credential subscriptions during checkout, and use installation video content to reduce the perceived risk that once kept self-installation buyers in stores. Direct-channel telemetry also gives manufacturers faster product feedback than distributor-mediated sales permit.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.