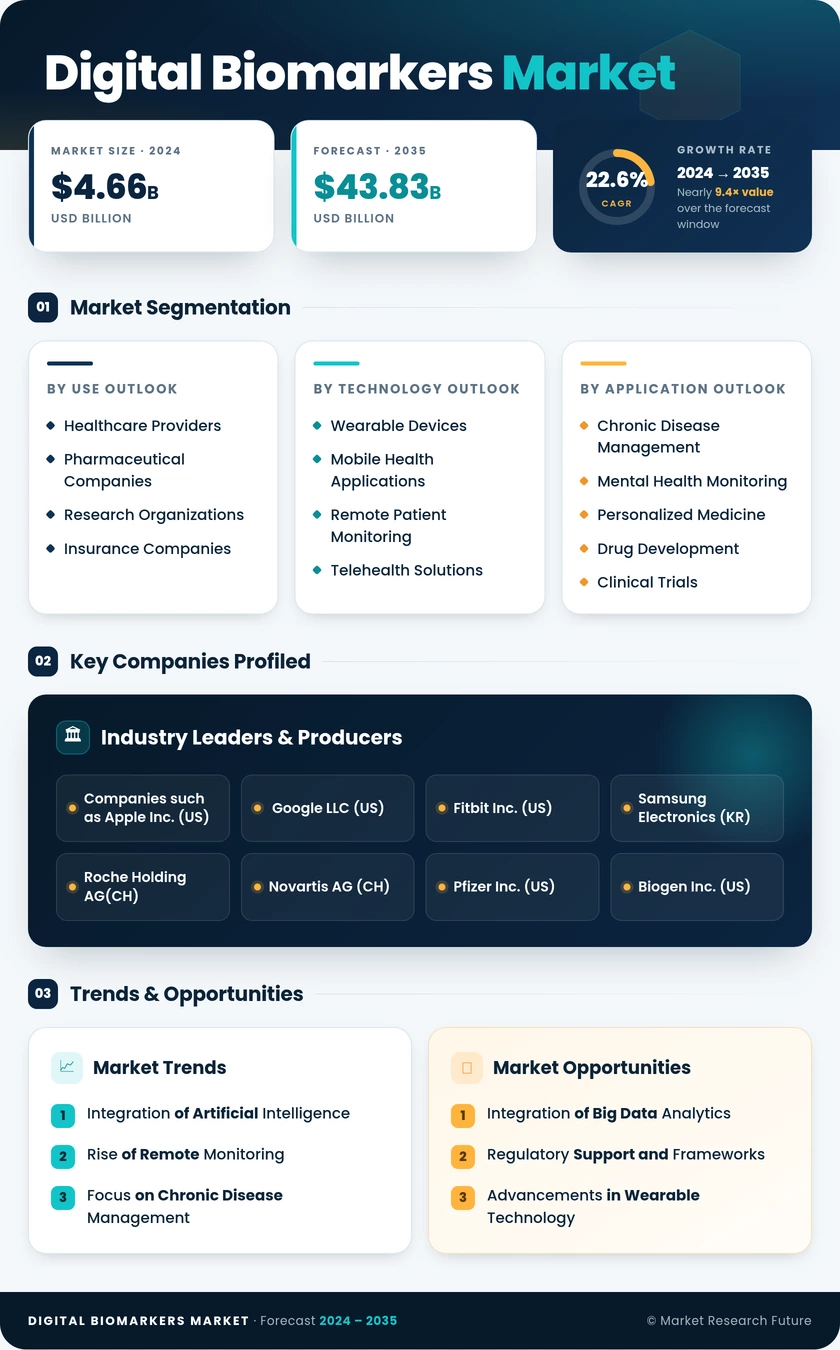
Digital Biomarkers Market (2026 - 2035)

ID: MRFR/HC/10766-HCR 200 Pages Vikita Thakur Last Updated: September 15, 2026
Digital Biomarkers Market Research Report: Size, Share, Trend Analysis By Applications (Chronic Disease Management, Mental Health Monitoring, Personalized Medicine, Drug Development, Clinical Trials), By Technology (Wearable Devices, Mobile Health Applications, Remote Patient Monitoring, Telehealth Solutions), By End Use (Healthcare Providers, Pharmaceutical Companies, Research Organizations, Insurance Companies), By Data Source (Physiological Data, Behavioral Data, Psychological Data, Genetic Data) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2025 To 2035
Digital Biomarkers Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)18.6%
2025 Market SizeUSD 4.18 Billion
2035 Market SizeUSD 23.02 Billion
Key Players
Koninklijke Philips N.V.
Medtronic plc
Apple Inc.
Biogen Inc.
Huma Therapeutics
Evidation Health
Opportunities
  • Neurodegenerative Disease Endpoint Franchises
  • Emerging-Market Leapfrog Deployments
  • Data Monetisation and Endpoint-as-a-Service Models
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways |
    1. 2.1 By Component |
    2. 2.2 By Therapeutic Area |
    3. 2.3 By Geography
  3. 3 Global Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2025) |
    2. 3.2 Current & Forecast Market Size (2026–2035) |
    3. 3.3 Market Size by Revenue (USD billion) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Market Drivers Analysis |
    1. 4.1 Regulatory Qualification of Sensor-Derived Endpoints |
    2. 4.2 Decentralized & Hybrid Clinical Trial Adoption |
    3. 4.3 Reimbursement Expansion & Value-Based Care |
    4. 4.4 Sensor Cost Decline & Analytical Model Capability
  5. 5 Market Restraints Analysis |
    1. 5.1 Clinical Validation Cost & Evidence Burden |
    2. 5.2 Data Privacy, Consent & Cross-Border Transfer |
    3. 5.3 Interoperability Gaps & Proprietary Formats |
    4. 5.4 Clinician Workflow Burden & Alert Fatigue |
    5. 5.5 Reimbursement Uncertainty Outside Pilot Programmes
  6. 6 Market Opportunity Analysis |
    1. 6.1 Neurodegenerative Disease Endpoint Franchises |
    2. 6.2 Emerging-Market Leapfrog Deployments |
    3. 6.3 Data Monetisation & Endpoint-as-a-Service Models |
    4. 6.4 Payer-Led Population Risk Stratification |
    5. 6.5 Regulatory-Grade Software Toolchains |
    6. 6.6 Industry Value Chain Analysis |
    7. 6.7 Porter's Five Forces Analysis
  7. 7 Regional Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Foundation Models & Predictive Analytics |
    2. 8.2 Platform Economics & Margin Migration |
    3. 8.3 Endpoint Standardisation & Pre-Competitive Consortia |
    4. 8.4 Integration into Routine Care Delivery
  9. 9 Segmentation Analysis |
    1. 9.1 By Component | |
      1. 9.1.1 Data Collection Tools | |
      2. 9.1.2 Data Integration & Analytics Platforms |
    2. 9.2 By Data Source | |
      1. 9.2.1 Wearables | |
      2. 9.2.2 Smartphones & Mobile Apps | |
      3. 9.2.3 Implantables | |
      4. 9.2.4 Ingestibles | |
      5. 9.2.5 Other Sources |
    3. 9.3 By Therapeutic Area | |
      1. 9.3.1 Neurological Disorders | |
      2. 9.3.2 Cardiovascular Disorders | |
      3. 9.3.3 Diabetes & Metabolic | |
      4. 9.3.4 Respiratory Diseases | |
      5. 9.3.5 Sleep & Behavioural Health | |
      6. 9.3.6 Oncology | |
      7. 9.3.7 Other Areas |
    4. 9.4 By Clinical Practice | |
      1. 9.4.1 Monitoring Digital Biomarkers | |
      2. 9.4.2 Diagnostic Digital Biomarkers | |
      3. 9.4.3 Predictive & Prognostic Digital Biomarkers | |
      4. 9.4.4 Response Digital Biomarkers | |
      5. 9.4.5 Safety & Susceptibility Digital Biomarkers |
    5. 9.5 By End User | |
      1. 9.5.1 Pharmaceutical & Biotech Companies | |
      2. 9.5.2 Healthcare Providers | |
      3. 9.5.3 Payers | |
      4. 9.5.4 Healthcare & Research Institutes | |
      5. 9.5.5 Others
  10. 10 Competitive Landscape |
    1. 10.1 Market Share Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Koninklijke Philips N.V. | |
      2. 10.3.2 Medtronic plc | |
      3. 10.3.3 Apple Inc. | |
      4. 10.3.4 Biogen Inc. | |
      5. 10.3.5 Huma Therapeutics | |
      6. 10.3.6 Evidation Health | |
      7. 10.3.7 AliveCor Inc. | |
      8. 10.3.8 Koneksa Health | |
      9. 10.3.9 Biofourmis | |
      10. 10.3.10 Empatica Inc. | |
      11. 10.3.11 ActiGraph LLC | |
      12. 10.3.12 IXICO plc
  11. 11 Recent Developments & News
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Citations |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions (FAQs)
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Digital Biomarkers Market Size & Forecast, by Revenue (USD billion), 2021–2035 |
  17. TABLE 2 Global Digital Biomarkers Market – Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis – Impact on CAGR, Geographic Relevance & Timeline |
  19. TABLE 4 Restraint Impact Analysis – Impact on CAGR, Geographic Relevance & Timeline |
  20. TABLE 5 Global Digital Biomarkers Market Size, by Region, 2021–2035 (USD billion) |
  21. TABLE 6 North America Digital Biomarkers Market Size, by Country, 2021–2035 (USD billion) |
  22. TABLE 7 Europe Digital Biomarkers Market Size, by Country, 2021–2035 (USD billion) |
  23. TABLE 8 Asia-Pacific Digital Biomarkers Market Size, by Country, 2021–2035 (USD billion) |
  24. TABLE 9 South America Digital Biomarkers Market Size, by Country, 2021–2035 (USD billion) |
  25. TABLE 10 Middle East & Africa Digital Biomarkers Market Size, by Country, 2021–2035 (USD billion) |
  26. TABLE 11 Global Digital Biomarkers Market Size, by Component, 2021–2035 (USD billion) |
  27. TABLE 12 Global Digital Biomarkers Market Size, by Data Source, 2021–2035 (USD billion) |
  28. TABLE 13 Global Digital Biomarkers Market Size, by Therapeutic Area, 2021–2035 (USD billion) |
  29. TABLE 14 Global Digital Biomarkers Market Size, by Clinical Practice, 2021–2035 (USD billion) |
  30. TABLE 15 Global Digital Biomarkers Market Size, by End User, 2021–2035 (USD billion) |
  31. TABLE 16 North America Digital Biomarkers Market Size, by Component & Data Source, 2021–2035 (USD billion) |
  32. TABLE 17 Europe Digital Biomarkers Market Size, by Therapeutic Area & End User, 2021–2035 (USD billion) |
  33. TABLE 18 Asia-Pacific Digital Biomarkers Market Size, by Component & Clinical Practice, 2021–2035 (USD billion) |
  34. TABLE 19 South America Digital Biomarkers Market Size, by Data Source & End User, 2021–2035 (USD billion) |
  35. TABLE 20 Middle East & Africa Digital Biomarkers Market Size, by Therapeutic Area, 2021–2035 (USD billion) |
  36. TABLE 21 Competitive Benchmarking Matrix – Global Digital Biomarkers Market, 2026 |
  37. TABLE 22 Company Profiles – Key Players, Global Digital Biomarkers Market |
  38. TABLE 23 Recent Developments & Strategic Announcements, 2023–2025 |
  39. TABLE 24 Report Scope & Methodology Summary |
  40. TABLE 25 Detailed Sources & Citations Index
  41. 16 LIST OF FIGURES |
  42. FIGURE 1 Global Digital Biomarkers Market – Market Dynamics Overview (Drivers, Restraints, Opportunities) |
  43. FIGURE 2 Industry Value Chain Analysis – Sensor to Evidence |
  44. FIGURE 3 Porter's Five Forces Analysis |
  45. FIGURE 4 Global Market Size Trend & Forecast, 2021–2035 (USD billion) |
  46. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 (%) |
  47. FIGURE 6 Market Share by Component, 2025 vs 2035 (%) |
  48. FIGURE 7 Market Share by Data Source, 2025 (%) |
  49. FIGURE 8 Market Share by Therapeutic Area, 2025 (%) |
  50. FIGURE 9 Market Share by Clinical Practice, 2025 (%) |
  51. FIGURE 10 Market Share by End User, 2025 (%) |
  52. FIGURE 11 Regional Market Share Distribution, 2025 (%) |
  53. FIGURE 12 Regional CAGR Comparison, 2026–2035 (%) |
  54. FIGURE 13 Country-Level Revenue Contribution – Top 10 Markets, 2025 |
  55. FIGURE 14 Competitive Landscape – Estimated Revenue Share Distribution, 2026 |
  56. FIGURE 15 Strategic Positioning Matrix – Capability vs Regulatory Depth |
  57. FIGURE 16 Regulatory Milestone Timeline, 2023–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentData Collection Tools; Data Integration & Analytics PlatformsData Collection ToolsData Integration & Analytics Platforms
By Data SourceWearables; Smartphones & Mobile Apps; Implantables; Ingestibles; Other SourcesWearablesImplantables
By Therapeutic AreaNeurological Disorders; Cardiovascular Disorders; Diabetes & Metabolic; Respiratory Diseases; Sleep & Behavioural Health; Oncology; Other AreasNeurological DisordersOncology
By Clinical PracticeMonitoring; Diagnostic; Predictive & Prognostic; Response; Safety & SusceptibilityMonitoring Digital BiomarkersPredictive & Prognostic Digital Biomarkers
By End UserPharmaceutical & Biotech Companies; Healthcare Providers; Payers; Healthcare & Research Institutes; OthersPharmaceutical & Biotech CompaniesPayers
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
Data Collection ToolsSensor bill-of-materials cost decline pushing hardware toward commodity pricing.
Data Integration & Analytics PlatformsRegulatory-grade pipelines with audit trails becoming a procurement requirement.


Hardware still captures the larger revenue pool, but the strategic centre of gravity has already shifted. Buyers who once evaluated devices now evaluate whether a vendor can defend an algorithm in front of a regulator.

By Data Source

Sub-SegmentKey Trend
WearablesWrist-worn medical clearances extending consumer hardware into regulated workflows
Smartphones & Mobile AppsZero-hardware deployment models scaling rapidly in South Asia and Latin America
ImplantablesUninterrupted telemetry preferred for cardiology regulatory submissions.
IngestiblesAdherence verification gaining traction in psychiatry and tuberculosis therapy.
Other SourcesAmbient and voice sensing emerging for cognitive and respiratory assessment.


Source diversity is increasing rather than consolidating. Sponsors now routinely combine two or three modalities per study, which is precisely what drives platform demand.

By Therapeutic Area

Sub-SegmentKey Trend
Neurological DisordersComposite digital endpoints entering regulatory qualification pipelines
Cardiovascular DisordersPopulation-scale arrhythmia screening generating clinical referral volume.
Diabetes & MetabolicContinuous glucose ecosystems expanding into pre-diabetes populations
Respiratory DiseasesExacerbation prediction models reaching clinically actionable lead times
Sleep & Behavioural HealthConsumer sleep metrics migrating into formal clinical assessment
OncologyPerformance status and toxicity capture supplementing clinician grading.
Other AreasRare disease and musculoskeletal niches funded by patient advocacy groups


Therapeutic concentration reflects measurement difficulty more than disease prevalence. Where existing instruments are blunt, continuous capture delivers the largest incremental value.

By Clinical Practice

Sub-SegmentKey Trend
Monitoring Digital BiomarkersAnchored by reimbursed chronic disease and post-discharge programmes
Diagnostic Digital BiomarkersTriage applications reducing unnecessary specialist referrals
Predictive & Prognostic Digital BiomarkersRisk stratification tied directly to value-based contract performance.
Response Digital BiomarkersTreatment efficacy signals shortening trial readout timelines
Safety & Susceptibility Digital BiomarkersContinuous adverse event detection strengthening pharmacovigilance.


Monitoring dominates today because it is the only category with mature reimbursement. Predictive applications grow fastest because they change clinical decisions rather than merely documenting them.

By End User

Sub-SegmentKey Trend
Pharmaceutical & Biotech CompaniesPortfolio-wide endpoint standardisation replacing study-by-study procurement.
Healthcare ProvidersReimbursement availability now the primary gate on adoption pace
PayersCost-avoidance modelling driving direct vendor contracting
Healthcare & Research InstitutesGrant-funded validation cohorts underpinning regulatory dossiers
OthersEmployers and CROs entering as intermediary purchasers


Buyer mix is broadening in a way that changes pricing power. Sponsors tolerate premium rates; payers and providers will not, which pushes vendors toward tiered commercial architectures over the forecast decade.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.