Digital Biomarkers Market (2026 - 2035)

Digital Biomarkers Market Research Report: Size, Share, Trend Analysis By Applications (Chronic Disease Management, Mental Health Monitoring, Personalized Medicine, Drug Development, Clinical Trials), By Technology (Wearable Devices, Mobile Health Applications, Remote Patient Monitoring, Telehealth Solutions), By End Use (Healthcare Providers, Pharmaceutical Companies, Research Organizations, Insurance Companies), By Data Source (Physiological Data, Behavioral Data, Psychological Data, Genetic Data) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2025 To 2035
ID: MRFR/HC/10766-HCR 200 Pages Vikita Thakur, Rahul Gotadki Last Updated: September 15, 2026
Digital Biomarkers Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)18.6%
2025 Market SizeUSD 4.18 Billion
2035 Market SizeUSD 23.02 Billion
Key Players
Koninklijke Philips N.V.
Medtronic plc
Apple Inc.
Biogen Inc.
Huma Therapeutics
Evidation Health
Opportunities
  • Neurodegenerative Disease Endpoint Franchises
  • Emerging-Market Leapfrog Deployments
  • Data Monetisation and Endpoint-as-a-Service Models

Digital Biomarkers Market Summary

The Digital Biomarkers Market was valued at USD 4.18 billion in 2025 and opens the forecast window at USD 4.96 billion in 2026, climbing to USD 23.02 billion by 2035 at a 18.6% CAGR. Two catalysts anchor that trajectory. The US Food and Drug Administration's Digital Health Center of Excellence has now qualified several sensor-derived endpoints under its Drug Development Tool pathway [1], and the European Health Data Space regulation, adopted in 2025, obliges member states to make interoperable electronic health records available for secondary research use [2]. Both actions convert measurement innovation into reimbursable, submissible evidence.

Legacy episodic assessment – a six-minute walk test in a clinic hallway, a paper symptom diary, a quarterly HbA1c draw – is giving way to continuous passive recording using consumer-grade sensors and certified medical wearables. In 2024 alone, pharmaceutical sponsors spent around USD 2.4 billion on decentralized and hybrid trial infrastructure [3], and approximately 38% of protocols registered that year for Phase II/III trials included at least one sensor-derived endpoint [4]. That shift is what makes the Digital Biomarkers Market fundamentally different from previous telehealth cycles.


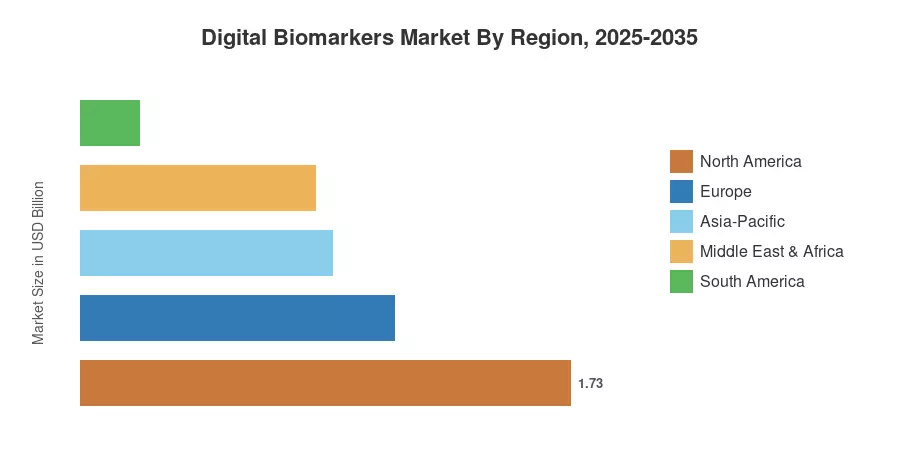
North America is expected to generate 41.5% of revenue in 2025, supported by FDA precedent and payer pilots. Asia-Pacific is the fastest-growing region with a CAGR of 21.4% through 2035, driven by China’s smart-hospital program and India’s Ayushman Bharat Digital Mission. In second place is Europe, at an estimated USD 1.11 billion, where the EU AI Act’s medical-device carve-outs are shaping validation practice. The next decade will reward companies that own the evidence, not just the sensor.


Key Report Takeaways

• By Component

  • Data Collection Tools account for 56% of 2025 Digital Biomarkers Market revenue, reflecting continued hardware and firmware spend at the edge.
  • Data Integration & Analytics Platforms post the fastest trajectory at a 20.3% CAGR as sponsors consolidate fragmented sensor feeds

• By Therapeutic Area

  • Neurological Disorders lead with USD 1.09 billion in 2025, driven by Alzheimer's and Parkinson's digital endpoint qualification.
  • Cardiovascular applications hold a 23% share, anchored by atrial fibrillation detection at consumer scale.
  • Oncology, though small today, expands at a 22.8% CAGR on patient-reported outcome integration

• By Geography

  • North America contributes 41.5% of global Digital Biomarkers Market revenue in 2025
  • Asia-Pacific advances at a 21.4% CAGR, the fastest of any region across the Digital Biomarkers Market
  • Middle East & Africa reaches USD 0.17 billion in 2025, concentrated in Gulf-state hospital digitisation.


Market Size and Forecast (2021–2035)

The figures below combine bottom-up vendor revenue mapping for over 140 device, platform and analytics vendors with top-down validation against pharmaceutical R&D disclosures, payer pilot budgets and regulatory submission counts. Where possible, historical years are reconciled to audited filings; forecast years use therapeutic-area cohort-based adoption curves. The Digital Biomarkers Market is measured in terms of end-user value, net of hardware sold outside of a clinical or research setting.
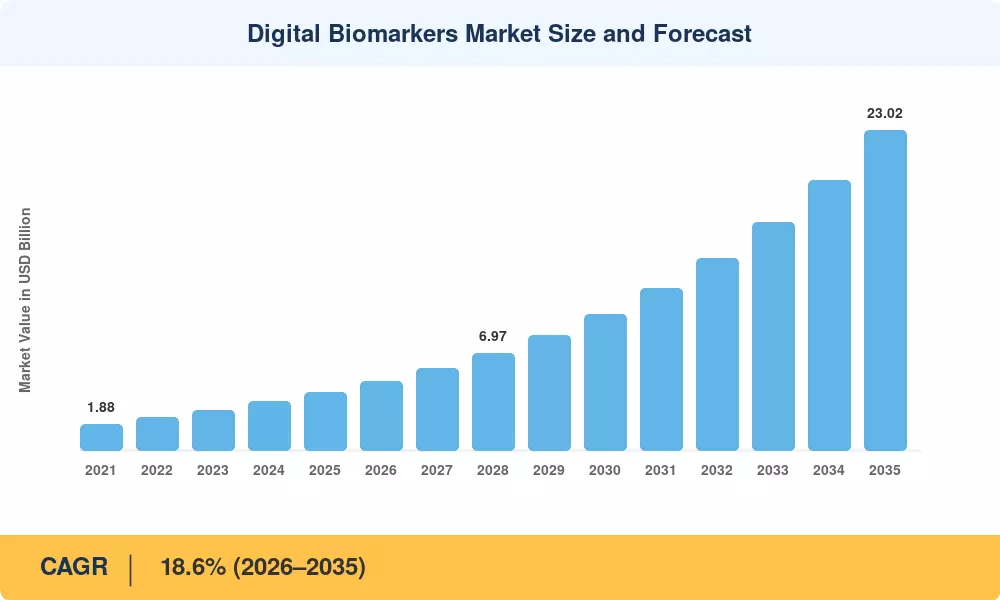
Digital Biomarkers Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Regulatory qualification of sensor endpoints 4.1 North America, Europe Medium-term (2–4 yr)
Decentralized and hybrid clinical trial adoption 3.6 Global Short-term (≤2 yr)
Chronic disease burden and ageing populations 3.0 Europe, Asia-Pacific Long-term (≥4 yr)
Consumer wearable penetration and sensor cost decline 2.7 Global Short-term (≤2 yr)
Value-based care and remote monitoring reimbursement 2.4 North America Medium-term (2–4 yr)
Foundation-model analytics for time-series health data 2.0 North America, Asia-Pacific Long-term (≥4 yr)
National digital health infrastructure programmes 1.6 Asia-Pacific, Middle East Medium-term (2–4 yr)


Regulatory Qualification Turns Measurement into Evidence

Nothing moved this sector faster than the FDA's willingness to treat a sensor output as a fit-for-purpose endpoint. Under the Drug Development Tool qualification programme, stride velocity 95th centile was accepted as a secondary endpoint in Duchenne muscular dystrophy trials, and the agency's 2023 guidance on digital health technologies for remote data acquisition set expectations for verification, validation, and usability evidence [1]. Sponsors read that as permission to invest. The European Medicines Agency's parallel qualification route has processed a comparable pipeline, and MHRA's 2024 innovative devices pathway compressed review timelines by roughly 30% for qualifying submissions [10].

Decentralized Trials Rebuilt the Demand Base

Sponsors spent an estimated USD 2.4 billion on decentralized and hybrid trial infrastructure in 2024, with sensor procurement and data-management services absorbing close to 40% of that outlay [3]. Trial economics explain the persistence: dropout rates fall by 8–12 percentage points when site visits are replaced by home-based capture, and each retained participant in a mid-size Phase III saves roughly USD 40,000 in replacement recruitment cost [4]. Continuous capture also shortens signal detection — a 12-week passive monitoring window can surface treatment effects that a quarterly clinic visit would miss entirely.

Reimbursement Finally Caught Up

Payer behaviour changed the commercial calculus. CMS remote physiologic monitoring codes generated more than USD 1.1 billion in Medicare billings during 2024, up sharply from a negligible base five years earlier [7]. Germany's DiGA fast-track has now listed dozens of prescribable digital applications with statutory reimbursement, and France's PECAN scheme created an equivalent early-access reimbursement corridor in 2024 [11]. When a monitoring workflow becomes billable, provider adoption stops depending on grant funding.

Sensor Economics and Model Capability Converged

Component costs collapsed while analytical capability rose. Photoplethysmography modules that cost roughly USD 12 in 2019 now ship below USD 4 at volume, and inertial measurement units have followed a similar curve [6]. Meanwhile, transformer architectures trained on multi-million-hour accelerometry corpora have improved gait-event classification accuracy to above 94% against laboratory reference systems [8]. Cheap sensing plus credible inference is what makes population-scale deployment defensible.


Restraints Impact Analysis

Restraint impacts are directional drag estimates, scored on the same analyst framework used in Section 4 and equally non-additive. They describe friction that suppresses achievable growth relative to an unconstrained adoption path across the Digital Biomarkers Market.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Clinical validation cost and evidence burden -2.8 Global Medium-term (2–4 yr)
Data privacy, consent, and cross-border transfer rules -2.2 Europe, Asia-Pacific Short-term (≤2 yr)
Interoperability gaps and proprietary data formats -1.9 Global Medium-term (2–4 yr)
Clinician workflow burden and alert fatigue -1.5 North America, Europe Short-term (≤2 yr)
Reimbursement uncertainty outside pilot programmes -1.3 South America, MEA Long-term (≥4 yr)


Validation Costs Deter Second-Tier Entrants

Proving that an algorithm measures what it claims remains expensive. A full analytical and clinical validation package for a single digital endpoint — bench testing, usability studies, and a validation cohort of 200 or more participants — typically runs USD 3–7 Million and 18 to 30 months [12]. Small vendors cannot self-fund that, which pushes them toward licensing deals on unfavourable terms. Consolidation follows.

Privacy Regimes Fragment Deployment

Continuous physiological capture sits squarely inside the most tightly regulated data category in every major jurisdiction. GDPR Article 9 restrictions, China's PIPL localisation requirements, and India's 2023 Digital Personal Data Protection Act each impose distinct consent architecture, forcing vendors to maintain parallel regional stacks [2]. Compliance engineering absorbs an estimated 9–14% of platform development budgets at multinational operators.

Interoperability Remains Unsolved at the Last Mile

Standards exist; adoption lags. Fewer than half of surveyed provider organisations reported the ability to ingest continuous device streams directly into their EHR without a middleware layer, and HL7 FHIR device-resource implementations vary widely between vendors [13]. Every integration project therefore becomes bespoke, inflating deployment cost and lengthening sales cycles by several quarters.


Digital Biomarkers Market Opportunities

Neurodegenerative Disease Endpoint Franchises

Alzheimer's therapeutics created an unmet measurement need that clinic-based cognitive scales cannot fill. Passive speech, typing cadence, and ambulation metrics can detect functional decline months earlier than annual assessments, and regulators have signalled openness to composite digital endpoints in this indication [1]. A vendor that owns a qualified endpoint in this therapeutic area captures royalty-like economics across every sponsor running trials in it.

Emerging-Market Leapfrog Deployments

Health systems in India, Indonesia, Brazil, and Nigeria are building digital infrastructure without a legacy EHR estate to displace. India's Ayushman Bharat Digital Mission has issued over 700 million health account identifiers, creating an addressable substrate for smartphone-based monitoring at costs unachievable in mature systems [9]. Vendors that price for these markets rather than porting Western SKUs will define regional share by 2030.

Data Monetisation and Endpoint-as-a-Service Models

Recurring revenue is displacing hardware margin. Platform operators are licensing curated, consented longitudinal cohorts to pharmaceutical sponsors under subscription contracts, with typical deal values between USD 2 Million and USD 15 Million annually depending on cohort depth [15]. Real-world digital health data assets built once can be resold many times, which is why platform valuations now run at multiples well above device manufacturers.

Payer-Led Population Risk Stratification

Insurers are the most underexploited buyer. Early programmes using continuous monitoring to triage heart-failure and COPD populations have demonstrated 15–22% reductions in 30-day readmissions, translating directly into avoided penalty exposure under value-based contracts [7]. Selling avoided cost rather than clinical novelty shortens the procurement conversation considerably.

Regulatory-Grade Software Toolchains

Every sponsor deploying sensors needs audit trails, version control, and 21 CFR Part 11 compliance for algorithm changes. Few own that capability internally. Suppliers offering validated, pre-qualified toolchains can charge premium rates while reducing sponsor submission risk — a services layer growing faster than the underlying hardware it supports.


Digital Biomarkers Market Future Outlook

Foundation Models Move from Classification to Prediction

Analytical capability will shift from labelling what happened to forecasting what comes next. Time-series foundation models trained on billions of sensor-hours are already achieving clinically useful lead times — atrial fibrillation prediction windows of 24 to 72 hours have been demonstrated in research settings [8]. Predictive framing changes the product entirely, converting monitoring dashboards into intervention triggers and raising the regulatory bar for every vendor in the Digital Biomarkers Market.

Platform Economics Displace Device Margin

Hardware will commoditise. As sensor bills of materials continue falling and consumer devices reach medical-grade specification, defensible value migrates to validated algorithms, regulatory dossiers, and curated cohorts. Expect gross margin dispersion to widen sharply, with platform businesses sustaining 70%+ margins while pure-play device suppliers compress toward contract-manufacturing economics [15].

Endpoint Standardisation and Pre-Competitive Consortia

Fragmentation is expensive for everyone, which is why sponsors are collaborating. The Digital Medicine Society's endpoint library and IMI-funded consortia such as Mobilise-D have produced shared validation frameworks that reduce duplicated effort [19]. Standardised endpoints will do for this sector what harmonised assay methods did for laboratory diagnostics — expand the addressable base while compressing per-unit pricing.

Integration into Routine Care Delivery


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 41.5% share Endpoint qualification, RPM reimbursement, pharma partnerships
Europe USD 1.11 billion EHDS implementation, DiGA-style prescribing, AI Act compliance
Asia-Pacific 21.4% CAGR National digital health missions, smartphone-first deployment
South America USD 0.21 billion Private insurer pilots, urban tertiary hospital digitisation
Middle East & Africa 19.8% CAGR Sovereign health transformation programmes, medical tourism
Total USD 4.18 billion —

Geographic performance across the Digital Biomarkers Market tracks three variables: regulatory clarity, reimbursement availability, and sensor penetration. Regions where all three align are already at scale; those missing reimbursement remain pilot-bound.


North America

Country Metric Key Driver
US 88% of regional revenue FDA qualification pathway and CMS RPM codes
Canada USD 0.13 billion Provincial remote monitoring programmes
Mexico 20.6% CAGR Private hospital chain digitisation


Regulatory precedent gives the United States a structural advantage that pricing alone cannot erode. Medicare remote physiologic monitoring billings exceeded USD 1.1 billion in 2024, and the Advanced Research Projects Agency for Health has committed multi-year funding to sensor-based early-detection programmes [7][16]. Canada's trajectory is slower but steadier, with Ontario and British Columbia both funding heart-failure monitoring at provincial scale.

Europe

Country Metric Key Driver
Germany 24% of regional revenue DiGA statutory reimbursement pathway
UK USD 0.21 billion NICE early value assessment and NHS App integration
France 19.1% CAGR PECAN early-access reimbursement scheme
Italy 9% of regional revenue PNRR digital health allocation
Spain USD 0.07 billion Regional telemonitoring rollouts
Nordic Countries 20.4% CAGR Registry linkage and high device penetration
Russia 3% of regional revenue Domestic platform substitution
Rest of Europe USD 0.11 billion Cross-border research consortia


Europe's advantage is data depth rather than deployment speed. Nordic national registries permit longitudinal linkage that no US dataset can match, and the European Health Data Space framework — with an implementation runway extending through 2029 — will make secondary use of that material routine [2]. Germany remains the commercial bellwether: its DiGA listings established that a software-delivered intervention can be prescribed and reimbursed like a drug.

Asia-Pacific

Country Metric Key Driver
China 38% of regional revenue Smart hospital construction and domestic wearable scale
India 24.8% CAGR Ayushman Bharat Digital Mission identifiers
Japan USD 0.19 billion Ageing population and PMDA SaMD pathway
South Korea 11% of regional revenue K-Bio Vaccine fund and 5G health infrastructure
ASEAN 22.1% CAGR Urban private hospital adoption
Rest of Asia-Pacific USD 0.05 billion Donor-funded rural monitoring pilots


Scale economics favour this region uniquely. China's National Health Commission smart-hospital grading has pushed tertiary facilities toward continuous inpatient monitoring, while domestic device makers supply certified hardware at roughly 40% of Western price points [9]. India's opportunity is different in kind — smartphone-native deployment across a population where dedicated wearables remain aspirational, which is why app-first architectures dominate regional roadmaps.

South America

Country Metric Key Driver
Brazil 62% of regional revenue ANS-regulated private insurer monitoring pilots
Argentina USD 0.03 billion Buenos Aires metropolitan hospital programmes
Rest of South America 19.4% CAGR Chilean and Colombian telehealth expansion


Private payers, not public systems, are funding adoption here. Brazil's supplementary health sector covers roughly 51 million lives and faces medical cost inflation above 12% annually, which makes readmission avoidance a straightforward business case [17]. Public-sector procurement remains constrained by fiscal conditions, so vendors sequence Brazil first and treat public tenders as a later-decade opportunity.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 31% of regional revenue Vision 2030 Health Sector Transformation Program
UAE USD 0.04 billion Malaffi and Riayati health information exchanges
South Africa 18.9% CAGR Private hospital group chronic care programmes
Egypt 8% of regional revenue Universal Health Insurance rollout
Rest of MEA USD 0.03 billion Donor-funded infectious disease surveillance


Sovereign programmes dominate demand. Saudi Arabia's health transformation allocation exceeds USD 65 billion across its programme horizon, with digital infrastructure and virtual care explicitly named as pillars [18]. Sub-Saharan adoption follows a separate logic entirely, where low-cost smartphone monitoring is deployed for maternal health and infectious disease surveillance rather than chronic care.


Digital Biomarkers Market By Region, 2025-2035

Digital Biomarkers Market Segmentation

By Component

Component structure within the Digital Biomarkers Market reflects a sector still buying tools while learning to value analytics.

Segment Metric (2025) Primary Demand Driver
Data Collection Tools 56% share Sensor procurement for trials and remote monitoring
Data Integration & Analytics Platforms 20.3% CAGR Multi-source harmonisation and regulatory-grade pipelines


Collection tools dominate current spend because every deployment starts with hardware. Platform revenue grows faster for the opposite reason. Once a sponsor runs three or more sensor-enabled studies, the marginal cost of another device is trivial while the cost of unharmonised data becomes intolerable. That inflection typically arrives 24 to 36 months after first deployment, which is why platform bookings now lead hardware orders as a growth signal.

By Data Source

Segment Metric (2025) Primary Demand Driver
Wearables 47% share Consumer device penetration and validated wrist sensors
Smartphones & Mobile Apps USD 1.00 billion Zero-hardware deployment in emerging markets
Implantables 21.7% CAGR Cardiac rhythm and neurostimulation telemetry
Ingestibles USD 0.25 billion Adherence verification in psychiatry and TB therapy
Other Sources 8% share Ambient sensing, voice, and connected home devices


Wrist-worn devices carry the segment on installed base alone. Implantables grow faster because the data is uninterrupted and clinically unambiguous — no compliance question, no wear-time gap — which makes them the preferred source for regulatory submissions in cardiology.

By Therapeutic Area

Therapeutic concentration in the Digital Biomarkers Market tracks where measurement is hardest, and stakes are highest.

Segment Metric (2025) Primary Demand Driver
Neurological Disorders USD 1.09 billion Alzheimer's and Parkinson's endpoint qualification
Cardiovascular Disorders 23% share Consumer-scale arrhythmia detection
Diabetes & Metabolic 19.6% CAGR Continuous glucose monitoring ecosystem expansion
Respiratory Diseases 12% share COPD exacerbation prediction
Sleep & Behavioural Health USD 0.46 billion Consumer sleep tracking crossing into clinical use
Oncology 22.8% CAGR Performance status and toxicity monitoring
Other Areas 4% share Rare disease and musculoskeletal applications


Neurology leads because conventional instruments are so poor. A clinician-rated Parkinson's scale administered twice yearly cannot capture fluctuation that varies hour to hour; wrist accelerometry can. Cardiovascular applications hold second position through sheer reach — consumer arrhythmia notifications have screened populations in the tens of millions, generating a referral funnel no clinical programme could replicate.

By Clinical Practice

Segment Metric (2025) Primary Demand Driver
Monitoring Digital Biomarkers 41% share Chronic disease management and post-discharge care
Diagnostic Digital Biomarkers USD 0.92 billion Early detection and triage workflows
Predictive & Prognostic 22.4% CAGR Risk stratification for value-based contracts
Response Digital Biomarkers 12% share Treatment efficacy assessment in trials
Safety & Susceptibility USD 0.25 billion Adverse event detection and pharmacovigilance


By End User

Segment Metric (2025) Primary Demand Driver
Pharmaceutical & Biotech Companies 36% share Endpoint deployment across development portfolios
Healthcare Providers USD 1.38 billion Reimbursed remote monitoring programmes
Payers 20.9% CAGR Population risk stratification and cost avoidance
Healthcare & Research Institutes 12% share Grant-funded validation cohorts
Others USD 0.25 billion Employers, CROs, and wellness intermediaries


Sponsors remain the anchor buyer because trial budgets tolerate premium pricing that provider procurement will not. Payers represent the fastest-growing customer class, and their entry matters disproportionately — when an insurer mandates monitoring, provider adoption follows without a separate sales cycle.


Competitive Benchmarking

Concentration is medium, with an estimated HHI of around 780 and a combined top-five share of nearly 34%. No single provider owns the stack end to end: the sensor layer is owned by consumer platforms, validated algorithms are owned by specialist vendors and data is increasingly owned by pharmaceutical sponsors. That structural bifurcation maintains the Digital Biomarkers Market competitive but is pushing steady acquisition of algorithm specialists by larger platforms.

Company Est. Revenue Share Range Key Offerings for Digital Biomarkers Market Strategic Positioning
Koninklijke Philips N.V. ~8–11% Hospital-grade monitoring, cardiac telemetry, patient platforms Incumbent with provider channel depth
Medtronic plc ~6–9% Implantable cardiac telemetry, CGM, LINQ family Implantable data leadership
Apple Inc. ~5–8% Consumer sensors, HealthKit, ResearchKit ecosystem Largest validated consumer installed base
Biogen Inc. ~4–6% Neurology endpoint programmes, cognitive assessment Sponsor-side endpoint development
Huma Therapeutics ~3–5% Regulated remote monitoring and decentralised trial platform Regulatory-grade platform specialist
Evidation Health ~3–5% Consented person-generated data cohorts, real-world evidence Cohort and evidence marketplace
AliveCor Inc. ~2–4% ECG hardware and arrhythmia algorithms Cleared algorithm portfolio
Koneksa Health ~2–4% Trial-grade endpoint capture and analytics Pharma-focused endpoint services
Biofourmis ~2–4% AI-driven therapeutic monitoring and care-at-home Payer and provider value-based positioning
Empatica Inc. ~1–3% Research wearables, seizure detection, EDA sensing Neurology and research niche leader
ActiGraph LLC ~1–3% Actigraphy devices and validated activity endpoints Reference-standard measurement supplier
IXICO plc ~1–2% Neuroimaging and digital endpoint analytics Neurology trial analytics specialist


Recent News & Developments

  • US FDA (March 2024): Published updated guidance on digital health technologies for remote data acquisition in clinical investigations, clarifying verification and validation expectations for sponsors [1]
  • European Union (March 2025): European Health Data Space regulation entered into force, establishing secondary-use rights for electronic health data across member states with phased implementation to 2029 [2]
  • Medtronic (September 2024): Expanded its LINQ family analytics with AI-based arrhythmia classification, reducing false-positive alert volume by a reported 80%+ [20]
  • Huma Therapeutics (June 2024): Acquired assets of a decentralised trial platform to consolidate regulated remote monitoring capability across European and US markets [21]
  • Evidation Health (November 2023): Announced a multi-year person-generated data partnership with a top-ten pharmaceutical sponsor covering neurology and metabolic programmes [15]
  • Apple (September 2025): Received clearance for a hypertension notification feature, extending consumer sensor output into a new cardiovascular risk category [22]
  • CMS (January 2025): Finalised physician fee schedule updates expanding remote therapeutic monitoring code applicability to additional chronic conditions [7]
  • Mobilise-D Consortium (2024): Published validation results for digital mobility outcomes across four disease cohorts, supporting regulatory qualification submissions in Europe [19]


Digital Biomarkers Market Report Scope

Parameter Detail
Market Scope Global Digital Biomarkers Market by component, data source, therapeutic area, clinical practice, end user, and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 18.6% (2026–2035)
Market Size Checkpoints USD 4.18 billion (2025); USD 4.96 billion (2026); USD 11.64 billion (2031); USD 23.02 billion (2035)
Fastest Growing Segments Data Integration & Analytics Platforms; Implantables; Predictive & Prognostic applications; Payers
Companies Profiled 12 major suppliers across device, platform, analytics, and sponsor categories
Valuation Currency USD billion, end-user value at constant 2025 exchange rates

FAQs

What should procurement teams verify before signing a multi-year vendor contract in the Digital Biomarkers Market?
Demand the analytical and clinical validation dossier for each specific endpoint, not the platform overall. Confirm data portability terms and algorithm version-control commitments in writing [12].
How do consumer-grade wearables compare with medical-grade devices for regulated use?
Consumer devices win on scale and cost but often lack raw-signal access, which regulators increasingly expect. Medical-grade hardware costs five to ten times more yet shortens submission review [1].
Who actually owns the data generated in a sponsored study within the Digital Biomarkers Market?
Ownership depends entirely on the consent architecture and vendor contract. Sponsors typically hold study data; platform vendors often retain rights to de-identified derivative models unless explicitly excluded [15].
What integration obstacle most often delays provider deployments?
Middleware. Fewer than half of provider organisations can ingest continuous device streams natively into their EHR, so each rollout requires custom interface work that adds two to three quarters [13].
Which emerging use case is least covered by current investment?
Perioperative recovery monitoring. Post-surgical complication detection has strong clinical economics but almost no dedicated vendor focus compared with cardiology and neurology [14].
How does the EU AI Act affect vendors operating in the Digital Biomarkers Market?
Most clinical algorithms fall under high-risk classification, requiring conformity assessment, risk management documentation, and post-market monitoring. Compliance overlaps substantially with existing MDR obligations [2].
Is acquisition or partnership the better entry route for a pharmaceutical sponsor?
Partnership suits sponsors running fewer than five sensor-enabled studies annually. Above that threshold, acquisition of an endpoint specialist typically returns better economics within three years [21].      
Author
Author Author Profile Vikita Thakur LinkedIn Senior Research Analyst
She holds an experience of about 5+ years in market research and business consulting projects for sectors such as life sciences, medical devices, and healthcare IT. She possesses a robust background in data analysis, market estimation, competitive intelligence, pipeline analysis market trend identification, and consumer behavior insights. Her expertise lies in technical Sales support, client interaction and project management, designing and implementing market research studies, conducting competitive analysis, and synthesizing complex data into actionable recommendations that drive business growth.
Co-Author Co-Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical journals, clinical publications, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA) Digital Health Center of Excellence, European Medicines Agency (EMA) Digital Health Unit, National Institutes of Health (NIH) National Center for Biotechnology Information (NCBI/PubMed), World Health Organization (WHO) Global Digital Health Observatory, US Department of Health & Human Services (HHS) Office of the National Coordinator for Health Information Technology (ONC), Centers for Disease Control and Prevention (CDC) National Center for Health Statistics, US National Library of Medicine (NLM) ClinicalTrials.gov, European Commission Digital Health and Care Policy, Health Canada Medical Devices Directorate, UK National Institute for Health and Care Excellence (NICE), Australia Therapeutic Goods Administration (TGA), Japan Pharmaceuticals and Medical Devices Agency (PMDA), Digital Medicine Society (DiMe), International Medical Device Regulators Forum (IMDRF), Institute of Electrical and Electronics Engineers (IEEE) Standards Association, and national digital health strategies from key markets. These sources were used to collect regulatory approval data for wearable devices and mobile health applications, clinical validation studies for digital endpoints, digital biomarker qualification pathways, adoption statistics across therapeutic areas, technology penetration metrics, and competitive landscape analysis for physiological monitoring, behavioral data analytics, genetic data integration, and psychological assessment platforms.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. Chief Executive Officers, Chief Technology Officers, Heads of Digital Health Innovation, regulatory affairs directors, and commercial strategy leads from digital biomarker platform developers, wearable device manufacturers, mobile health application providers, and pharmaceutical companies that integrate digital endpoints comprised supply-side sources. Chief medical informatics officers, clinical trial investigators, digital therapeutics medical directors, payer innovation executives, and procurement leads from academic medical centers, contract research organizations (CROs), health insurance providers, and biotechnology firms comprised demand-side sources. Primary research has confirmed the product pipeline timelines for AI-integrated analytics platforms, validated market segmentation across chronic disease management, mental health monitoring, personalized medicine applications, drug development applications, and clinical trial deployment, and gathered insights on clinical adoption patterns, data interoperability standards, pricing strategies for software-as-a-service models, and reimbursement dynamics for remote patient monitoring.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through revenue mapping and deployment volume analysis. The methodology included:

Identification of 55+ key technology providers and platform developers across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Product mapping across wearable devices, mobile health applications, remote patient monitoring systems, and telehealth-integrated platforms

Technology segmentation covering physiological data sensors, behavioral data analytics, psychological assessment tools, and genetic data integration platforms

Analysis of reported and modeled annual revenues specific to digital biomarker portfolios and digital health solution suites

Coverage of technology developers and pharmaceutical integrators representing 75-80% of global market share in 2024

Extrapolation using bottom-up (deployment volume × ASP by therapeutic area and end-user segment) and top-down (manufacturer revenue validation, enterprise software licensing models, and pharmaceutical partnership valuations) approaches to derive segment-specific valuations across chronic disease management, mental health monitoring, drug development, and clinical trial applications

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















