Custom Antibody Market Summary
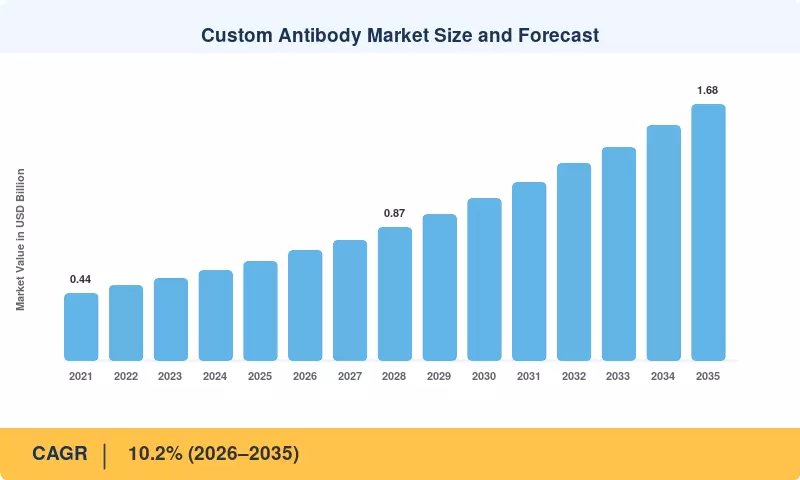
The Custom Antibody Market reached USD 0.65 billion in 2025 and opens the forecast window at USD 0.72 billion in 2026, advancing to USD 1.68 billion by 2035 at a 10.2% CAGR. Two catalysts anchor that trajectory. The first is the sustained expansion of antibody-drug conjugate pipelines, where more than 200 candidates are in active clinical development and each program consumes multiple bespoke reagent campaigns. The second is public funding: the U.S. National Institutes of Health obligated roughly USD 47 billion in extramural research awards in FY2024, a large share of which flows into immunoassay-dependent discovery work that purchases reagents rather than making them in house [1][3].
Hybridoma-derived supply is steadily giving way to sequence-defined production. Legacy immunization-and-fusion workflows carry lot-to-lot drift, clone loss, and 16–20 week timelines; engineered display libraries, cell-free expression, and AI-assisted binder design compress that to six to ten weeks with reproducible sequence records. The FairJourney Biologics acquisition, valued near USD 1 billion, signalled how sharply discovery capacity has been repriced, and roughly one-quarter of newly approved antibody therapeutics now use multispecific architectures that hybridoma routes cannot deliver [4][7].
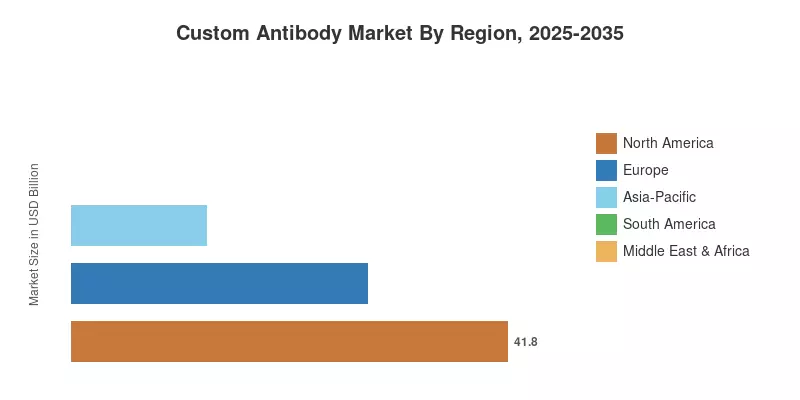
North America holds 41.8% of the Custom Antibody Market on the strength of its academic and biopharma installed base. Asia-Pacific grows fastest at 12.9% CAGR as Chinese, Indian, and South Korean contract providers scale gram-level output at materially lower unit cost. Europe ranks second at 28.4%, supported by EMA-aligned quality systems and a dense diagnostics manufacturing base. Buyer behaviour over the next decade will hinge less on price per milligram and more on data provenance, sequence ownership, and reagent reproducibility.
Key Report Takeaways
• By Antibody Type
- Monoclonal antibodies held 50.1% of the Custom Antibody Market in 2025, sustained by validated clinical and diagnostic use cases
- Recombinant antibodies post the fastest expansion at 14.5% CAGR through 2035, driven by sequence-defined reproducibility
- Polyclonal antibodies retain relevance in signal-amplification diagnostics, contributing USD 0.17 billion in 2025
• By Service
- Antibody development services captured 38.4% of 2025 revenue as buyers consolidate vendors
- Antibody fragmentation and labeling grows at 15.9% CAGR, the fastest service line
- Antibody production and purification generated USD 0.19 billion in 2025 on toxicology-scale demand
• By Application
- Oncology led with 33.2% share, anchored by conjugate and checkpoint follow-on programs
- Stem cell research expands at 14.8% CAGR as conditioning antibodies enter the clinic
• By End User
- Pharmaceutical and biotechnology companies accounted for 60.1% of demand
- Contract research organisations grow at 13.1% CAGR as sponsors outsource discovery
• By Region
- North America leads the Custom Antibody Market with 41.8% share
- Asia-Pacific is the fastest-growing region at 12.9% CAGR
Market Size and Forecast (2021–2035)
Figures below combine bottom-up vendor revenue mapping across roughly 140 reagent and service providers with top-down validation against biopharma R&D expenditure, NIH and Horizon Europe grant flows, and customs data on reagent trade. Historical years are reconciled against audited filings where available; forecast years apply a segment-weighted growth model calibrated to the 2025 base.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


