Content Intelligence Market (2026 - 2035)

Content Intelligence Market Size, Share and Research Report By Component (Solution, Services), By Deployment Mode (Cloud, On-Premise, Hybrid), By Organization Size (SMEs, Large Enterprises) and By Regional (North America, Europe, Asia Pacific, Rest of the World) - Industry Forecast to 2035.
ID: MRFR/ICT/6910-HCR 100 Pages Apoorva Priyadarshi, Aarti Dhapte Last Updated: August 24, 2026
Content Intelligence Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)31.22%
2025 Market SizeUSD 2.17 Billion
2035 Market SizeUSD 27.48 Billion
Key Players
Adobe Inc.
OpenText Corporation
Ceralytics
Contently
Conductor
PathFactory
Opportunities
  • Generative AI for Multilingual Content Scaling
  • Content Intelligence in Regulated Verticals
  • Outcome-Based Pricing Models

Content Intelligence Market Summary

The Content Intelligence Market stood at USD 2.17 billion in 2025, with the forecast period opening at USD 2.82 billion in 2026 and climbing to USD 27.48 billion by 2035 at a 31.22% CAGR. As content libraries across sectors now reach petabyte scale, enterprises are investing heavily in AI-powered content tagging and classification. Government requirements for digital accessibility, particularly the WCAG 3.0 compliance deadlines in the United States and European Union, have provided a regulatory floor for adoption. These catalysts have helped make spending on content performance intelligence platforms resilient to macroeconomic instability. A generational technology change is taking place, replacing outdated content management systems based on static taxonomies with adaptive, AI-native architectures. NLP for content personalization engines now does real-time audience segmentation, sentiment scoring, and dynamic asset assembly — activities that manual editing workflows can't match at scale. At the forefront of this change are Adobe's GenStudio platform and OpenText's Titanium X suite, with combined corporate commitments that surpass USD 3 billion through 2027 [1]. Automated content audit and gap analysis were once costly add-ons. Now they are table stakes features built into every major platform.

North America commands roughly 40.50% of Content Intelligence Market revenue, anchored by Silicon Valley innovation clusters and Fortune 500 martech budgets. Asia-Pacific registers the fastest expansion at a 36.72% CAGR, propelled by a creator economy valued at over USD 140 billion and rapid digitization across India, China, and Southeast Asia. Europe holds the second-largest share at approximately 27.30%, where GDPR-driven demand for privacy-compliant content intelligence for SEO optimization continues to fuel platform adoption. The decade ahead will reward vendors that balance scalability with data sovereignty.

Key Report Takeaways

• By Component

  • Solutions accounted for 68.20% of Content Intelligence Market revenue in 2025, driven by demand for integrated AI-powered content tagging and classification modules
  • Services are expanding at a 35.87% CAGR through 2035 as enterprises pair platforms with consulting and workflow redesign

• By Deployment

  • Cloud deployment captured 82.40% share in 2025 within the Content Intelligence Market, reflecting SaaS-first procurement preferences
  • Hybrid architectures are growing fastest at a 39.02% CAGR, fueled by data-sovereignty mandates and edge-inference needs

• By Geography

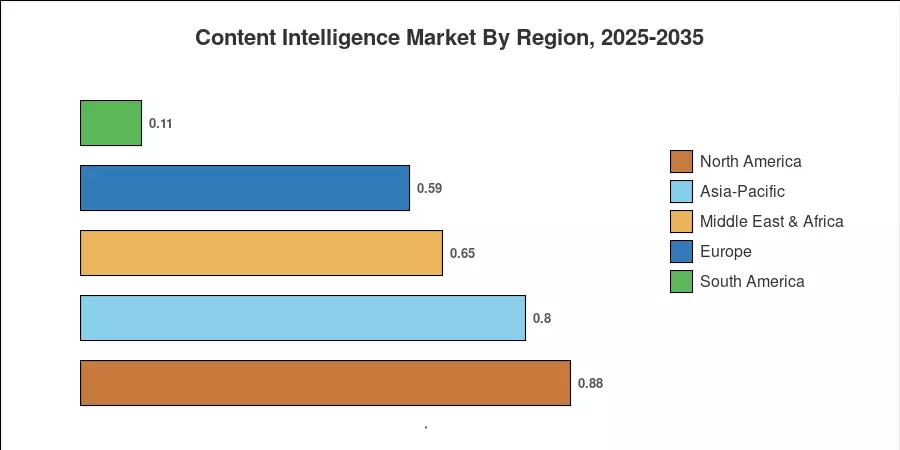
  • North America generated USD 0.88 billion in 2025 Content Intelligence Market revenue, led by US enterprise spending
  • Asia-Pacific holds the fastest CAGR of 36.72%, reflecting surging adoption of NLP for content personalization engines across media and e-commerce
  • Europe's share sits near 27.30%, sustained by regulatory compliance cycles and multilingual content demands

MRFR's sizing methodology triangulates vendor revenues, enterprise IT spending surveys, and bottom-up demand modeling across six end-user verticals and five geographic regions. Historical figures (2021–2024) use reported financials; forecast values (2026–2035) apply the calibrated 31.22% CAGR with adjustments for segment-specific acceleration and deceleration factors.
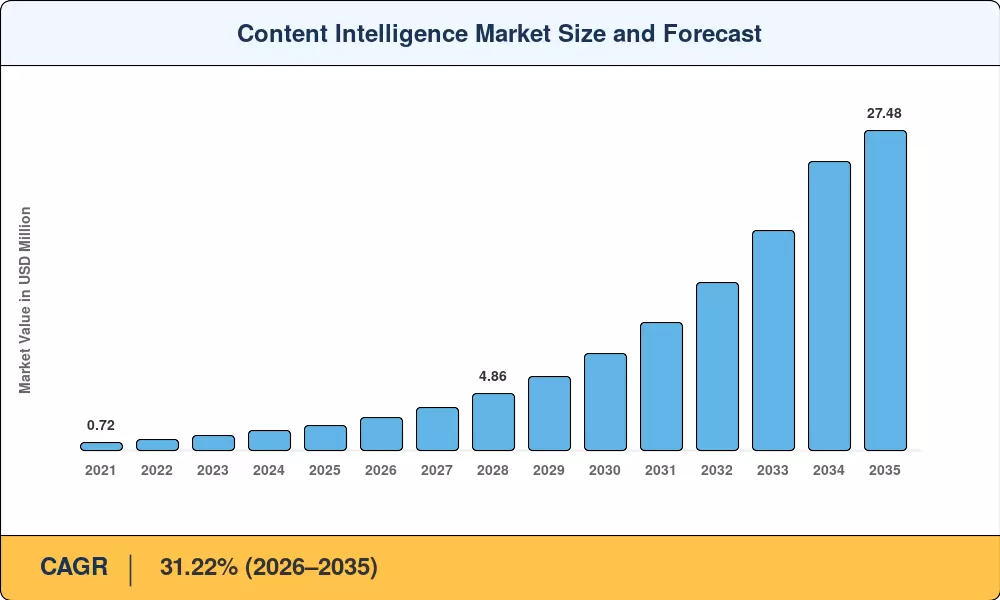
Content Intelligence Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Demand for personalized, data-driven content at scale +8.5% Global, led by North America and EU Medium term (2–4 yr)
AI/ML integration across martech stacks +8.1% Global, APAC spillover to MEA Short term (≤2 yr)
Omnichannel video and social content explosion +6.8% APAC core, expanding to North America Medium term (2–4 yr)
WCAG 3.0 accessibility mandates +4.4% North America, EU, global spillover Long term (≥4 yr)
Small language models reducing inference costs +6.0% Global, enterprise-heavy in developed markets Short term (≤2 yr)
Synthetic audience data and zero-party targeting +4.2% North America, EU, emerging APAC Medium term (2–4 yr)

Personalized Content Demand at Scale

Enterprises that deploy AI-powered content tagging and classification report 40–70% faster content creation cycles and measurably higher engagement scores [1]. Financial services firms using the Content Intelligence Market's personalization tools have documented 28% increases in click-through rates on regulatory-compliant communications. Adobe's Customer Experience Orchestration platform demonstrated engagement lifts of up to 30% for dynamically assembled banner variants in 2024, validating the ROI case for NLP for content personalization engines across verticals [1].

AI/ML Integration Across Martech Stacks

Generative AI has moved from being an experimental element to basic infrastructure within content performance intelligence platforms. OpenText's Titanium X incorporates more than 100 AI agents and 15 specialized aviators, delivering USD 1 billion in cumulative savings to enterprise customers over a decade [2]. Consolidation pressure is forcing legacy vendors to build in automated content audit and gap analysis or risk being displaced by AI-native competitors. The budget allocation has moved from one-time licenses to ongoing model tuning, agent orchestration and data-ops spending.

Omnichannel Content Explosion

Short-form video, live commerce, and interactive media increase the number of content variants per campaign, creating demand for clip-level optimization and thumbnail production at scale. Asia-Pacific's creative economy, worth around USD 140 billion with over 210 million contributors, needs AI-assisted localization and format adaptation [3]. Generative in Adobe Premiere Pro 1. Adapt features cut timescales up to 80%, proving that content intelligence for SEO optimization goes beyond text to multimedia.

WCAG 3.0 Accessibility Regulations

In the United States, accessibility regulations will go into force in June 2025, requiring conformance with WCAG 2.1 Level AA, while the outcome-based testing framework of WCAG 3.0 is on the regulatory horizon [4]. Content Intelligence with built-in accessibility modules. Market systems can cut remediation costs by 60-80% against manual audits. Vendors that build real-time scoring for color contrast, alt-text quality, and navigation patterns into their products have a persistent competitive edge as compliance deadlines ripple around the world.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
GDPR/DMA compliance costs –4.6% EU core, global regulatory spillover Long term (≥4 yr)
Content-AI talent shortage –3.9% Global, acute in developed markets Medium term (2–4 yr)
GPU/ASIC supply-chain bottlenecks –3.0% Global, manufacturing concentrated in APAC Short term (≤2 yr)
Hallucination-driven brand liability –2.3% Global, regulatory focus in NA and EU Medium term (2–4 yr)
Integration complexity with legacy CMS –1.8% Global, concentrated in large enterprises Medium term (2–4 yr)

Data-Privacy Compliance Costs

OpenAI's EUR 15 million GDPR penalties in 2025 highlight the financial exposure that organizations incur when using AI-driven content technologies [7]. Indeed, the European Data Protection Board guidance now calls for clear justification of all personal-data use in training, inference, and monitoring pipelines. Content Intelligence Market players need to invest in privacy-preserving designs and synthetic data pipelines, which add 25-40% to the total cost of ownership and expand procurement cycles in regulated sectors.

Content-AI Talent Shortage

Many organizations [8] have a limited pool of specialists with a mix of AI experience, content strategy, and governance understanding that adds 6–12 months to project deadlines. Creative teams sometimes reject automation that they view as frightening, leading to change management friction. Successful content performance intelligence platforms implementations combine incremental automation rollouts with upskilling initiatives, but vendor-managed services only go so far in bridging the gap. This shortfall represents a medium-term headwind to the Content Intelligence Market's realized expansion.

Content Intelligence Market Opportunities

Generative AI for Multilingual Content Scaling

Enterprises expanding into non-English markets face a content localization bottleneck that NLP for content personalization engines can address. Real-time translation combined with cultural-context adaptation opens addressable markets worth over USD 4 billion by 2030, particularly across APAC and Latin America

Content Intelligence in Regulated Verticals

Healthcare and life sciences firms need compliant, auditable content workflows—from patient communications to clinical trial documentation. Automated content audit and gap analysis tools with embedded regulatory guardrails are high-margin expansion opportunities within the Content Intelligence Market

Outcome-Based Pricing Models

As vendors move from per-seat licensing to performance-linked pricing — where payments are tied to verifiable engagement lifts or conversion gains — this can expedite SME adoption. This commercial innovation connects vendor incentives with buyer objectives, and widens the addressable Content Intelligence Market across price-sensitive groups

Emerging Market Digitization in Africa and Southeast Asia

The rising mobile-first internet penetration in Sub-Saharan Africa and ASEAN countries is generating greenfield demand for AI-based content tagging and classification. Governments can access new commercial and public sector buyer pools by investing in digital infrastructure programs

Data Monetization Through Content Analytics

Organizations with proprietary content performance data might monetize insights by offering anonymised benchmarking services. Content Intelligence for SEO optimization creates competitive intelligence data sets that publishers and advertisers will pay to see, generating recurring revenue streams beyond basic platform subscriptions.

Content Intelligence Market Future Outlook

Agentic AI and Autonomous Content Operations

Content workflows will move from human-directed automation to fully autonomous agent orchestration by 2030. Human touchpoints will be reduced to strategic oversight and brand governance by AI agents capable of ideation, creation, compliance review, and publication. The Content Intelligence Market will see platform architectures evolve from tool suites to agent ecosystems, with vendors competing on orchestration sophistication and auditability.

Platform Economics and Ecosystem Lock-In

Winner-take-most dynamics are speeding up as top content performance intelligence platforms combine development, distribution, analytics, and monetisation into holistic ecosystems. As the data accumulates, the model is fine-tuned, and the workflow is tailored, with switching costs rising. Vendors using open APIs and interoperability standards could carve out defensible nooks and crannies against monolithic incumbents.

Sustainability and ESG Content Reporting

Corporate sustainability disclosure standards – such as the EU's CSRD and the SEC's climate reporting rules – produce huge volumes of structured content. Automated content audit and gap analysis solutions configured for ESG frameworks are a high-growth adjacency for the Content Intelligence Market. Deloitte projects that sustainability reporting content will triple by 2030.

Hyper-Personalization Through Synthetic and Zero-Party Data

As third-party cookies are being phased out and privacy restrictions tighten, AI-powered tagging and classification of first-party and zero-party data is the foundation of personalized strategy. Brands can create synthetic audiences to replicate consumer categories without having to process personal data, overcoming the privacy-personalization issue. This capability will drive the next growth wave throughout the Content Intelligence Market to 2035 [20].

Content Intelligence Market Segmentation

By Component (Solution, Service)

Segment Key Metric Primary Demand Driver
Solution 68.20% of 2025 revenue Integrated AI-powered content tagging and classification suites
Service 35.87% CAGR (2026–2035) Consulting, implementation, and managed optimization

The Content Intelligence Market's Solution segment retains dominance as enterprises consolidate point tools into unified platforms that combine content creation, NLP for content personalization engines, and performance analytics. Commoditization of baseline AI features, however, compresses margins and pushes vendors toward vertical-specific differentiation.

Services are the growth engine. Organizations pairing software with managed services report 20–30% higher adoption rates and faster time-to-value. Subscription-based service models now anchor vendor revenue strategies, particularly for content intelligence for SEO optimization engagements where continuous tuning is essential.

By Deployment (Cloud, On-Premise, Hybrid)

Segment Key Metric Primary Demand Driver
Cloud 82.40% of 2025 revenue SaaS scalability and lower upfront investment
On-Premise USD 0.15 Billion (2025) Defense, healthcare, and classified content workflows
Hybrid 39.02% CAGR (2026–2035) Data sovereignty with elastic scaling

Cloud deployment dominates the Content Intelligence Market as consumption-based pricing eliminates capital barriers for SMEs and mid-market buyers. Hybrid configurations, however, post the steepest growth as multinational enterprises split sensitive data onto local clusters while routing burst workloads through public clouds. Small, domain-tuned language models that perform efficiently on CPU cores make local inference increasingly practical, further accelerating hybrid adoption for automated content audit and gap analysis at the edge.

By Organization Size (SMEs, Large Enterprises)

Segment Key Metric Primary Demand Driver
SMEs 63.10% of 2025 revenue Affordable SaaS plans and pre-built workflows
Large Enterprises USD 0.80 Billion (2025) Complex compliance and multi-brand orchestration

SMEs drive the Content Intelligence Market's volume growth because consumption-based plans let lean teams access enterprise-grade AI-powered content tagging and classification. For many small businesses, automated captioning, image generation, and editorial quality checks are competitive necessities rather than luxuries. Large enterprises bring substantial budgets but face longer procurement cycles due to compliance review and cross-departmental coordination requirements.

By End-User Vertical

Segment Key Metric Primary Demand Driver
Media and Entertainment 27.70% of 2025 revenue Content volume management and audience targeting
Government and Public Sector 30.50% CAGR (2026–2035) Digital accessibility mandates and citizen engagement
Healthcare and Life Sciences 34.72% CAGR (2026–2035) Regulatory content compliance and patient communication
BFSI USD 0.31 Billion (2025) Personalized financial communications
Retail and E-Commerce 33.20% CAGR (2026–2035) Omnichannel product content and dynamic merchandising

Media and Entertainment anchors the Content Intelligence Market's vertical mix, as publishers and studios require content performance intelligence platforms to manage thousands of daily assets across streaming, social, and web properties. Healthcare and Life Sciences registers the fastest growth, driven by compliance-heavy workflows where NLP for content personalization engines must navigate regulatory guardrails while delivering patient-centric communications.

Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 40.50% of 2025 revenue Enterprise martech consolidation; WCAG compliance
Europe 27.30% of 2025 revenue GDPR-compliant personalization; multilingual scaling
Asia-Pacific 36.72% CAGR (2026–2035) Creator economy; mobile-first content
South America USD 0.11 Billion (2025) Digital transformation in media and retail
Middle East & Africa 29.85% CAGR (2026–2035) Government digitization; e-commerce growth
Total USD 2.17 Billion (2025)

North America and Europe are the major geographical concentrations for the Content Intelligence Market, with Asia-Pacific not far behind. The most established global economies are the heaviest adopters of NLP for content personalization engines, whereas emerging areas are focusing on AI-powered content tagging and classification for foundational content operations.

North America

Country Key Metric Key Driver
US 82.10% of regional revenue Fortune 500 martech spend; content performance intelligence platforms
Canada 10.30% of regional revenue Bilingual content mandates; media sector growth
Mexico 33.50% CAGR Nearshoring-driven digital infrastructure investment

North America's dominance in the Content Intelligence Market reflects deep enterprise budgets, mature SaaS ecosystems, and early regulatory pressure from WCAG timelines. US-based companies allocate an estimated 12–15% of their martech budgets to content intelligence capabilities, with financial services and healthcare leading vertical adoption.

Europe

Country Key Metric Key Driver
Germany 21.40% of regional revenue Industrial content automation; Industrie 4.0 alignment
UK 19.80% of regional revenue Publishing and media sector digitization
France 14.60% of regional revenue Public-sector digital accessibility mandates
Italy 8.50% of regional revenue SME adoption through EU-funded digitization grants
Spain 7.20% of regional revenue Tourism and hospitality content personalization
Nordic Countries 33.90% CAGR Sustainability reporting and ESG content requirements
Russia 2.80% of regional revenue Domestic platform development amid sanctions
Rest of Europe 12.70% of regional revenue Cross-border e-commerce content localization

European adoption of automated content audit and gap analysis tools accelerates under twin pressures: GDPR compliance costs and the EU Accessibility Act's 2025 enforcement deadlines. Multilingual content demands across 24 official EU languages make NLP for content personalization engines indispensable for brands operating across borders [13].

Asia-Pacific

Country Key Metric Key Driver
China 31.20% of regional revenue Domestic AI ecosystem; ByteDance and Alibaba platforms
India 38.40% CAGR Digital India initiative; vernacular content explosion
Japan 18.50% of regional revenue Enterprise digital transformation; aging workforce automation
South Korea 12.90% of regional revenue K-content global export optimization
ASEAN 35.60% CAGR Mobile-first economies; social commerce growth
Rest of Asia-Pacific 8.40% of regional revenue Emerging digital infrastructure investments

Asia-Pacific's trajectory in the Content Intelligence Market is powered by the region's creator economy and mobile-dominant internet usage. India's vernacular web — with over 500 million non-English internet users — creates massive demand for AI-powered content tagging and classification in regional languages [14].

South America

Country Key Metric Key Driver
Brazil 58.30% of regional revenue Media industry modernization; fintech content needs
Argentina 22.10% of regional revenue Digital advertising growth; startup ecosystem
Rest of South America 31.80% CAGR E-commerce expansion and government digitization

Brazil's expanding digital advertising sector drives demand for content performance intelligence platforms, particularly among media conglomerates and fintech firms scaling personalized communications to over 150 million digital banking users [15].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 28.40% of regional revenue Vision 2030 digital transformation programs
UAE 24.60% of regional revenue Smart city and tourism content initiatives
South Africa 18.70% of regional revenue Financial services and media digitization
Egypt 32.10% CAGR Youth demographics and mobile internet adoption
Rest of MEA 16.30% of regional revenue Government e-services and education content

Saudi Arabia's Vision 2030 allocates significant budgets to digital content infrastructure, creating procurement opportunities for Content Intelligence Market vendors that offer Arabic-language NLP for content personalization engines and localized deployment models [16].

Content Intelligence Market By Region, 2025-2035

Competitive Benchmarking

The Content Intelligence Market exhibits medium concentration, with the top five vendors commanding an estimated 35–42% combined revenue share. An approximate Herfindahl-Hirschman Index (HHI) of 650–800 confirms a moderately fragmented structure where specialized AI-native entrants compete alongside enterprise software incumbents. M&A activity accelerated through 2024–2025 as legacy CMS providers acquired content intelligence capabilities to avoid displacement.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Adobe Inc. 8–11% Experience Cloud, GenStudio, Firefly Full-stack martech leader with generative AI integration
OpenText Corporation 6–9% Titanium X, AI Aviators, Content Cloud Enterprise content management with AI agent orchestration
Ceralytics 2–4% Content scoring, gap analysis, ROI attribution Pure-play content performance intelligence platforms
Contently 2–4% Content strategy, creator network, analytics Content-as-a-service with talent marketplace
Conductor 3–5% Organic marketing, SEO intelligence Content intelligence for SEO optimization specialist
PathFactory 2–4% Content engagement, journey acceleration B2B content experience and AI-powered content tagging and classification
Acrolinx 2–4% Content governance, style automation Linguistic AI for enterprise tone and compliance
Knotch 1–3% Content intelligence dashboard, audience insights Real-time content performance benchmarking
Siteimprove 2–4% Accessibility, SEO, content quality Accessibility-first content intelligence platform
Veritone 2–4% aiWare, media asset management, analytics AI operating system for media and government content

Recent News & Developments

  • Adobe (March 2025): Launched GenStudio 2.0 with expanded AI agent capabilities for real-time A/B testing and automated brand governance across channels [1].
  • OpenText (January 2025): Released the Titanium X platform, integrating over 100 AI agents and promising enterprise clients measurable cost reductions of up to 40% in content operations [2].
  • Siteimprove (September 2024): Expanded its accessibility compliance suite to cover WCAG 3.0 draft criteria, targeting early adopters ahead of regulatory enforcement [4].
  • US Department of Justice (June 2025): Finalized Title II ADA rules mandating WCAG 2.1 Level AA for state and local government web content, accelerating demand for automated content audit and gap analysis [4].
  • PathFactory (August 2024): Introduced AI-driven content journey mapping for B2B buyers, integrating NLP for content personalization engines with intent-data signals [22].
  • Veritone (May 2024): Expanded aiWare platform to support government and defense content workflows, securing FedRAMP authorization for classified content environments [23].
  • European Commission (April 2025): Published updated guidance under the European Accessibility Act, requiring member states to enforce digital content standards by June 2025 [13].

Content Intelligence Market Report Scope

Parameter Detail
Market Scope Content Intelligence Market — global, segmented by Component, Deployment, Organization Size, End-User Vertical, and Geography
Study Period 2021–2035
CAGR (Forecast Period) 31.22% (2026–2035)
Market Size (2025) USD 2.17 Billion
Market Size (2035) USD 27.48 Billion
Fastest Growing Segment Hybrid Deployment (39.02% CAGR); Healthcare and Life Sciences (34.72% CAGR)
Companies Profiled Adobe, OpenText, Ceralytics, Contently, Conductor, PathFactory, Acrolinx, Knotch, Siteimprove, Veritone
Valuation Currency USD Billion

FAQs

How should procurement teams evaluate content intelligence vendor lock-in risk?
Assess API openness, data portability guarantees, and contract exit clauses before committing. Vendors offering open-standard integrations and documented export formats reduce long-term switching costs significantly [18].
What distinguishes AI-native content intelligence platforms from retrofitted CMS solutions?
AI-native platforms build models into their core architecture rather than layering them onto legacy databases. This structural difference delivers faster inference, tighter feedback loops, and lower maintenance overhead [11].
How does the Content Intelligence Market address multilingual content at scale?
Leading platforms combine neural machine translation with cultural-context adaptation to produce localized assets in real time. This capability is critical for brands operating across Asia-Pacific's diverse linguistic landscape [14].
What ROI benchmarks exist for Content Intelligence Market deployments?
Organizations typically report 40–70% faster creation cycles and 20–30% higher engagement within the first year. Financial services and healthcare verticals document the strongest measurable returns [1].
How do small language models reshape the Content Intelligence Market economics?
Domain-tuned small models run on standard CPU infrastructure, cutting inference costs by 50–70% versus large-model alternatives. This shift makes on-premise and hybrid deployment practical for mid-market buyers [5].
What compliance frameworks most heavily influence Content Intelligence Market purchasing?
GDPR, the EU Accessibility Act, and US ADA Title II rules create mandatory procurement triggers. Organizations in regulated verticals treat compliance-ready platforms as non-negotiable requirements [7].
How will agentic AI change the Content Intelligence Market by 2030?
Autonomous AI agents will handle end-to-end content workflows from ideation through publication with minimal human intervention. Vendors competing on agent orchestration depth and audit transparency will capture premium positioning [17].                
Author
Author
Author Profile
Apoorva Priyadarshi LinkedIn Research Analyst
With 4+ years of experience in Market Intelligence and Strategic Research, Apoorv specializes in ICT, Semiconductor, and BFSI markets. Combining strong analytical capabilities with a deep understanding of technology-driven industries, he focuses on delivering data-driven insights that support strategic decision-making. With a background in technology and business research, Apoorv has contributed to numerous global market studies, competitive landscape analyses, and opportunity assessments across sectors such as semiconductors, digital banking, cybersecurity, and telecommunications.
Co-Author
Co-Author Profile
Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















