Coating Pretreatment Market (2026 - 2035)

ID: MRFR/CnM/1239-CR 111 Pages Chitranshi Jaiswal Last Updated: October 29, 2026
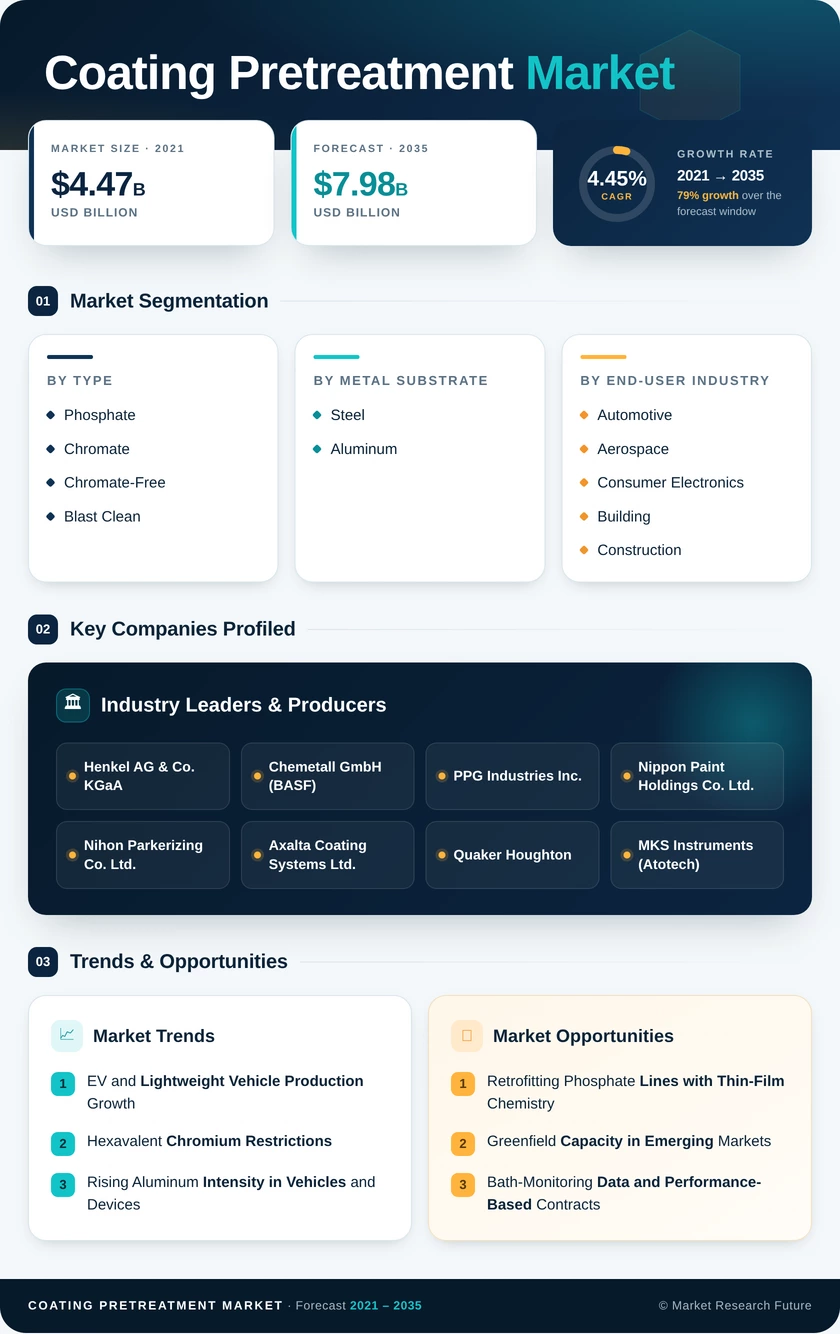
Coating Pretreatment Market Research Report Information By Type (Phosphate, Chromate, Chromate-Free, and Blast Clean), By Metal Substrate (Steel and Aluminum), By End-User Industry (Automotive, Aerospace, Consumer Electronics, Building and Construction, and Other End-User Industries (Industrial Machinery and Appliances, etc.)), And By Region (North America, Europe, Asia-Pacific, and Rest of the World) – Market Forecast Till 2035.
Coating Pretreatment Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.45%
2025 Market SizeUSD 5.16 Billion
2035 Market SizeUSD 7.98 Billion
Key Players
Henkel AG & Co. KGaA
Chemetall GmbH
PPG Industries Inc.
Nippon Paint Holdings Co. Ltd.
Nihon Parkerizing Co. Ltd.
Axalta Coating Systems Ltd.
Opportunities
  • Retrofitting Phosphate Lines with Thin-Film Chemistry
  • Greenfield Capacity in Emerging Markets
  • Bath-Monitoring Data and Performance-Based Contracts
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Type | |
    2. 2.2 By Metal Substrate | |
    3. 2.3 By End-User Industry | |
    4. 2.4 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Market Size (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 EV and Lightweight Vehicle Production Growth | |
    2. 4.2 Hexavalent Chromium Restrictions | |
    3. 4.3 Rising Aluminum Intensity in Vehicles and Devices | |
    4. 4.4 Infrastructure and Construction Spending | |
    5. 4.5 Manufacturing Localization in India and Southeast Asia | |
    6. 4.6 Commercial Aerospace Fleet Expansion | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Raw Material Price Volatility | |
    2. 5.2 Wastewater and Sludge Compliance Costs | |
    3. 5.3 Long Qualification Cycles for Chromium-Free Aerospace Systems | |
    4. 5.4 China Property-Sector Slowdown | |
    5. 5.5 Elevated Energy Costs for Heated Immersion Lines | |
  6. 6 Opportunities | |
    1. 6.1 Retrofitting Phosphate Lines with Thin-Film Chemistry | |
    2. 6.2 Greenfield Capacity in Emerging Markets | |
    3. 6.3 Bath-Monitoring Data and Performance-Based Contracts | |
    4. 6.4 EV Battery Enclosures and Aluminum Structures | |
    5. 6.5 Chromium-Free Sealers for Aerospace and Defence | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 Asia-Pacific | | |
      1. 7.1.1 China | | |
      2. 7.1.2 Japan | | |
      3. 7.1.3 India | | |
      4. 7.1.4 South Korea | | |
      5. 7.1.5 ASEAN Countries | | |
      6. 7.1.6 Rest of Asia-Pacific | |
    2. 7.2 North America | | |
      1. 7.2.1 United States | | |
      2. 7.2.2 Canada | | |
      3. 7.2.3 Mexico | |
    3. 7.3 Europe | | |
      1. 7.3.1 Germany | | |
      2. 7.3.2 United Kingdom | | |
      3. 7.3.3 France | | |
      4. 7.3.4 Italy | | |
      5. 7.3.5 Spain | | |
      6. 7.3.6 Russia | | |
      7. 7.3.7 NORDIC Countries | | |
      8. 7.3.8 Rest of Europe | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 South Africa | | |
      3. 7.5.3 Rest of Middle East and Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Automated Bath Control and Digital Line Management | |
    2. 8.2 Electrified Vehicle Platforms Reshape Substrate Demand | |
    3. 8.3 Regulatory Convergence Toward Chromium- and Nickel-Free Chemistry | |
    4. 8.4 Sustainability Reporting and Low-Energy Processing | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Type | | |
      1. 9.1.1 Phosphate | | |
      2. 9.1.2 Chromate | | |
      3. 9.1.3 Chromate-Free | | |
      4. 9.1.4 Blast Clean | |
    2. 9.2 By Metal Substrate | | |
      1. 9.2.1 Steel | | |
      2. 9.2.2 Aluminum | |
    3. 9.3 By End-User Industry | | |
      1. 9.3.1 Automotive | | |
      2. 9.3.2 Aerospace | | |
      3. 9.3.3 Consumer Electronics | | |
      4. 9.3.4 Building and Construction | | |
      5. 9.3.5 Other End-user Industries (Industrial Machinery and Appliances, etc.) | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Henkel AG & Co. KGaA | | |
      2. 10.3.2 Chemetall GmbH (BASF) | | |
      3. 10.3.3 PPG Industries Inc. | | |
      4. 10.3.4 Nippon Paint Holdings Co. Ltd. | | |
      5. 10.3.5 Nihon Parkerizing Co. Ltd. | | |
      6. 10.3.6 The Sherwin-Williams Company | | |
      7. 10.3.7 Axalta Coating Systems Ltd. | | |
      8. 10.3.8 Quaker Houghton | | |
      9. 10.3.9 MKS Instruments (Atotech) | | |
      10. 10.3.10 Element Solutions Inc. (MacDermid Enthone) | | |
      11. 10.3.11 Kansai Paint Co. Ltd. | |
  11. 11 Recent News and Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Market Snapshot, 2025–2035 | |
  16. TABLE 2 Global Market Size and Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Restraints Impact Analysis, 2026–2035 | |
  19. TABLE 5 Regional Summary, by Region, 2025 | |
  20. TABLE 6 Asia-Pacific Market, by Country, 2025 | |
  21. TABLE 7 North America Market, by Country, 2025 | |
  22. TABLE 8 Europe Market, by Country, 2025 | |
  23. TABLE 9 South America Market, by Country, 2025 | |
  24. TABLE 10 Middle East and Africa Market, by Country, 2025 | |
  25. TABLE 11 Global Market, by Type, 2025 | |
  26. TABLE 12 Global Market, by Metal Substrate, 2025 | |
  27. TABLE 13 Global Market, by End-User Industry, 2025 | |
  28. TABLE 14 Competitive Benchmarking Matrix, 2025 | |
  29. TABLE 15 Report Scope and Methodology | |
  30. TABLE 16 Detailed Sources and Citations | |
  31. TABLE 17 Segmentation Quick Reference | | LIST OF FIGURES | |
  32. FIGURE 1 Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  33. FIGURE 2 Industry Value Chain Analysis | |
  34. FIGURE 3 Porter's Five Forces Analysis | |
  35. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  36. FIGURE 5 Market Share by Type, 2025 | |
  37. FIGURE 6 Market Share by Metal Substrate, 2025 | |
  38. FIGURE 7 Market Share by End-User Industry, 2025 | |
  39. FIGURE 8 Regional Market Share, 2025 | |
  40. FIGURE 9 Country-Level Share within Each Region, 2025 | |
  41. FIGURE 10 Competitive Landscape and Estimated Revenue Share Ranges, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TypePhosphate; Chromate; Chromate-Free; Blast CleanPhosphate (48.6% share)Chromate-Free (5.95% CAGR)
By Metal SubstrateSteel; AluminumSteel (63.8% share)Aluminum (5.71% CAGR)
By End-User IndustryAutomotive; Aerospace; Consumer Electronics; Building and Construction; Other End-user Industries (Industrial Machinery and Appliances, etc.)Automotive (38.2% share)Consumer Electronics (5.63% CAGR)
By RegionAsia-Pacific; North America; Europe; South America; Middle East and AfricaAsia-Pacific (44.8% share)Asia-Pacific (44.8% share)

Market Segmentation Overview

By Type

Sub-SegmentKey Trend
PhosphateRetains OEM approvals but faces nickel and sludge pressure
ChromateDeclining under Cr(VI) restrictions outside qualified aerospace uses
Chromate-FreeSilane and zirconium-silane hybrids gain new-line specifications
Blast CleanStable demand in heavy fabrication and structural steel

Phosphate leads by type because zinc phosphate remains the approved base for most automotive steel bodies and its performance is proven across decades of warranty data. Chromate-Free grows fastest as restriction proposals in Europe and emission rules in the United States make trivalent, zirconium and silane chemistries the safer long-term choice. Chromate shrinks steadily, while Blast Clean holds its niche where mechanical profiling precedes thick protective coatings.

By Metal Substrate

Sub-SegmentKey Trend
SteelGalvanized and press-hardened grades dominate vehicle bodies and appliances
AluminumRising use in EV enclosures, closures and device housings

Steel leads because passenger-cell structures, appliance cabinets and structural sections still rely on galvanized and press-hardened grades. Aluminum grows faster as EV makers adopt extruded and cast battery enclosures and electronics brands favour aluminum housings. That shift favours non-etch cleaners and zirconium or sol-gel layers over traditional zinc phosphate.

By End-User Industry

Sub-SegmentKey Trend
AutomotiveEV body shops specify chromium- and nickel-free chemistry
AerospaceChromium-free sealer qualification on major airframes
Consumer ElectronicsCosmetic-grade treatments for aluminum and magnesium housings
Building and ConstructionCoil-coated roofing and architectural aluminum profiles
Other End-user Industries (Industrial Machinery and Appliances, etc.)Hybrid zirconium systems balancing cost and durability

Automotive leads end-user demand because vehicle volumes and long anti-perforation warranties require consistent, high-performance base layers on every body. Consumer Electronics grows fastest as premium devices demand flawless finishes on aluminum and magnesium frames using chromium-free, low-VOC chemistry. Aerospace adds high value per litre, while Building and Construction and Other End-user Industries (Industrial Machinery and Appliances, etc.) contribute steady, price-sensitive volume.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.