Castor Oil Market (2026 - 2035)

Castor Oil Market Size, Share, Industry Trend & Analysis Research Report By Product Type (Crude Castor Oil, Hydrogenated Castor Oil, Dehydrated Castor Oil, Jamaican Black Castor Oil, Others), By End-User (Chemical Industry, Pharmaceuticals, Cosmetics and Personal Care, Food and Beverages, Others), By Geography (North America, Europe, Asia-Pacific, South America, Middle East and Africa) - Forecast to 2035

Forecast Period
2026-2035
CAGR
5.6%
2025 Market Size
USD 2.57 Billion
2035 Market Size
USD 4.43 Billion
Consumer and Retail ● Updated August 27, 2026 Report ID: MRFR/CG/20647-HCR | Pages: 100 | Author: Priya Nagrale

Castor Oil Market Summary

The castor oil market reached USD 2.57 Billion in 2025 and opens the forecast window at USD 2.71 Billion in 2026, climbing to USD 4.43 Billion by 2035 at a 5.6% CAGR. Two catalysts anchor that trajectory. The European Union's renewable carbon push under the Sustainable Carbon Cycles framework rewards non-food agricultural feedstocks, while India's Ministry of Commerce continues to route roughly 85% of global castor seed output through Gujarat's export corridor, giving the castor oil market a supply base no competing oleochemical crop can match. [1][2]

Reformulation, not novelty, is doing the heavy lifting. Petrochemical polyols, mineral-base greases, and synthetic emollients are giving way to castor-derived chemistry because the molecule's hydroxyl group delivers performance parity without a fossil input. Arkema's Rilsan polyamide-11 line, backed by a EUR 300 million capacity program, is the clearest signal that downstream buyers will pay for renewable carbon content rather than merely tolerate it. [3][11]

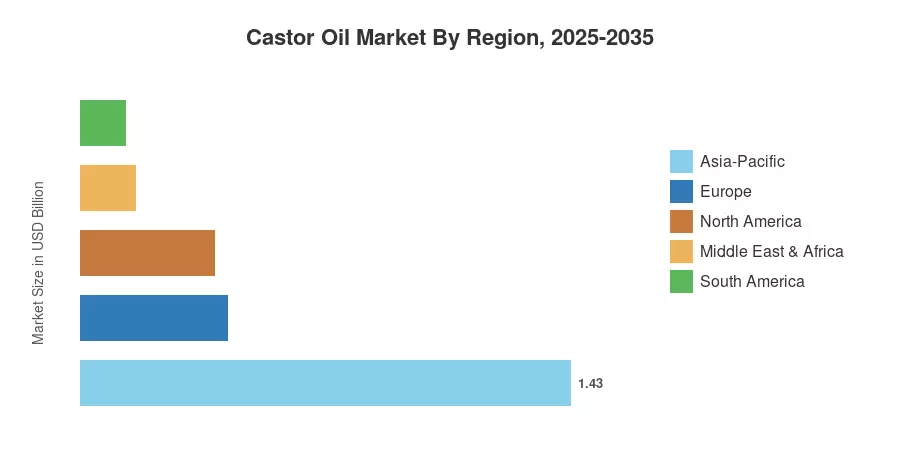
Asia-Pacific holds 55.6% of the castor oil market, a position built on crush capacity rather than consumption alone. Middle East & Africa grows fastest at a 6.3% CAGR as Ethiopian and Tanzanian cultivation pilots mature, and Europe follows Asia-Pacific with USD 0.43 Billion in 2025 demand concentrated in Germany and Italy. Expect origin diversification to become the defining strategic question of the next decade. [4][14]


Key Report Takeaways

• By Product Type

  • Crude castor oil commands 41.2% of the castor oil market in 2025, sustained by refiners who prefer to control downstream fractionation in-house.
  • Jamaican Black castor oil advances at an 8.0% CAGR through 2035, the fastest of any product grade.
  • Hydrogenated castor oil generates USD 0.63 Billion in 2025 revenue on grease and coatings demand.

• By End-User

  • The chemical industry accounts for 29.4% of castor oil market revenue, the single largest consuming vertical.
  • Cosmetics and personal care expands at a 7.2% CAGR as clean-label reformulation accelerates.
  • Pharmaceuticals contribute USD 0.48 Billion in 2025, led by excipient and softgel applications.

• By Region

  • Asia-Pacific holds a 55.6% share, anchored by Gujarat's crushing cluster.
  • Middle East & Africa posts a 6.3% CAGR, the highest regional growth rate.
  • North America generates USD 0.39 Billion in 2025 demand.


Market Size and Forecast (2021–2035)

Figures below blend customs-level trade data from India's Directorate General of Commercial Intelligence and Statistics, crush-capacity audits across the top 30 processors, and end-user consumption surveys covering 140 formulators. Volumes were reconciled against FAO production statistics before conversion to value at annual average realizations.
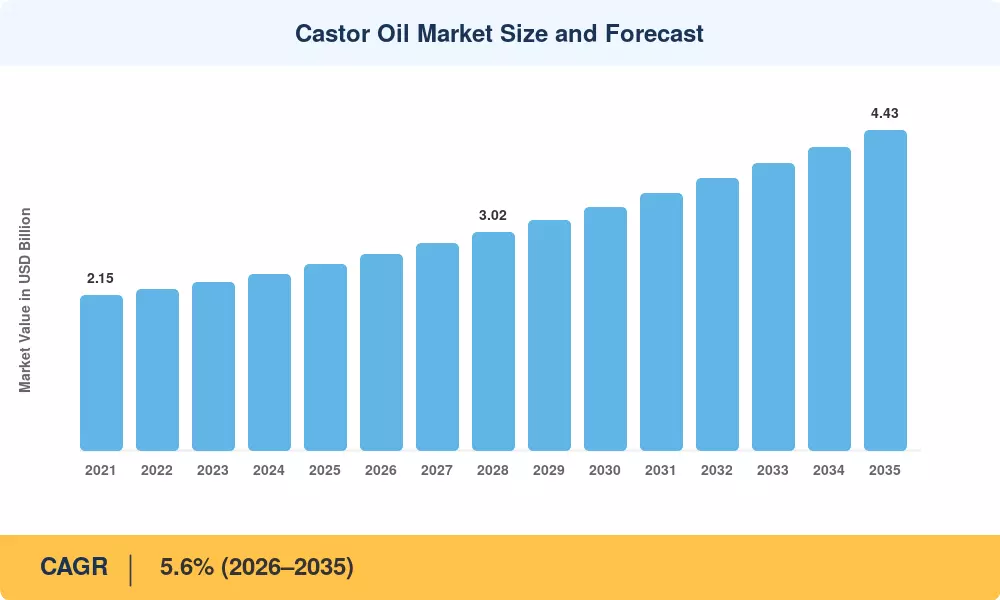
Castor Oil Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Bio-based chemical substitution mandates +1.1 pp EU, North America Long-term (≥4 yr)
Clean-label cosmetics reformulation +0.9 pp North America, Europe Medium-term (2–4 yr)
Electric-vehicle fluid and grease demand +0.7 pp Asia-Pacific, Europe Long-term (≥4 yr)
India export-supply consolidation +0.6 pp Asia-Pacific Short-term (≤2 yr)
Pharmaceutical excipient growth +0.5 pp Global Medium-term (2–4 yr)
African cultivation programs +0.4 pp Middle East & Africa Long-term (≥4 yr)
Sustainable aviation fuel feedstock trials +0.3 pp Europe, North America Long-term (≥4 yr)


Renewable Carbon Policy Is Repricing Feedstock Choice

Calculus was altered by Brussels. Formulators are encouraged to record renewable carbon content at the molecule level rather than the product level by the EU Chemicals Strategy for Sustainability and the EUR 1.1 billion Horizon Europe grant to bio-based companies. Because castor's 12-hydroxy functionality endures conversion into polyols, polyamides, and bio-based lubricants without the need for extra petrochemical inputs, this documentation requirement benefits castor. The feedstock is increasingly being specified by compliance officials rather than procurement teams. [1] [3]


4.2 Cosmetics Reformulation Under a Clearer U.S. Rulebook

The tax on natural oils used for personal care was once a source of regulatory difficulty. This uncertainty was eliminated by the FDA's Modernization of Cosmetics Regulation Act, which was implemented gradually through 2025 and replaced it with clear facility registration and safety substantiation procedures. In response, formulators reported that a castor derivative was present in the top five ingredients of nearly 18% of new lip and hair launches in North America in 2025, compared to roughly 11% three years prior. The majority of such change was captured by premium hydrogenated and Jamaican Black grades. [7] [8]


Electrification Rewrites Lubricant Specifications

Electric drivetrains run hotter, quieter, and with tighter dielectric tolerances than combustion units, which invalidates decades of mineral-base grease qualification data. Castor-derived 12-hydroxystearic thickeners hold dropping points above 260°C and resist the copper corrosion that plagues e-axle bearings. Volkswagen Group and Hyundai both opened supplier qualification tracks for renewable-base e-fluids during 2024, with commercial volumes expected from 2027. Each qualified platform locks in roughly seven years of specified demand. [11][17]

Excipient Demand Follows Injectable and Softgel Growth

Polyoxyl-35 castor oil remains the solubilizer of record for several taxane and immunosuppressant formulations, and USP-grade demand tracks injectable oncology volumes closely. The U.S. Pharmacopeia's 2024 excipient monograph revisions tightened peroxide-value limits, which pushed procurement toward the four suppliers holding cGMP-audited refining assets. Scarcity at that quality tier, not aggregate supply, sets pricing in the pharmaceutical channel. [9][10]


Restraints Impact Analysis

Restraint weightings are directional drags applied to the base-case growth path of the castor oil market. They reflect probability-weighted downside scenarios rather than deterministic subtractions, and several are partially offset by the drivers catalogued above.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Monsoon-linked yield volatility −0.8 pp Asia-Pacific Short-term (≤2 yr)
Seed price pass-through and margin compression −0.6 pp Global Medium-term (2–4 yr)
Single-origin supply concentration −0.5 pp Global Long-term (≥4 yr)
Substitution by palm and rapeseed derivatives −0.4 pp Asia-Pacific, Europe Long-term (≥4 yr)
Ricin residue handling and worker-safety compliance −0.3 pp Global Medium-term (2–4 yr)


One Monsoon, One Market

A single rainfall anomaly immediately affects global prices because the vast bulk of castor seed produced worldwide comes from Gujarat's Saurashtra area. In just four months, the 2023 deficient monsoon increased seed quotations at Deesa Mandi by almost 22%, which was mostly absorbed by refiners before being passed on. Purchasers with annual fixed-price contracts suffered, whereas those with quarterly indexation did not. At the processing level, weather insurance products are still scarce. [2] [5]


Concentration Cuts Both Ways

Correlation is guaranteed by the same geography that ensures availability. When Indian yields fall short, there is no significant counter-cyclical origin since Brazilian and Chinese acreage together account for a small single-digit portion of global output. Programs in Tanzania and Ethiopia will be beneficial, but under present planting plans, their combined contribution will remain below 5% of the world's supply before 2030. Until then, diversification is more of a goal than a hedge. [4] [14]


Compliance Costs at the Crush Stage

Residual ricin in press cake requires detoxification, controlled disposal, and documented worker exposure limits. European importers increasingly demand third-party audits of these controls, and smaller Indian crushers face capital costs of USD 1.5–3 million to reach that standard. Consolidation is the predictable outcome, and it removes low-cost marginal capacity from the market. [13]


Castor Oil Market Opportunities

Certified Traceable Supply Chains

Farm-level certification converts a commodity into a differentiated input. Programs pairing satellite plot verification with digital payment records already command 8–14% price premiums for cosmetics-grade volumes, and the EU Deforestation Regulation's due-diligence architecture gives that infrastructure a second use. Processors who built traceability for compliance can monetize it as a product attribute. [15]

African Origin Development

Ethiopia, Tanzania, and Mozambique offer agronomic conditions comparable to Gujarat with a fraction of the land cost. The African Development Bank's agro-industrial processing zone financing has already committed to oilseed corridors, and early castor bean processing ventures are targeting export-grade crude rather than local consumption. First-mover offtake agreements signed before 2028 will define regional pricing for a decade. [14]

Polyamide-11 and Engineering Polymers

Automotive fuel lines, flexible offshore pipe, and 3D-printing powders all consume undecylenic acid derived from castor. Each tonne of polyamide-11 pulls roughly three tonnes of castor oil upstream, which makes polymer capacity announcements the most reliable forward indicator available to the castor oil market. [3]

Data-Backed Yield Services as a Revenue Line

Processors sitting on a decade of plot-level yield, weather, and procurement data can sell agronomic advisory and forward-price hedging back to their own grower networks. Jayant Agro's cultivation programs already demonstrate the retention benefit; the monetization step is the unexploited part. Subscription agronomy converts procurement cost into service margin. [16]

Pharmaceutical-Grade Capacity Expansion

Fewer than a dozen facilities worldwide hold both cGMP certification and castor refining capability. Adding a qualified line costs roughly USD 20–35 million and takes 30 months, but commands margins several multiples above industrial grades. The bottleneck is regulatory, which is precisely why it persists. [9]


Castor Oil Market Future Outlook

Renewable Carbon Accounting Becomes Auditable

Voluntary claims are giving way to measured ones. ISO 14067 product carbon footprint methodology and the EU's Green Claims Directive together mean that a "bio-based" label without an auditable mass-balance trail becomes a liability by 2027. Suppliers with certified chain-of-custody will capture a disproportionate share of the castor oil market as compliance departments gain veto power over sourcing. [1][15]

Aviation Fuel Optionality

The IEA projects sustainable aviation fuel demand exceeding 20 Mt annually by 2035 under its announced-pledges scenario, and non-food oilseeds sit high in feedstock preference hierarchies precisely because they avoid food-versus-fuel scrutiny. Castor will not be a primary SAF feedstock at that scale, but even marginal offtake tightens a market this size. [12]

Vertical Integration Reshapes Margin Distribution

Processors are buying downstream, and farmers are being contracted upstream. The consequence is fewer arm's-length trades and thinner spot liquidity, which raises volatility for buyers without term contracts. Expect the merchant trading layer to shrink meaningfully by 2030 as integrated players internalize what intermediaries once handled. [16]

Climate Adaptation as Competitive Advantage

IRENA and World Bank analyses both flag Gujarat as facing increased rainfall variability through mid-century. Drought-tolerant cultivar deployment, drip irrigation subsidies, and origin diversification are therefore not sustainability gestures but supply-security investments. Companies treating them as the latter will source more reliably than those treating them as the former. [19][20]


Castor Oil Market Segmentation

By Product Type

Product-grade choice within the castor oil market reflects how much conversion the buyer intends to perform internally.

Segment Metric (2025) Primary Demand Driver
Crude Castor Oil 41.2% share Downstream refiners controlling fractionation
Hydrogenated Castor Oil USD 0.63 Billion Greases, waxes, coatings
Dehydrated Castor Oil 17.9% share Alkyd resins and paints
Jamaican Black Castor Oil 8.0% CAGR Premium hair and skin care
Others USD 0.21 Billion Niche industrial formulations


Crude dominates because integrated chemical producers prefer to buy the base molecule and control every conversion step themselves, protecting both margin and formulation IP. Jamaican Black, by contrast, grows fastest from a small base: the roasted-and-ashed processing method carries authentic provenance that textured-hair brands can market, and consumers demonstrably pay for it. The two segments barely compete — one sells on specification, the other on story.

By End-User

End-user mix determines price elasticity across the castor oil market, and it varies more than most commodity oils.

Segment Metric (2025) Primary Demand Driver
Chemical Industry 29.4% share Polyols, polyamides, sebacic acid
Cosmetics & Personal Care 7.2% CAGR Clean-label reformulation
Pharmaceuticals USD 0.48 Billion Excipients and solubilizers
Food & Beverages 14.7% share Additives and packaging coatings
Others USD 0.39 Billion Textiles, paper, agriculture


Chemical industry buyers set the floor price because they purchase in volume against annual contracts and will substitute when spreads justify it. Cosmetics buyers set the ceiling: they purchase small volumes at quality specifications the industrial channel never requires, and their growth reflects genuine reformulation rather than cyclical restocking. Pharmaceutical demand behaves independently of both, tracking injectable drug volumes with almost no price sensitivity given excipient cost is trivial relative to API value.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 15.2% share Clean-label cosmetics, pharma excipients
Europe USD 0.43 Billion Renewable polymers, REACH-compliant derivatives
Asia-Pacific 55.6% share Crush capacity, vertical integration
South America 5.1% CAGR Biodiesel co-products, Cerrado acreage
Middle East & Africa 6.3% CAGR Cultivation corridors, processing zones
Total USD 2.57 Billion

Regional dynamics in the castor oil market separate cleanly into production geographies and consumption geographies, and the two rarely overlap. Asia-Pacific dominates on crush capacity; Europe and North America dominate on value capture per tonne.


North America

Country Metric Key Driver
US 71.4% of region Cosmetics and pharmaceutical formulation
Canada USD 0.06 Billion Industrial coatings and adhesives
Mexico 6.4% CAGR Personal-care contract manufacturing


American demand is quality-led rather than volume-led. Post-MoCRA safety substantiation requirements pushed brand owners toward suppliers who can document peroxide values, heavy-metal limits, and origin in a single dossier, and that documentation burden has consolidated purchasing among four importers handling most cosmetics-grade volume. Mexican contract manufacturers serving U.S. brands are the growth story here. [7][8]

Europe

Country Metric Key Driver
Germany 23.8% of region Polyamide and polyurethane chemistry
UK USD 0.06 Billion Personal care and pharmaceutical excipients
France 5.9% CAGR Renewable polymer capacity
Italy 10.4% of region Coatings and textile auxiliaries
Spain USD 0.03 Billion Lubricant additives
Nordic Countries 5.4% CAGR Bio-based specialty chemicals
Russia 6.1% of region Industrial greases
Rest of Europe USD 0.05 Billion Diversified industrial demand


Germany anchors the region because its polymer and coatings clusters convert imported crude into high-value derivatives domestically. REACH registration costs deter opportunistic importers, which stabilizes supplier relationships and lengthens contract tenors relative to Asia. French capacity additions in renewable polyamides represent the most concrete European demand increment through 2030. [3][6]

Asia-Pacific

Country Metric Key Driver
China 24.6% of region Derivative chemistry and downstream conversion
India USD 0.61 Billion Seed production and export crushing
Japan 5.1% CAGR Specialty lubricants and electronics chemicals
South Korea 6.2% of region Cosmetics manufacturing
ASEAN USD 0.14 Billion Personal care and food applications
Rest of Asia-Pacific 5.8% CAGR Industrial and agricultural uses


India supplies the raw material; China converts it. That division explains why Indian value capture has lagged its volume share for years and why the Solvent Extractors' Association has pushed derivative-linked export incentives since 2023. Vertical integration by Gujarat processors into sebacic acid and hydrogenated grades is beginning to close the gap, though Chinese conversion capacity remains substantially larger. [2][6]

South America

Country Metric Key Driver
Brazil 58.3% of region Cerrado cultivation and biodiesel programs
Argentina USD 0.04 Billion Industrial lubricants
Rest of South America 5.2% CAGR Agricultural and coatings demand


Brazilian ambitions have outrun Brazilian acreage for two decades. EMBRAPA's improved cultivars raise yields meaningfully, but castor competes for land against soy and sugarcane at unfavorable gross margins, so expansion depends on guaranteed offtake rather than agronomy. Regional biodiesel blending policy remains the swing variable. [18]

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 18.2% of region Industrial lubricants and specialty chemicals
UAE USD 0.02 Billion Re-export trade and personal care
South Africa 6.9% CAGR Cultivation programs and coatings
Egypt 14.6% of region Pharmaceutical and cosmetics manufacturing
Rest of MEA USD 0.07 Billion Emerging cultivation corridors


Africa is where the castor oil market's supply-side story gets rewritten or does not. Ethiopian smallholder programs backed by development finance have proven agronomic viability; what remains unproven is aggregation logistics at export scale. Success here would give global buyers their first genuine alternative origin. [14][19]


Castor Oil Market By Region, 2025-2035

Competitive Benchmarking

Concentration in the castor oil market sits in the medium band, with an estimated HHI near 640 and top-five suppliers holding roughly 33–38% of global revenue. Indian processors dominate crushing volume while European and Japanese specialty chemical firms dominate derivative value. Fragmentation persists at the crushing tier and is disappearing at the pharmaceutical-grade tier.

Company Est. Revenue Share Range Key Offerings for Castor Oil Market Strategic Positioning
Jayant Agro-Organics ~9–12% Crude, hydrogenated, derivatives Largest integrated Indian processor
Adani Wilmar ~6–9% Crude and refined grades Distribution scale and origination
NK Proteins ~5–8% Commercial and pharma grades Export-focused crushing
Gokul Agro Resources ~4–7% Crude, refined, meal Capacity expansion in Gujarat
Thai Castor Oil Industries ~4–6% Refined and specialty grades Southeast Asian supply hub
Casda Biomaterials ~3–5% Sebacic acid, derivatives China's leading converter
Arkema SA ~3–5% Polyamide-11, specialty polymers Premium renewable polymer chemistry
Hokoku Corporation ~2–4% Hydrogenated and specialty grades Japanese quality specialization
Itoh Oil Chemicals ~2–4% Derivatives and esters Technical formulation depth
Kanak Castor Products ~2–3% Crude and refined oil Mid-tier export supplier
BASF SE ~1–3% Castor-based polyols Downstream formulation integration


Recent News & Developments

  • Jayant Agro-Organics (March 2024): Commissioned expanded derivative capacity in Gujarat, deepening integration beyond crude crushing and lifting captive conversion volumes. [16]
  • U.S. FDA (July 2024): Completed phased implementation guidance under the Modernization of Cosmetics Regulation Act, clarifying safety substantiation for natural oil ingredients. [7]
  • Arkema (October 2024): Confirmed additional polyamide-11 capacity in Asia, reinforcing structural demand for castor-derived undecylenic acid. [3]
  • Gokul Agro Resources (January 2025): Announced refining capacity additions targeting pharmaceutical and cosmetic grade output for export markets. [17]
  • African Development Bank (April 2025): Approved agro-industrial processing zone financing covering oilseed corridors in East Africa. [14]
  • European Commission (June 2025): Advanced Green Claims Directive negotiations, tightening substantiation requirements for bio-based product marketing. [1]
  • Solvent Extractors' Association of India (September 2025): Published revised crop estimates following above-normal Saurashtra rainfall, easing near-term seed price expectations. [2]
  • Casda Biomaterials (November 2025): Expanded sebacic acid output to serve engineering polymer and lubricant additive customers. [6]


Castor Oil Market Report Scope

Parameter Detail
Market Scope Global castor oil market by product type, end-user, and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.6% (2026–2035)
Market Size Checkpoints USD 2.57 Billion (2025); USD 2.71 Billion (2026); USD 4.43 Billion (2035)
Fastest Growing Segments Jamaican Black castor oil (product type); Cosmetics & Personal Care (end-user); Middle East & Africa (geography)
Companies Profiled 11 leading suppliers and converters
Valuation Currency USD Billion

FAQs

What contract structures protect buyers from seed price volatility in the castor oil market?
Quarterly-indexed contracts tied to Deesa mandi seed quotations transfer less risk to buyers than annual fixed-price agreements. Large formulators increasingly pair indexation with volume floors to keep supplier commitment intact. [5]
How should procurement teams audit a supplier's pharmaceutical-grade capability?
Request the cGMP certificate, the most recent regulatory inspection report, and peroxide-value batch records covering twelve months. Facilities lacking all three should be treated as industrial-grade suppliers regardless of marketing claims. [9]
Which certification schemes carry real commercial weight in the castor oil market?
Farm-level traceability programs with satellite plot verification and third-party audit command genuine premiums. Self-declared sustainability claims without chain-of-custody documentation increasingly fail European buyers' due diligence. [15]
Is castor meal a liability or a revenue stream for processors?
Detoxified meal sells as organic fertilizer and supports processor margins, but untreated cake carries disposal cost and regulatory exposure. The detoxification investment determines which side of the ledger it lands on. [13]
What lead times should buyers expect when qualifying a new castor oil market supplier?
Industrial grades qualify in roughly eight to twelve weeks. Cosmetics grades take four to six months, and pharmaceutical excipients routinely require eighteen months, including stability testing. [10]
Do castor derivatives face patent barriers for new entrants?
Base chemistry is long off-patent, but specific polyamide-11 grades and proprietary ester formulations remain protected. New converters typically enter through commodity derivatives before attempting specialty positions. [3]
How does currency exposure affect castor oil market buyers outside India?
Most contracts price in USD while underlying seed costs move with the rupee, creating a hidden basis risk. Buyers with rupee-denominated hedges have historically outperformed those hedging USD alone. [5]    
Author
Author
Author Profile
Priya Nagrale LinkedIn Senior Research Analyst
With an experience of over five years in market research industry (Chemicals & Materials domain), I gather and analyze market data from diverse sources to produce results, which are then presented back to a client. Also, provide recommendations based on the findings. As a Senior Research Analyst, I perform quality checks (QC) for market estimations, QC for reports, and handle queries and work extensively on client customizations. Also, handle the responsibilities of client proposals, report planning, report finalization, and execution

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, agricultural commodity reports, peer-reviewed scientific journals, chemical industry publications, and authoritative trade organizations. Key sources included the United States Department of Agriculture (USDA), Food and Drug Administration (FDA), European Chemicals Agency (ECHA), International Castor Oil Association (ICOA), Solvent Extractors' Association of India (SEA), Food and Agriculture Organization (FAO) of the United Nations, USDA Foreign Agricultural Service (FAS) Global Agricultural Information Network, National Institute of Oilseed Products (NIOP), International Organization for Standardization (ISO) technical committees for oleochemicals, India's Ministry of Agriculture & Farmers Welfare, Brazilian Institute of Geography and Statistics (IBGE) agricultural data, China National Chemical Information Center, OECD-FAO Agricultural Outlook, World Bank Commodity Markets, and national agricultural statistics bureaus from key producing regions. These sources were used to collect cultivation statistics, export/import trade data, regulatory compliance standards, price trend analysis, and market landscape assessment for technical grade, pharmaceutical grade, and cosmetic grade castor oil across liquid, semi-solid, and solid forms.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, managing directors, chiefs of oilseed processing, procurement leaders from castor oil refiners, and commercial directors from agro-processing firms were examples of supply-side sources. R&D leaders from pharmaceutical businesses, cosmetic formulators, procurement managers from lubricant companies, purchasers from the paint and coatings sector, and sustainability executives from biofuel producers were examples of demand-side suppliers. In addition to confirming capacity expansion timelines and gathering information on formulation adoption patterns, pricing volatility, and sustainable sourcing dynamics, primary research validated market segmentation across pharmaceuticals, personal care and cosmetics, lubricants, paints and coatings, and food and beverage applications.

Primary Respondent Breakdown:

By Designation: C-level Primaries (30%), Director Level (32%), Others (38%)

By Region: North America (28%), Europe (30%), Asia-Pacific (35%), Rest of World (7%)


Market Size Estimation

Global market valuation was derived through production volume mapping and revenue analysis across the value chain. The methodology included:

Identification of 50+ key processors and refiners across India, China, Brazil, Europe, and North America

Product mapping across technical grade, pharmaceutical grade, and cosmetic grade categories

Form-based analysis covering liquid, semi-solid, and solid castor oil derivatives

Analysis of reported and modeled annual revenues specific to castor oil portfolios

Coverage of processors representing 75-80% of global market share in 2024

Extrapolation using bottom-up (cultivation area × yield × extraction rate × ASP by region) and top-down (refiner revenue validation) approaches to derive segment-specific valuations for pharmaceutical, personal care and cosmetics, lubricants, paints and coatings, and food & beverage applications

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















