Benzoic Acid Market (2026 - 2035)

ID: MRFR/CnM/0613-CR 128 Pages Chitranshi Jaiswal Last Updated: October 16, 2026
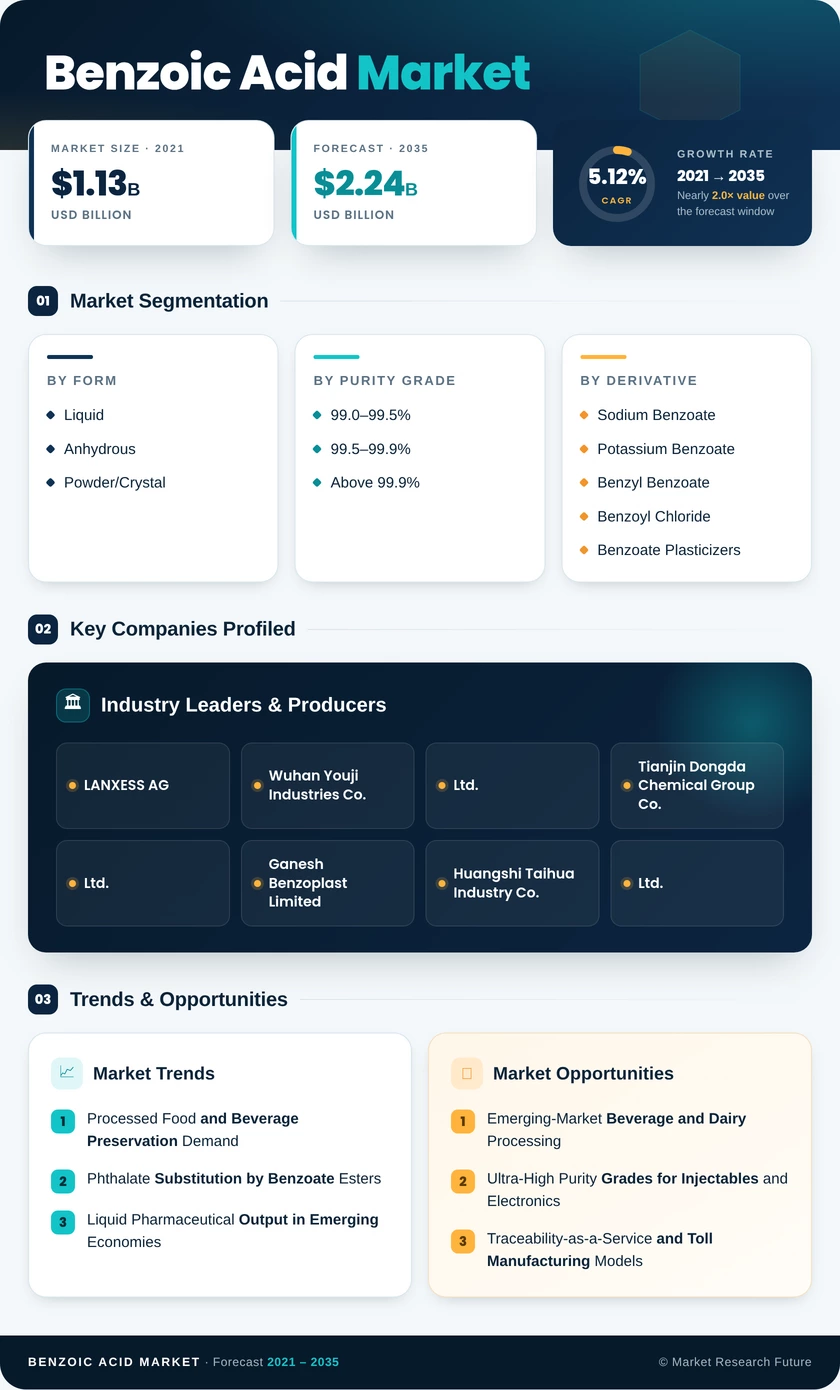
Benzoic Acid Market Research Report Information By Form (Liquid, Anhydrous, and Powder/Crystal), By Purity Grade (99.0–99.5%, 99.5–99.9%, and Above 99.9%), By Derivative (Sodium Benzoate, Potassium Benzoate, Benzyl Benzoate, Benzoyl Chloride, Benzoate Plasticizers, and Other Derivatives), and By Application (Food and Beverage, Pharmaceuticals, Chemicals, Personal Care and Cosmetics, Animal Feed, and Others) – Forecast Till 2035.
Benzoic Acid Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.12%
2025 Market SizeUSD 1.36 Billion
2035 Market SizeUSD 2.24 Billion
Key Players
LANXESS AG
Wuhan Youji Industries Co., Ltd.
Tianjin Dongda Chemical Group Co., Ltd.
Ganesh Benzoplast Limited
Huangshi Taihua Industry Co., Ltd.
FUSHIMI Pharmaceutical Co., Ltd.
Opportunities
  • Emerging-Market Beverage and Dairy Processing
  • Ultra-High Purity Grades for Injectables and Electronics
  • Traceability-as-a-Service and Toll Manufacturing Models
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Form | |
    2. 2.2 By Purity Grade | |
    3. 2.3 By Derivative | |
    4. 2.4 By Application | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Processed Food and Beverage Preservation Demand | |
    2. 4.2 Phthalate Substitution by Benzoate Esters | |
    3. 4.3 Liquid Pharmaceutical Output in Emerging Economies | |
    4. 4.4 Feed Acidifier Adoption After Growth-Promoter Bans | |
    5. 4.5 Regulatory Harmonization of Additive Standards | |
    6. 4.6 Integrated Toluene-Oxidation Capacity in Asia | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Benzene-Formation Concerns in Beverages | |
    2. 5.2 Clean-Label Reformulation Pressure | |
    3. 5.3 Toluene Feedstock Price Volatility | |
    4. 5.4 Category-Specific Use Limits and Additive Scrutiny | |
    5. 5.5 Environmental Compliance Costs for Chinese Producers | |
  6. 6 Opportunities | |
    1. 6.1 Emerging-Market Beverage and Dairy Processing | |
    2. 6.2 Ultra-High Purity Grades for Injectables and Electronics | |
    3. 6.3 Traceability-as-a-Service and Toll Manufacturing Models | |
    4. 6.4 Bio-Based Production Routes | |
    5. 6.5 Asian Swine Feed Acidifiers | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | | |
      4. 7.1.4 Rest of North America | |
    2. 7.2 Europe | | |
      1. 7.2.1 United Kingdom | | |
      2. 7.2.2 Germany | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Russia | | |
      5. 7.2.5 Italy | | |
      6. 7.2.6 Spain | | |
      7. 7.2.7 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 India | | |
      2. 7.3.2 China | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 Australia | | |
      5. 7.3.5 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 South Africa | | |
      2. 7.5.2 Saudi Arabia | | |
      3. 7.5.3 Rest of Middle East and Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Digital Process Control in Oxidation Plants | |
    2. 8.2 Sustainability and Bio-Based Feedstocks | |
    3. 8.3 Additive Regulation Convergence and Scrutiny | |
    4. 8.4 Supply Chain Regionalization | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Form | | |
      1. 9.1.1 Liquid | | |
      2. 9.1.2 Anhydrous | | |
      3. 9.1.3 Powder/Crystal | |
    2. 9.2 By Purity Grade | | |
      1. 9.2.1 Above
    3. 99.0–99.5% | | |
    4. 99.5–99.9% | | |
    5. 99.9% | |
    6. 9.3 By Derivative | | |
      1. 9.3.1 Sodium Benzoate | | |
      2. 9.3.2 Potassium Benzoate | | |
      3. 9.3.3 Benzyl Benzoate | | |
      4. 9.3.4 Benzoyl Chloride | | |
      5. 9.3.5 Benzoate Plasticizers | | |
      6. 9.3.6 Other Derivatives | |
    7. 9.4 By Application | | |
      1. 9.4.1 Food and Beverage | | |
      2. 9.4.2 Pharmaceuticals | | |
      3. 9.4.3 Chemicals | | |
      4. 9.4.4 Personal Care and Cosmetics | | |
      5. 9.4.5 Animal Feed | | |
      6. 9.4.6 Others | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Table | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 LANXESS AG | | |
      2. 10.3.2 Eastman Chemical Company | | |
      3. 10.3.3 Wuhan Youji Industries Co., Ltd. | | |
      4. 10.3.4 Tianjin Dongda Chemical Group Co., Ltd. | | |
      5. 10.3.5 Ganesh Benzoplast Limited | | |
      6. 10.3.6 Huangshi Taihua Industry Co., Ltd. | | |
      7. 10.3.7 FUSHIMI Pharmaceutical Co., Ltd. | | |
      8. 10.3.8 Merck KGaA | | |
      9. 10.3.9 Thermo Fisher Scientific Inc. | | |
      10. 10.3.10 Spectrum Chemical Mfg. Corp. | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Driver Impact Analysis, 2026–2035 | |
  17. TABLE 3 Restraints Impact Analysis, 2026–2035 | |
  18. TABLE 4 Regional Summary, 2025 | |
  19. TABLE 5 North America Market, by Country, 2025 | |
  20. TABLE 6 Europe Market, by Country, 2025 | |
  21. TABLE 7 Asia-Pacific Market, by Country, 2025 | |
  22. TABLE 8 South America Market, by Country, 2025 | |
  23. TABLE 9 Middle East and Africa Market, by Country, 2025 | |
  24. TABLE 10 Market Segmentation, by Form, 2025–2035 | |
  25. TABLE 11 Market Segmentation, by Purity Grade, 2025–2035 | |
  26. TABLE 12 Market Segmentation, by Derivative, 2025–2035 | |
  27. TABLE 13 Market Segmentation, by Application, 2025–2035 | |
  28. TABLE 14 Competitive Benchmarking Table, 2025 | |
  29. TABLE 15 Report Scope and Methodology | |
  30. TABLE 16 Detailed Sources and Citations | | LIST OF FIGURES | |
  31. FIGURE 1 Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  32. FIGURE 2 Industry Value Chain Analysis | |
  33. FIGURE 3 Porter's Five Forces Analysis | |
  34. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  35. FIGURE 5 Market Share, by Form, 2025 | |
  36. FIGURE 6 Market Share, by Purity Grade, 2025 | |
  37. FIGURE 7 Market Share, by Derivative, 2025 | |
  38. FIGURE 8 Market Share, by Application, 2025 | |
  39. FIGURE 9 Regional Market Share, 2025 | |
  40. FIGURE 10 Country-Level Share Within Each Region, 2025 | |
  41. FIGURE 11 Competitive Landscape: Estimated Revenue Share Ranges, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By FormLiquid; Anhydrous; Powder/CrystalAnhydrous (49.0% share)Liquid (6.5% CAGR)
By Purity Grade99.0–99.5%; 99.5–99.9%; Above 99.9%99.5–99.9% (58.0% share)Above 99.9% (7.4% CAGR)
By DerivativeSodium Benzoate; Potassium Benzoate; Benzyl Benzoate; Benzoyl Chloride; Benzoate Plasticizers; Other DerivativesSodium Benzoate (43.0% share)Benzoate Plasticizers (7.1% CAGR)
By ApplicationFood and Beverage; Pharmaceuticals; Chemicals; Personal Care and Cosmetics; Animal Feed; OthersFood and Beverage (59.0% share)Pharmaceuticals (6.6% CAGR)
By RegionNorth America; Europe; Asia-Pacific; South America; Middle-East and AfricaAsia-Pacific (44.5% share)Middle East and Africa (6.3% CAGR)

Market Segmentation Overview

By Form

Sub-SegmentKey Trend
LiquidPre-dissolved solutions adopted by syrup and coating producers
AnhydrousPreferred for dry-mix foods and granular feed premixes
Powder/CrystalFlexible, cost-efficient grade for general use

Anhydrous leads because its low moisture uptake keeps bulk inventories stable in dry-mix food and feed supply chains. Liquid is the fastest-growing form, as pharmaceutical syrup makers and high-shear coating lines value removing on-site dissolution. Powder/Crystal holds a middle position, serving buyers that dissolve material in-house at lower cost.

By Purity Grade

Sub-SegmentKey Trend
99.0–99.5%Price-competitive grade for food and industrial use
99.5–99.9%Default specification for regulated food and oral-dose products
Above 99.9%Rising demand from injectables and specialty coatings

The 99.5–99.9% grade leads because it meets most food and oral pharmaceutical monographs without the cost of further purification. Above 99.9% grows fastest as parenteral formulations and specialty coatings impose tighter impurity limits under USP and Ph. Eur. standards. The 99.0–99.5% tier remains a price-led option for less sensitive uses.

By Derivative

Sub-SegmentKey Trend
Sodium BenzoateCore preservative for acidic beverages and condiments
Potassium BenzoateGrowth in low-sodium food formulations
Benzyl BenzoateStable demand in scabicides and fragrance fixation
Benzoyl ChlorideAgrochemical and peroxide intermediate demand
Benzoate PlasticizersSubstitution of restricted ortho-phthalates
Other DerivativesDyes, resins and research reagents

Sodium Benzoate leads on the strength of soft-drink, juice and pickle preservation, where low pH maximizes its efficacy. Benzoate Plasticizers grow fastest because REACH phthalate restrictions push flooring and adhesive formulators toward benzoate esters. Potassium Benzoate gains steadily as brands cut sodium, while Benzoyl Chloride follows herbicide synthesis demand.

By Application

Sub-SegmentKey Trend
Food and BeveragePackaged food and soft-drink expansion across Bakery, Confectionery, Dairy, Beverage, Sauces and Dressings, and Others
PharmaceuticalsLiquid-dose growth and stricter shelf-life rules in emerging markets
ChemicalsAlkyd resin chain-stopping and intermediate synthesis
Personal Care and CosmeticsParaben-free preservative blends
Animal FeedSwine acidifiers replacing growth promoters
OthersLaboratory and niche industrial uses

Food and Beverage leads, with Beverage and Sauces and Dressings the largest users given their acidic pH and long distribution chains. Pharmaceuticals grow fastest as India and China expand liquid oral output and tighten stability requirements. Animal Feed is a smaller but expanding outlet, driven by antibiotic-reduction policies in swine production.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.