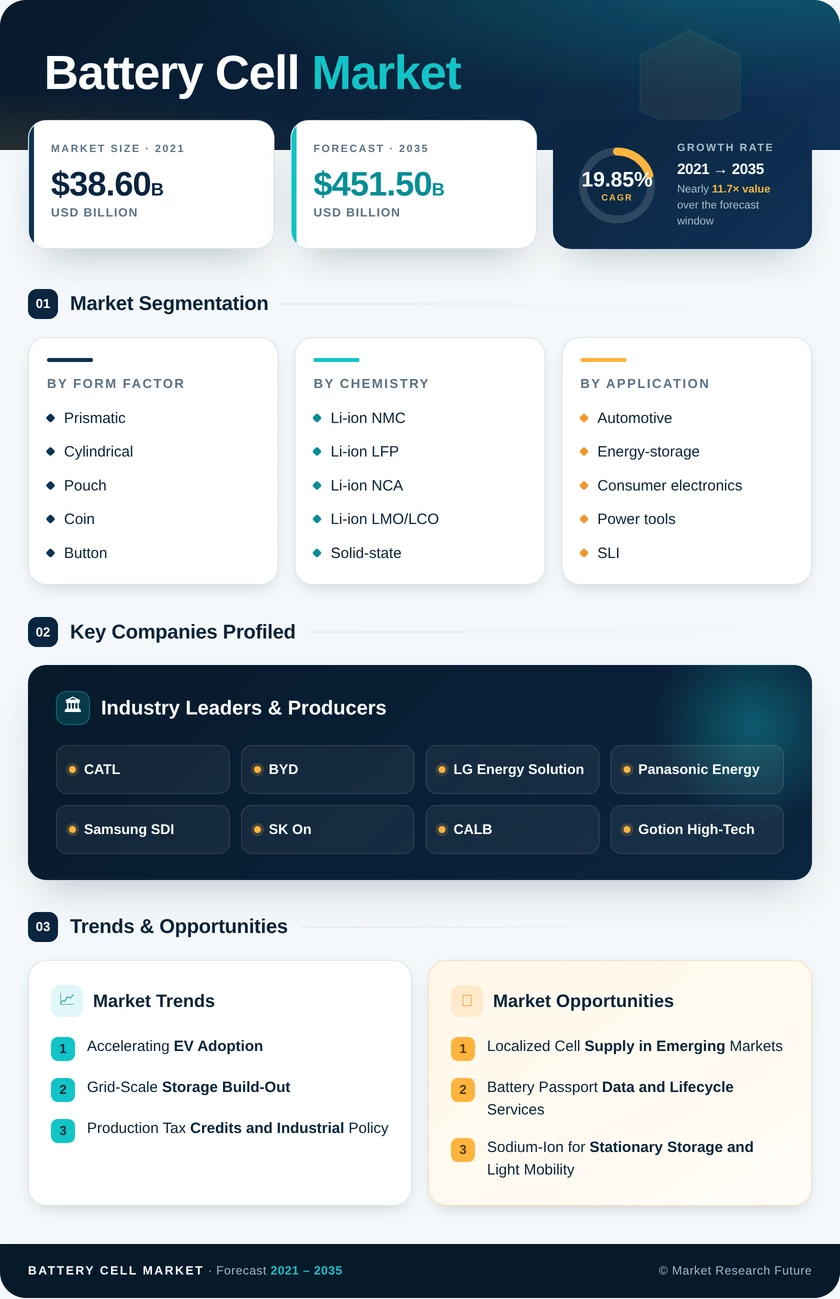
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Form Factor | Prismatic, Cylindrical, Pouch, Coin and Button | Cylindrical (50.5% share) | Pouch (24.4% CAGR) |
| By Chemistry | Li-ion NMC, Li-ion LFP, Li-ion NCA, Li-ion LMO/LCO, Solid-state, Sodium-ion | Li-ion NMC (42.4% share) | Solid-state (38.3% CAGR) |
| By Application | Automotive, Energy-storage, Consumer electronics, Power tools, SLI and micro-mobility | Automotive (52.0% share) | Energy-storage (27.8% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific (68.4% share) | Asia-Pacific (20.6% CAGR) |
Market Segmentation Overview
By Form Factor
| Sub-Segment | Key Trend |
|---|---|
| Prismatic | LFP prismatic cells dominate Chinese EV and storage packs |
| Cylindrical | 4680 large-format cells extend automation advantages |
| Pouch | Cell-to-chassis designs lift volumetric efficiency |
| Coin and Button | Stable demand from wearables and medical devices |
Cylindrical cells lead with a 50.5% share because 2170 and 4680 lines run on highly automated, proven equipment favored by premium EV and tool makers. Pouch cells grow fastest at a 24.4% CAGR, as module-less pack designs reward their flexible shape and low weight. Prismatic cells hold a strong position in LFP packs, although pouch swelling under heavy cycling remains a constraint for commercial fleets.
By Chemistry
| Sub-Segment | Key Trend |
|---|---|
| Li-ion NMC | High-nickel variants serve long-range EVs |
| Li-ion LFP | Cost and safety drive mass-market EV and storage use |
| Li-ion NCA | Premium cylindrical applications |
| Li-ion LMO/LCO | Consumer electronics remain core demand |
| Solid-state | Pilot lines move toward commercial scale after 2027 |
| Sodium-ion | Lithium-free cells target storage and two-wheelers |
Li-ion NMC leads with a 42.4% share on the strength of energy density needed for premium EV range, while Li-ion LFP closes the gap in cost-sensitive vehicles and grid storage. Solid-state grows fastest at a 38.3% CAGR as licensing deals such as PowerCo–QuantumScape move nonflammable electrolytes toward production. Sodium-ion adds a lithium-independent option for storage buyers.
By Application
| Sub-Segment | Key Trend |
|---|---|
| Automotive | Multi-year offtake contracts with EV makers |
| Energy-storage | Utility-scale firming for solar and wind |
| Consumer electronics | Device capacities plateau, volumes flatten |
| Power tools | High-rate cylindrical cells for cordless tools |
| SLI and micro-mobility | Tighter safety certification favors branded cells |
Automotive leads with a 52.0% share because EV programs commit gigawatt-hours of cells years in advance. Energy-storage grows fastest at a 27.8% CAGR as utilities in the U.S., China, and Australia procure batteries for frequency regulation and peak shifting. Consumer electronics and SLI and micro-mobility grow more slowly, with the latter reshaped by certification rules that remove uncertified imports.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA