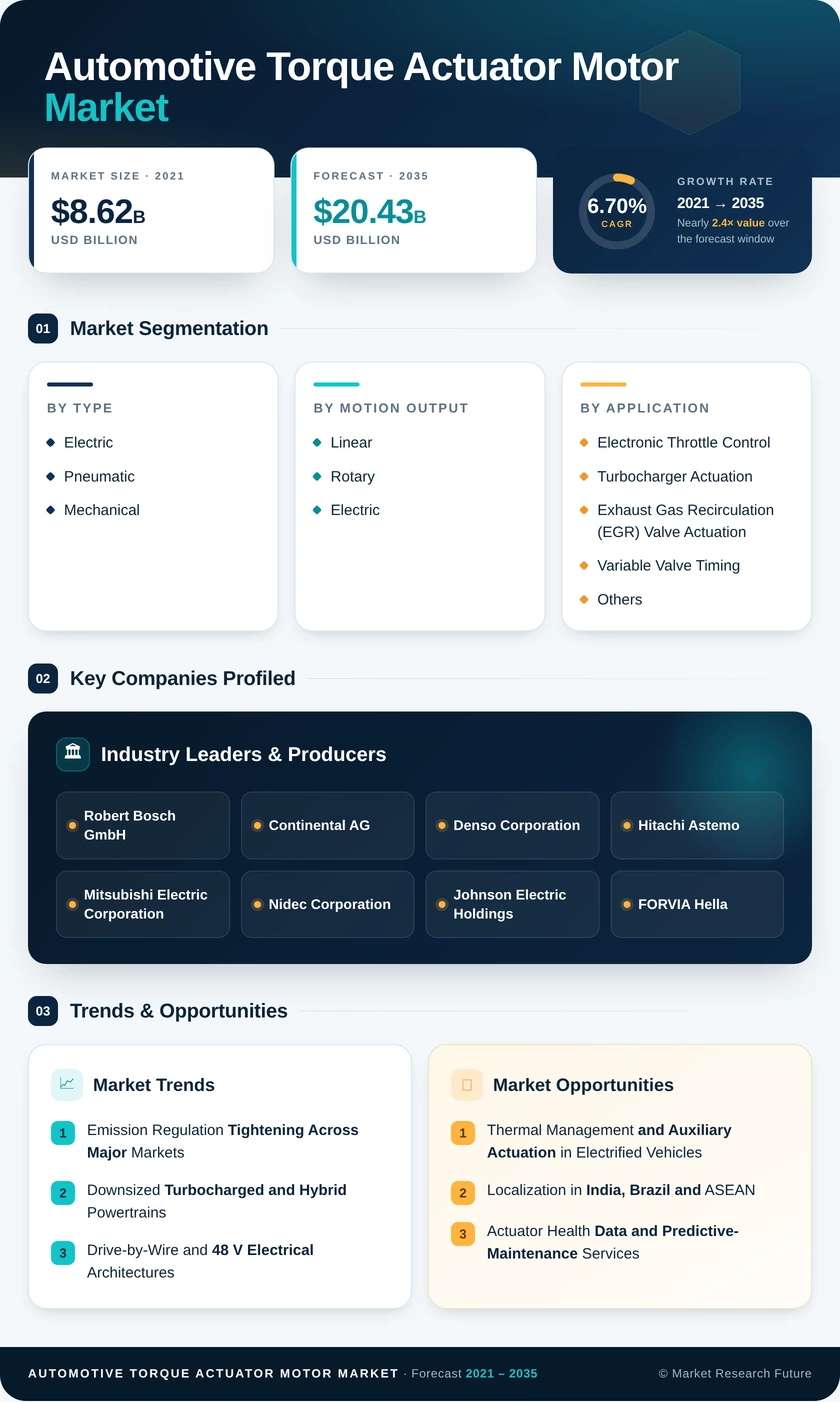
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Type | Electric, Pneumatic, Mechanical | Electric (71.4% share) | Electric (71.4% share; fastest-growing type) |
| By Motion Output | Linear, Rotary, Electric | Rotary (57.3% share) | Linear (6.81% CAGR) |
| By Application | Electronic Throttle Control, Turbocharger Actuation, Exhaust Gas Recirculation (EGR) Valve Actuation, Variable Valve Timing, Others | Electronic Throttle Control (43.4% share) | Turbocharger Actuation (6.73% CAGR) |
| By Vehicle Type | Passenger Vehicles, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles | Passenger Vehicles (60.2% share) | Light Commercial Vehicles (6.77% CAGR) |
| By Sales Channel | OEM, Aftermarket | OEM (81.4% share) | Aftermarket (6.83% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific (44.6% share) | South America (8.1% CAGR) |
Market Segmentation Overview
By Type
| Sub-Segment | Key Trend |
|---|---|
| Electric | Diagnosable, 48 V-compatible designs with redundant sensing and limp-home modes |
| Pneumatic | Retained in heavy-duty engines with onboard compressed air, but losing ground on controllability |
| Mechanical | Sensor overlays on legacy throttle bodies as a low-cost compliance bridge |
Electric actuators lead the type dimension with a 71.4% share and also grow fastest, because OBD, RDE, and ISO 26262 requirements are far easier to satisfy with electronically commanded units. Pneumatic designs persist where trucks already carry compressed-air systems, yet their slower, less precise response is a liability under Euro 7. Mechanical overlays serve only as a transitional option for entry-level engines.
By Motion Output
| Sub-Segment | Key Trend |
|---|---|
| Linear | Direct-drive modules with minimal backlash for EGR valves and exhaust flaps |
| Rotary | Gear-reduction platforms with compact magnetic encoders for throttle and turbo vanes |
| Electric | Integrated electric-output modules combining drive electronics with multi-axis motion |
Rotary actuators lead with a 57.3% share because throttle blades and variable-geometry turbo vanes are inherently angular mechanisms served by mature, high-volume gearing. Linear units grow fastest at a 6.81% CAGR, as EGR valve stroke precision directly determines NOx outcomes and direct-drive designs remove backlash. Electric output modules remain a smaller niche centered on synchronized duties such as variable valve timing.
By Application
| Sub-Segment | Key Trend |
|---|---|
| Electronic Throttle Control | Dual-spring fail-safe blades meeting ASIL-C targets |
| Turbocharger Actuation | Sub-250 ms positional response for variable-geometry and electric boosting |
| Exhaust Gas Recirculation (EGR) Valve Actuation | High- and low-pressure loops adding actuator nodes per engine |
| Variable Valve Timing | Electric cam phasing in downsized and hybrid engines |
| Others | Exhaust flaps, intake runner and swirl control |
Electronic Throttle Control holds a 43.4% share because every drive-by-wire gasoline and hybrid engine requires one, making it the volume foundation of the application mix. Turbocharger Actuation grows fastest at a 6.73% CAGR, driven by the shift from vacuum wastegates to electric control on downsized engines. EGR Valve Actuation adds significant value as emission rules push multi-valve recirculation architectures.
By Vehicle Type
| Sub-Segment | Key Trend |
|---|---|
| Passenger Vehicles | Multiple actuators per turbocharged engine with tighter NVH targets |
| Light Commercial Vehicles | Compact 48 V actuators and predictive maintenance for delivery fleets |
| Medium and Heavy Commercial Vehicles | Extended-durability actuators for EGR and turbo control under heavy-duty standards |
Passenger Vehicles lead with a 60.2% share, reflecting high production volumes and several actuators per turbocharged or hybrid engine. Light Commercial Vehicles grow fastest at a 6.77% CAGR, as last-mile delivery fleets expand and operators prize uptime-focused actuator diagnostics. Medium and Heavy Commercial Vehicles contribute high unit value through ruggedized housings and extended durability specifications.
By Sales Channel
| Sub-Segment | Key Trend |
|---|---|
| OEM | Co-engineered actuators locked in through homologation and multiyear platform awards |
| Aftermarket | Repair kits, complete assembly replacement and remanufactured units for ageing fleets |
OEM supply dominates with an 81.4% share because actuators are calibrated alongside the engine and tied to warranty obligations that favor incumbent tier-1 suppliers. The Aftermarket grows fastest at a 6.83% CAGR as fleets age past 12 years and actuators installed during the 2010s reach end of life. Remanufactured assemblies give independent workshops a lower-cost replacement path without sacrificing performance.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA