Automotive Solenoid Market (2026 - 2035)

Automotive Solenoid Market Research Report By Valve Type (2-Way Valve, 3-Way Valve, 4-Way Valve, 5-Way Valve, Others), By Application Type (Engine Control and Cooling System, Transmission and Drivetrain, Body Control and Interiors, Safety and Security, Others), By Operation Type (Direct Acting, Pilot Operated), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Medium & Heavy Commercial Vehicles, Others), By Sales Channel (OEM, Aftermarket) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast to 2035
ID: MRFR/AT/10730-HCR 128 Pages Shubham Munde, Garvit Vyas Last Updated: October 16, 2026
Automotive Solenoid Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.2%
2025 Market SizeUSD 6.02 Billion
2035 Market SizeUSD 12.06 billion
Key Players
Robert Bosch GmbH
DENSO Corporation
Vitesco / Schaeffler AG
BorgWarner Inc.
Hitachi Astemo Ltd.
FORVIA HELLA
Opportunities
  • Integrated Thermal Manifolds
  • India and ASEAN Localization
  • Predictive Diagnostics as a Service

Automotive Solenoid Market Summary

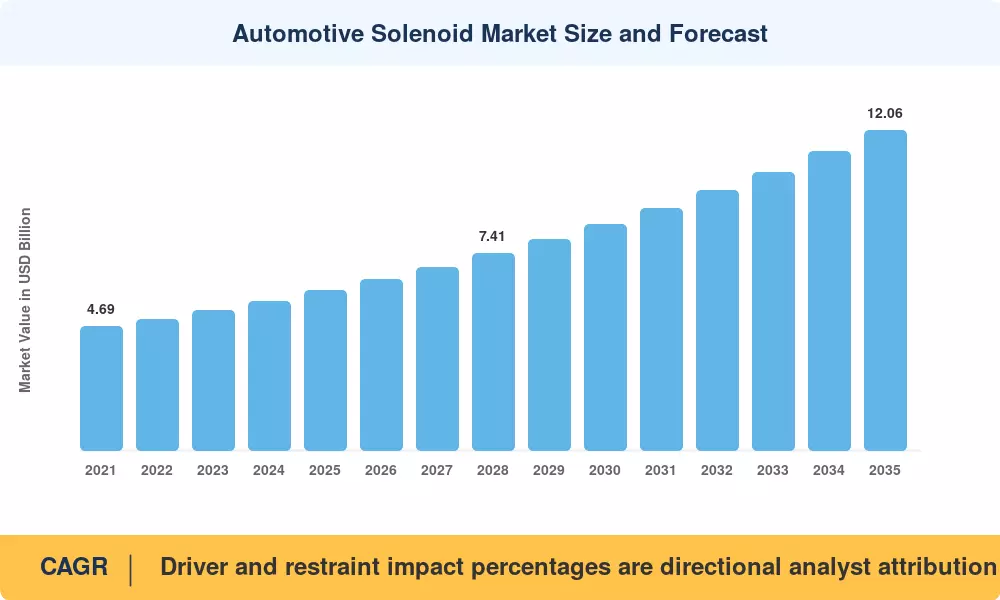
The Automotive Solenoid Market reached USD 6.02 billion in 2025, opens the forecast window at USD 6.45 billion in 2026, and is projected to close at USD 12.06 billion by 2035, expanding at a 7.2% CAGR across 2026โ€“2035. Two catalysts anchor that trajectory. Euro 7, adopted as Regulation (EU) 2024/1257, tightens particulate and brake-emission thresholds from late 2026 and forces finer fluid metering across intake, exhaust, and thermal circuits [1]. In parallel, global EV sales passed 17 million units in 2024, and each battery-electric platform swaps belt-driven accessories for distributed electro-hydraulic and coolant-routing circuits that raise valve content per vehicle [2].

Electrification is rewriting the bill of materials. Mechanical vacuum actuators, cable-pulled linkages and single-speed hydraulic blocks are giving way to fast-switching electromagnetic valves embedded in 8โ€“12 valve mechatronic packs. Bosch alone committed EUR 2.5 billion to software-defined vehicle and electrification programs through 2027, much of it flowing into actuator electronics [3]. Gasoline direct injection and variable valve timing keep combustion demand alive even as hybrids scale.

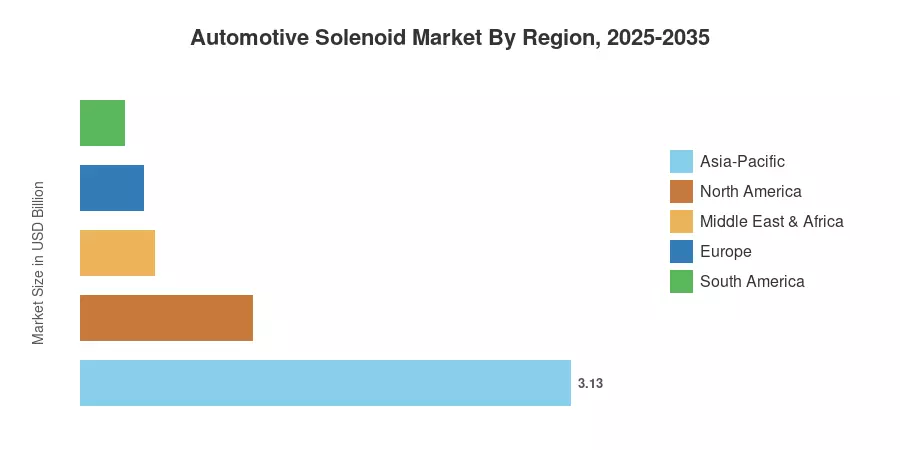
Asia-Pacific commands 52.0% of the Automotive Solenoid Market and also grows fastest, at an 8.9% CAGR. Europe follows at 21.4%, propped up by Euro 7 compliance retooling across German and Czech plants. North America holds third position. Content-per-vehicle gains, not unit volume, will drive the next decade of value creation in the Automotive Solenoid Market.

ย 

Key Report Takeaways

โ€ข By Valve Type

  • 3-Way valves led the Automotive Solenoid Market with a 35.5% share in 2025, reflecting their dominance in transmission hydraulic control
  • 5-Way configurations are the fastest-advancing architecture at a 9.2% CAGR through 2035

โ€ข By Operation Mode

  • 3-Way valves led the Automotive Solenoid Market with 35.5% share in 2025, reflecting their dominance in transmission hydraulic control
  • 5-Way configurations are the fastest-advancing architecture at a 9.2% CAGR through 2035
  • Direct-Acting designs retained 58.9% share, favored for latency-critical injection duty

โ€ข By Application

  • Body Control and Interiors accounted for 31.1% of application demand in 2025
  • Safety and Security posts the steepest application growth at an 8.8% CAGR

โ€ข By Vehicle Type

  • Body Control and Interiors accounted for 31.1% of application demand in 2025
  • Safety and Security posts the steepest application growth at an 8.8% CAGR
  • Passenger Cars generated USD 3.43 billion of Automotive Solenoid Market value in 2025

โ€ข By Region

  • Asia-Pacific held 52.0% of global share in 2025
  • Europe is forecast to compound at 6.6% through 2035 under Euro 7 retooling
  • North America contributed USD 1.10 billion in 2025

ย 

Market Size and Forecast (2021โ€“2035)

Estimates blend OICA vehicle production data, tier-one segment disclosures, customs-level actuator trade flows, and 40-plus primary interviews with powertrain purchasing leads. Historical years are reconciled against audited tier-one automotive electronics revenue; forecast years apply content-per-vehicle escalation layered on regional production outlooks.
Automotive Solenoid Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Euro 7 and equivalent emission tightening ~1.6 Europe, India Short-term (โ‰ค2 yr)
Battery-electric thermal management circuits ~1.5 China, Europe, US Long-term (โ‰ฅ4 yr)
Migration to 8-speed and higher automatics ~1.2 North America, Japan Medium-term (2โ€“4 yr)
Gasoline direct injection and VVT adoption ~1.0 Asia-Pacific Medium-term (2โ€“4 yr)
ADAS-linked brake and stability actuation ~0.9 Europe, North America Medium-term (2โ€“4 yr)
Comfort and access feature democratization ~0.7 Asia-Pacific Short-term (โ‰ค2 yr)
Aftermarket replacement of aging fleets ~0.5 North America, MEA Long-term (โ‰ฅ4 yr)

ย 

Emission Regulation Compression

Euro 7 is not only about reducing tailpipe limitations, but also about extending durability compliance to 200,000 km and introducing brake particulate ceilings of 7 mg/km for passenger automobiles from 2026 [1]. To meet those levels, exhaust gas recirculation and evaporative circuits must maintain flow tolerance across a decade of thermal cycling, driving OEMs toward higher-grade magnetic cores and closed-loop current monitoring. European suppliers are forecasting a 12-18% unit price hike for compliant valve families.

ย 

Electrified Thermal Architecture

Internal combustion platforms never required active coolant routing that battery packs do. Electric models reached about one-in-five of new cars sold globally in 2024, according to IEA data [2]. Each vehicle has between four and nine coolant-diverter and refrigerant-shutoff valves, depending on heat-pump strategy. According to Vitesco and Hitachi Astemo, the order books for coolant valves are expanding faster than their legacy injection portfolios [12].

ย 

Transmission Complexity

Four- and five-speed units have been replaced by eight, nine and ten-speed automatics in all North American light vehicles. Each added ratio means more hydraulic control channels. The ZF 8HP mechatronic module contains about eleven electro-hydraulic valves compared to the previous six-speed generation with six [8]. Transmission demand continues to be the second largest application pool, and the content curve of Chinaโ€™s dual-clutch and hybrid-integrated gearboxes is consistent.

ย 

Safety Actuation Mandates

Advanced Emergency Braking becomes necessary for all new EU type approvals from July 2024 under UN Regulation No. 152, and similar NHTSA rulemaking is targeted at US light vehicles by 2029 [9]. Both use electronic stability control hydraulic modulators packed with fast-response valves that can switch in less than 10 milliseconds. That regulatory floor makes a premium option standard fitment on almost 30 million annual car builds.

ย 

ย 

Restraints Impact Analysis

Restraint weightings reflect analyst judgment on drag intensity within the Automotive Solenoid Market and are directional rather than additive. They represent headwinds already visible in supplier pricing negotiations and program award cycles.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Rare-earth and copper input cost volatility ~-0.8 Global Short-term (โ‰ค2 yr)
Valve-count reduction in simplified EV platforms ~-0.6 China, Europe Long-term (โ‰ฅ4 yr)
OEM annual price-down pressure ~-0.5 Japan, North America Medium-term (2โ€“4 yr)
Solid-state and piezo substitution ~-0.4 Europe Long-term (โ‰ฅ4 yr)
Validation cost for 200,000 km durability ~-0.3 Europe, India Medium-term (2โ€“4 yr)

ย 

Input Cost Exposure

Neodymium-iron-boron prices changed about 40% between 2023 and 2025. Copper wrapping makes for 18-24% of the material cost of a typical valve [13]. Much of that volatility was absorbed by suppliers with fixed multi-year OEM contracts. Both Kendrion and Mikuni noted margin pressure related to magnet sourcing in recent filings, and numerous programs have switched to ferrite-based designs that sacrifice force density for cost stability.

ย 

Platform Simplification Risk

Skateboard EV architectures eliminate fuel systems, evaporative circuits, and exhaust recirculation entirely. Where a modern turbocharged gasoline vehicle may carry 28 to 34 electromagnetic valves, a simplified single-motor BEV can operate with 14 to 19. Volume growth in electric vehicles therefore partially offsets itself, which is why value expansion concentrates in thermal and brake actuation rather than total unit count [2].

Pricing Discipline

Japanese and Korean OEMs typically negotiate 2โ€“4% annual cost reductions across multi-year supply agreements [14]. For commodity two-way and three-way valve families, that ratchet consumes most productivity gains. Suppliers respond by moving up-stack into integrated modules where software calibration and diagnostics justify premium pricing, but the transition takes a full program cycle of five to seven years.

ย 

Automotive Solenoid Market Opportunities

Integrated Thermal Manifolds

Consolidating six to nine discrete coolant valves into a single molded manifold with an onboard controller cuts hose runs, leak paths, and assembly labor. OEMs pay a premium for that consolidation because it saves 1.5โ€“2.5 kg per vehicle and simplifies end-of-line testing. Suppliers that own the manifold interface also own the calibration data stream.

India and ASEAN Localization

India's CAFE-III framework and BS-VII roadmap push emission-control content into a market building over 5.5 million passenger vehicles annually [7]. Local content requirements under the Production Linked Incentive scheme reward suppliers who manufacture domestically, and Padmini VNA has already scaled EGR and canister valve output for export.

Predictive Diagnostics as a Service

Valve coil current signatures reveal wear long before functional failure. Tier-one suppliers can license residual-life algorithms to fleet operators and insurers, converting a one-time hardware sale into recurring subscription revenue. Bosch's Connected Repair platform demonstrates the commercial template, and fleet telematics penetration above 60% in North American commercial vehicles supplies the data backbone .

Commercial Vehicle Retrofit

Euro VI-D retrofit programs in European low-emission zones create replacement demand for exhaust and air-brake valves across trucks built before 2019. Municipal access restrictions in more than 320 European cities make retrofit economically rational rather than optional [16].

High-Voltage Refrigerant Control

Heat-pump adoption in electric vehicles is climbing toward 70% of European BEV builds by 2030, and each heat pump requires refrigerant shutoff and expansion valves rated for 800-volt system environments [15]. Few suppliers currently qualify at that voltage class.

ย 

Automotive Solenoid Market Future Outlook

Software-Defined Actuation

Zonal electrical architectures move valve control from dedicated ECUs to zone controllers running over automotive Ethernet. Suppliers that ship valves with standardized SOME/IP service descriptions will win integration slots; those shipping dumb coils become commodity vendors. The Automotive Solenoid Market will bifurcate accordingly, with software-enabled modules capturing disproportionate margin by 2030.

Thermal Efficiency Economics

IEA modeling indicates heat pumps can extend cold-weather EV range by 15โ€“25% versus resistive heating [2]. That efficiency gain justifies substantially more complex refrigerant routing, and each additional circuit branch adds a controlled valve. Thermal management becomes the single largest growth pool by the early 2030s.

Materials Substitution

Rare-earth supply concentration has pushed engineering teams toward ferrite and soft magnetic composite cores. Early results suggest 8โ€“12% force penalties, recoverable through optimized magnetic circuit geometry and higher drive currents. Successful substitution would materially de-risk the cost base [13].

Circularity and Reporting

Corporate Sustainability Reporting Directive obligations now require tier-one suppliers to disclose Scope 3 emissions and material recovery rates [16]. Remanufactured valve programs, historically an aftermarket curiosity, gain OEM sponsorship as a documented circularity lever, and copper recovery from returned coils improves reported material intensity.

ย 

Regional Market Share Analysis

Region Metric Primary Investment Themes
Asia-Pacific 52.0% share NEV mandates, localization, export hubs
Europe 6.6% CAGR Euro 7 compliance, heat-pump thermal control
North America USD 1.10 Billion Multi-speed automatics, ADAS braking
South America 4.6% share Flex-fuel injection, fleet renewal
Middle East & Africa 7.8% CAGR Aftermarket depth, CKD assembly growth
Total USD 6.02 Billion โ€”

Regional structure in the Automotive Solenoid Market tracks vehicle assembly region far more closely than consumption wealth, because valves are assembled into modules near the OEM plant.

ย 

North America

Country Metric Key Driver
US 78.4% of region Light-truck automatic transmission content
Canada USD 0.12 Billion Assembly plant retooling for EV platforms
Mexico 8.1% CAGR Tier-one manufacturing relocation

ย 

Nearshoring reshaped the North American supplier base after USMCA regional value thresholds rose to 75% for core parts. Mexico's Bajรญo corridor now hosts valve assembly for Bosch, Nidec, and Kendrion, serving US assembly plants within 48-hour logistics windows. EPA's MY2027โ€“2032 light-duty rule, projecting fleet-average targets near 85 g/mile COโ‚‚ by 2032, sustains combustion-side emission control content through the transition [5].

Europe

Country Metric Key Driver
Germany 27.9% of region Premium transmission and thermal modules
UK USD 0.14 Billion Aftermarket and specialist vehicle demand
France 12.6% of region Compact car electrification programs
Italy 9.8% of region Commercial vehicle exhaust control
Spain 8.4% of region High-volume export assembly base
Nordic Countries 7.4% CAGR BEV heat-pump penetration
Russia USD 0.05 Billion Constrained localized supply
Rest of Europe 11.2% of region Central European tier-two clusters

ย 

Regulation drives Europe more than volume does. ACEA reported EU passenger car registrations of roughly 10.6 million units in 2024, below pre-pandemic levels, yet valve value per vehicle rose because Euro 7 durability provisions forced material upgrades [1][17]. German suppliers concentrated capital on 800-volt refrigerant valves, while Czech and Slovak plants absorbed volume production of commodity families.

Asia-Pacific

Country Metric Key Driver
China 54.6% of region NEV mandate and thermal circuit content
India 9.6% CAGR CAFE-III and emission retrofit demand
Japan USD 0.51 Billion Hybrid transmission actuation
South Korea 7.9% of region Export platform electrification
ASEAN USD 0.21 Billion Pickup and MPV assembly growth
Rest of Asia-Pacific 4.1% of region Aftermarket replacement cycles

ย 

China anchors the Automotive Solenoid Market through sheer assembly scale, producing over 31 million vehicles in 2024, with new energy vehicles exceeding 40% of domestic sales [6][20]. MIIT's dual-credit mechanism keeps pushing OEMs toward heat-pump thermal systems, which multiply refrigerant and coolant, valve counts. Japanese demand skews differently, weighted toward hybrid transmission hydraulics where Denso and Mikuni hold entrenched positions.

South America

Country Metric Key Driver
Brazil 68.2% of region Flex-fuel injection and canister systems
Argentina USD 0.05 Billion Pickup truck assembly
Rest of South America 6.4% CAGR Import-led aftermarket demand

ย 

Brazil's Rota 2030 program ties tax incentives to efficiency improvement and local engineering spend, which sustained investment in ethanol-compatible injection hardware [18]. Flex-fuel calibration requires valves tolerant of higher alcohol content, creating a specialized niche that global platforms cannot serve without modification.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 31.4% of region Localization under Vision 2030
UAE USD 0.03 Billion Premium vehicle parc and service demand
South Africa 24.7% of region Export assembly for European OEMs
Egypt 8.3% CAGR CKD assembly incentives
Rest of MEA 18.9% of region Aging fleet replacement

ย 

South Africa remains the region's only meaningful production base, exporting Euro-compliant vehicles that carry full emission-control content. Elsewhere, aftermarket depth matters more than OEM fitment; vehicle parc age above 14 years across much of the region generates steady replacement demand for injection and idle-control valves [19].

ย 

Automotive Solenoid Market By Region, 2025-2035

Automotive Solenoid Market Segmentation

ย 

By Valve Type

Segment Metric Primary Demand Driver
2-Way Valve 28.4% share Fuel shutoff and evaporative control
3-Way Valve 35.5% share Transmission hydraulic switching
4-Way Valve USD 1.18 Billion Heat-pump refrigerant reversal
5-Way Valve 9.2% CAGR Complex multi-circuit thermal routing
Others 5.2% share Specialty and off-highway duty

ย 

Three-way architectures dominate the Automotive Solenoid Market because automatic transmission hydraulic control demands proportional pressure regulation with a single exhaust path. Five-way units grow fastest as integrated thermal manifolds require multi-port switching that discrete valves cannot deliver efficiently. The four-way pool expands alongside reversible heat pumps, where a single valve flips the refrigerant circuit between heating and cooling modes.

By Application

Segment Metric Primary Demand Driver
Engine Control and Cooling System 27.6% share GDI, VVT and thermal regulation
Transmission and Drivetrain USD 1.42 Billion Multi-speed automatic penetration
Body Control and Interiors 31.1% share Comfort access and seat adjustment
Safety and Security 8.8% CAGR Mandatory AEB and stability control
Others 6.2% share HVAC and auxiliary systems

ย 

Body control leads the Automotive Solenoid Market on unit volume rather than unit price. Central locking, tailgate release, fuel-flap actuation and seat ventilation each consume low-cost valves fitted across virtually every trim level. Safety and security grows fastest because regulation, not consumer preference, sets the adoption floor; a stability-control hydraulic module carries eight to twelve precision valves and commands five times the average selling price of a body-control unit.

By Operation Type

Segment Metric Primary Demand Driver
Direct Acting 58.9% share Injection and low-latency switching
Pilot Operated 8.9% CAGR High-flow thermal and brake circuits

ย 

Direct-acting solenoids lead the Automotive Solenoid Market by operation type with a dominant 58.9% share. This is driven by their reliance on electromagnetic force alone to shift internal plungers without requiring system pressure differentials, making them indispensable for low-latency switching, high-precision fuel injection, and low-pressure fluid management. Meanwhile, pilot-operated solenoids represent the fastest-growing operation segment, projecting a market-leading CAGR of 8.9%.

By Vehicle Type

Segment Metric Primary Demand Driver
Passenger Cars 57.0% share Feature democratization and BEV thermal
Light Commercial Vehicles USD 1.49 Billion Last-mile fleet expansion
Medium & Heavy Commercial Vehicles 6.4% CAGR Air brake and exhaust aftertreatment
Others 4.8% share Off-highway and two-wheeler applications

ย 

Passenger Cars lead the Automotive Solenoid Market by vehicle type with a dominant 57.0% share, driven by the rapid democratization of high-end features (such as multi-zone HVAC and automated seating), high-density transmission/braking solenoids, and expanding thermal management requirements in modern Battery Electric Vehicles (BEVs). Meanwhile, Medium & Heavy Commercial Vehicles represent the fastest-growing vehicle type segment, projecting a market-leading CAGR of 6.4%, driven by stringent global tailpipe emission standards requiring heavy-duty exhaust aftertreatment (EGR/SCR) solenoids and complex pneumatic air-brake control systems.

By Sales Channel

Segment Metric Primary Demand Driver
OEM 68.1% share Factory fitment across all platforms
Aftermarket 8.6% CAGR Aging parc and warranty expiry

ย 

Original Equipment Manufacturers (OEMs) lead the Automotive Solenoid Market by sales channel with a dominant 68.1% share, driven by mandatory factory-fitment requirements across engine management, transmission control, emission reduction, and electronic braking platforms. High-volume long-term supply agreements and deep engineering integration during initial vehicle development keep the OEM channel at the core of overall revenue. Meanwhile, the Aftermarket segment represents the fastest-expanding channel, projecting a market-leading CAGR of 8.6%, propelled by the increasing average age of global vehicle parcs, out-of-warranty replacement cycles, and expanding repair demand for high-wear electromechanical solenoids in engine and transmission subsystems.

ย 

Competitive Benchmarking

Concentration sits in the medium band, with an estimated HHI between 780 and 920 and a top-five share of roughly 42โ€“48%. Global tier-ones dominate integrated modules and safety-critical actuation, while regional specialists compete aggressively in body-control and aftermarket families where qualification barriers are lower. Consolidation has been steady rather than dramatic, and the Automotive Solenoid Market rewards suppliers who bundle valves into calibrated subsystems.

Company Est. Revenue Share Range Key Offerings for Automotive Solenoid Market Strategic Positioning
Robert Bosch GmbH ~11โ€“14% Injection valves, ESP modulators, purge units Broadest portfolio; software integration leader
DENSO Corporation ~9โ€“12% VVT, injection, thermal control valves Hybrid powertrain depth; Toyota-anchored
Vitesco / Schaeffler AG ~7โ€“9% Transmission actuation, coolant valves Electrification-focused reposition
BorgWarner Inc. ~6โ€“8% EGR, turbo actuation, thermal modules Emission control and eProduct pivot
Hitachi Astemo Ltd. ~5โ€“7% Brake modulators, injection valves Chassis-plus-powertrain bundling
FORVIA HELLA ~4โ€“6% Body control and actuator electronics Comfort and access specialization
Nidec Corporation ~3โ€“5% Coolant pumps and integrated valve packs Thermal manifold consolidation
Kendrion N.V. ~3โ€“4% Latch, brake, and industrial-grade valves High-mix engineered actuator niche
Rheinmetall AG ~2โ€“4% Exhaust recirculation and air management Commercial vehicle emission strength
Mikuni Corporation ~2โ€“3% Fuel and hydraulic control valves Japanese OEM and motorcycle base
Padmini VNA Mechatronics ~1โ€“2% Emission and canister control valves India localization and export cost base

ย 

ย 

Recent News & Developments

  • European Commission (May 2024): Regulation (EU) 2024/1257 entered force, setting Euro 7 limits with brake particulate ceilings applicable to new passenger car types from late 2026, expanding compliance content in the Automotive Solenoid Market [1]

ย 

ย 

ย 

  • US EPA (April 2024): Finalized MY2027โ€“2032 light- and medium-duty multi-pollutant standards, sustaining emission-control hardware demand through the hybrid transition [5]
  • Denso (November 2023): Disclosed capacity expansion for hybrid transmission control valves at its Anjo works, citing sustained global hybrid order growth [12]
  • India MoRTH (September 2024): Published the CAFE-III consultation framework tightening fleet COโ‚‚ targets from 2027, accelerating supplier localization plans [7]
  • FORVIA HELLA (May 2024): Launched a consolidated body-control actuator platform reducing part count across access and comfort functions by roughly 20% [10]

ย 

Automotive Solenoid Market Report Scope

Report Attribute/Metric Details
Market Scope Global Automotive Solenoid Market by valve type, application, operation type, vehicle type, sales channel and region
Study Period 2021-2035
Base Year 2025
Historical Data 2021โ€“2024
Forecast Period 2026โ€“2035
Market Size in 2025 USD 6.02 Billion
Market Size in 2035 USD 12.06 billion
CAGR (2026โ€“2035) 7.2%
Fastest Growing Segments 5-Way Valve; Safety and Security; Pilot Operated; Aftermarket
Regions Covered North America, Europe, South America, Asia Pacific, Middle East and Africa and ROW
Companies Profiled Robert Bosch GmbH, DENSO Corporation, Vitesco / Schaeffler AG, BorgWarner Inc., Hitachi Astemo Ltd., FORVIA HELLA, Nidec Corporation, Kendrion N.V., Rheinmetall AG, Mikuni Corporation, Padmini VNA Mechatronics
Valuation Currency USD Billion
Methodology 350+ primary expert interviews; bottom-up market sizing; top-down validation; data triangulation; scenario-based forecasting; real-time project tracking

FAQs

How should procurement teams evaluate supplier qualification for the Automotive Solenoid Market?
Prioritize suppliers with PPAP history on comparable duty cycles and documented 200,000 km durability data. Request coil insulation class evidence and salt-spray results before shortlisting. Dual-source commodity families, single-source only integrated modules [1].
What is the typical program award lead time in the Automotive Solenoid Market?
Nomination to start-of-production runs 30โ€“42 months for safety-critical actuation and 18โ€“24 months for body-control families. Tooling amortization is usually recovered across the first 400,000 units [22].
When do piezoelectric actuators beat electromagnetic valves?
Piezo wins where switching below 100 microseconds matters, chiefly in high-pressure diesel injection. Cost runs roughly three times higher, so electromagnetic designs retain nearly all gasoline and auxiliary applications [4].
How does the aftermarket channel differ commercially in the Automotive Solenoid Market?
Aftermarket units carry 25โ€“40% higher gross margin but far lower volume predictability. Distribution depth and catalogue coverage determine share more than engineering capability .
What integration risks appear when consolidating discrete valves into manifolds?
Shared housings create common-mode failure exposure and complicate field service, since one leak can condemn an entire assembly. Warranty modelling should assume higher per-incident replacement cost [12].
Which certification burdens surprise new entrants to the Automotive Solenoid Market?
IATF 16949 certification alone takes 12โ€“18 months, and functional safety work to ISO 26262 ASIL-B adds documented hardware metrics. Many entrants underestimate validation headcount [9].
Do rare-earth restrictions threaten supply continuity?
Export licensing changes have lengthened magnet lead times to 14โ€“20 weeks in some cases. Buyers holding ferrite-qualified alternates face materially lower disruption exposure [13]. ย  ย  ย 
Author
Author Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author Co-Author Profile Garvit Vyas LinkedIn Vice President - Operations
Garvit Vyas is a Research Analyst with experience in working across multiple industry domains in the market research sector. Over the past four years, he has been actively involved in analyzing diverse markets, gathering industry insights, and contributing to the development of comprehensive research reports. His work includes studying market trends, evaluating competitive landscapes, and supporting data-driven business insights. In the early phase of his career, Garvit worked on cross-domain research projects, which helped him build a strong foundation in market analysis, data interpretation, and industry intelligence across various sectors. Later, he transitioned into the Quality Control (QC) function, where he focuses on reviewing and refining research reports and marketing collaterals to ensure accuracy, consistency, and high editorial standards. His responsibilities include validating research data, improving report structure, and maintaining the overall quality of published content. Garvit is committed to maintaining strong research integrity and delivering reliable insights that support informed business decision-making.

Research Approach

ย 

Secondary Research

The secondary research process involved comprehensive analysis of automotive industry databases, technical publications, patent repositories, and authoritative transportation organizations. Key sources included the U.S. Environmental Protection Agency (EPA), European Environment Agency (EEA), International Energy Agency (IEA), International Organization of Motor Vehicle Manufacturers (OICA), U.S. Department of Transportation (DOT), National Highway Traffic Safety Administration (NHTSA), European Automobile Manufacturers' Association (ACEA), Society of Automotive Engineers (SAE International), International Electrotechnical Commission (IEC), Japan Automobile Manufacturers Association (JAMA), China Association of Automobile Manufacturers (CAAM), Indian Automotive Research Association (ARAI), and national automotive ministry reports from key production markets. These sources were used to collect vehicle production statistics, emission regulation frameworks, electrification adoption data, safety standard compliance metrics, and technological landscape analysis for 2-way valve solenoids, 3-way valve solenoids, 4-way valve solenoids, and other specialty valve configurations across passenger vehicles, light commercial vehicles (LCV), heavy commercial vehicles (HCV), and electric vehicles.

ย 

Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. tier-1 automotive component manufacturers, tier-2 solenoid specialists, and OEMs were among the supply-side sources, which included CEOs, VPs of Engineering, global sales directors, and R&D leaders. Demand-side sources included procurement leaders at original equipment manufacturers, vehicle platform engineering directors, powertrain system architects, fleet managers from commercial vehicle operators, and electrification transition consultants. The primary research validated market segmentation, confirmed the timelines for the integration of EV platforms, and collected insights on the dynamics of supplier consolidation, the evolution of fuel injection systems, and the adoption of thermal management systems.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (38%), Europe (30%), Asia-Pacific (25%), Rest of World (7%)

ย 

Market Size Estimation

Global market valuation was derived through production volume mapping and system integration revenue analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Product mapping across 2-way valve, 3-way valve, 4-way valve, and other specialty configurations

Application coverage spanning engine control modules, fuel and emission control systems, HVAC thermal management, and emerging EV-specific applications

Analysis of reported and modeled annual revenues specific to solenoid valve portfolios

Coverage of manufacturers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (vehicle production volume ร— solenoid content per vehicle ร— ASP by platform) and top-down (manufacturer revenue validation across tier-1 and tier-2 suppliers) approaches to derive segment-specific valuations across vehicle types and regional markets

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.