Segmentation Quick Reference
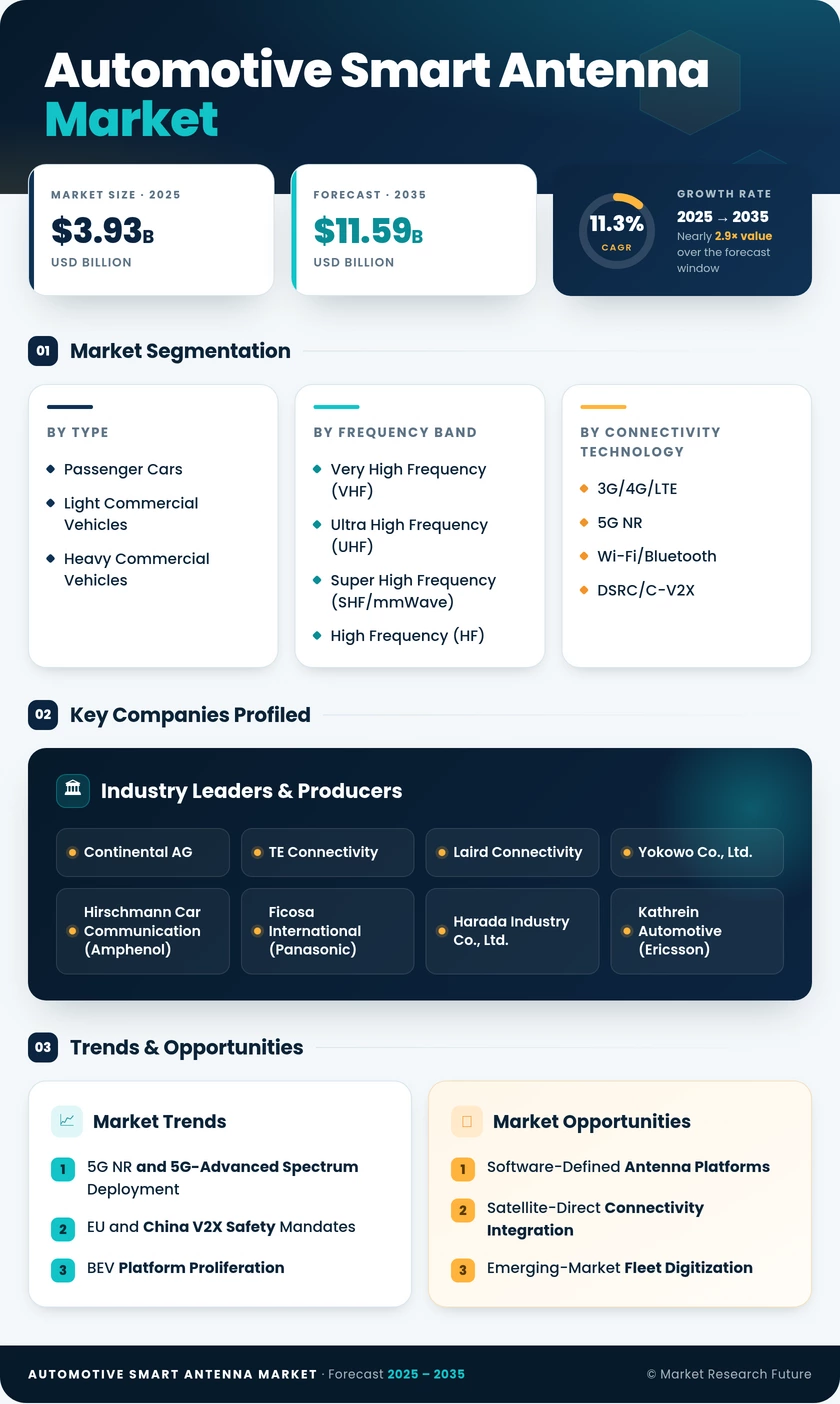
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| Antenna Type | Shark-Fin, Fixed Mast, Glass/Integrated, Embedded Module, Others | Shark-Fin | Embedded Module |
| Frequency Band | VHF, UHF, SHF/mmWave, HF | VHF | SHF/mmWave |
| Connectivity Technology | 3G/4G/LTE, 5G NR, Wi-Fi/Bluetooth, DSRC/C-V2X | 3G/4G/LTE | 5G NR |
| Vehicle Type | Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles | Passenger Cars | Light Commercial Vehicles |
| Vehicle Propulsion | ICE, BEV, PHEV, FCEV | ICE | BEV |
| Installation Location | Roof, Windshield/Glass, Bumper/Fascia, Interior/Dashboard | Roof | Windshield/Glass |
Market Segmentation Overview
By Antenna Type
| Sub-Segment | Key Trend |
| Shark-Fin | Continues to dominate due to compact multi-band design and OEM aesthetic preference |
| Fixed Mast | Declining share as OEMs phase out single-function legacy mast designs |
| Glass/Integrated | Growing adoption in panoramic-roof BEV platforms from premium automakers |
| Embedded Module | Fastest ramp-up driven by flush-body EV architectures and MIMO requirements |
| Others | Niche applications including retractable and specialty commercial-vehicle antennas |
Shark-fin antennas remain the default choice for most global OEM platforms. Still, the transition toward embedded and glass-integrated solutions is accelerating as vehicle designers prioritize aerodynamic efficiency and seamless exterior aesthetics in next-generation electric vehicles.
By Frequency Band
| Sub-Segment | Key Trend |
| VHF | Sustained baseline demand from AM/FM broadcast reception requirements |
| UHF | Driven by DAB radio adoption in Europe and early LTE connectivity modules |
| SHF/mmWave | Rapid growth linked to 5G mmWave rollout in dense urban corridors |
| HF | Limited to niche shortwave and specialized communication applications |
The frequency-band mix is shifting upward as 5G NR and millimeter-wave deployments expand, requiring antenna modules to cover wider bandwidth ranges with higher gain at shorter wavelengths.
By Connectivity Technology
| Sub-Segment | Key Trend |
| 3G/4G/LTE | Large installed base but declining share as 3G networks sunset globally |
| 5G NR | Fastest-growing segment, enabling OTA updates and autonomous driving data pipelines |
| Wi-Fi/Bluetooth | Stable in-cabin connectivity for device tethering and passenger hotspot services |
| DSRC/C-V2X | Policy-driven growth in V2X safety messaging across the EU and China |
5G NR is reshaping the connectivity-technology landscape, and antenna modules must support both sub-6 GHz and mmWave bands to meet OEM platform requirements for the next decade.
By Vehicle Type
| Sub-Segment | Key Trend |
| Passenger Cars | Volume leader, driven by consumer demand for connected infotainment and safety |
| Light Commercial Vehicles | Growing telematics penetration for fleet management and logistics optimization |
| Heavy Commercial Vehicles | Regulatory mandates for eCall and digital tachograph connectivity |
Passenger cars set the specification standard, but commercial vehicles are closing the connectivity gap as fleet digitization programs expand globally.
By Vehicle Propulsion
| Sub-Segment | Key Trend |
| ICE | Dominant by installed base but gradually ceding share to electric powertrains. |
| BEV | Fastest-growing segment with platform-level antenna integration as standard |
| PHEV | Transitional segment with full connectivity specifications matching BEV platforms |
| FCEV | Niche applications primarily in heavy-duty commercial and bus segments |
The propulsion mix shift toward BEVs is the single largest structural tailwind for antenna-module content growth per vehicle.
By Installation Location
| Sub-Segment | Key Trend |
| Roof | Preferred location for optimal sky-view angle across GNSS, cellular, and satellite bands |
| Windshield/Glass | Transparent conductive-film antennas enabling flush integration in premium BEVs |
| Bumper/Fascia | Short-range V2X and radar-coexistence antenna placements |
| Interior/Dashboard | Wi-Fi and Bluetooth modules for in-cabin connectivity distribution |
Roof-mounted installations will retain their leadership position, but glass-integrated solutions represent the fastest-growing installation category as OEMs seek to eliminate visible external antenna protrusions.
You’ve used 75% of your weekly limit.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA