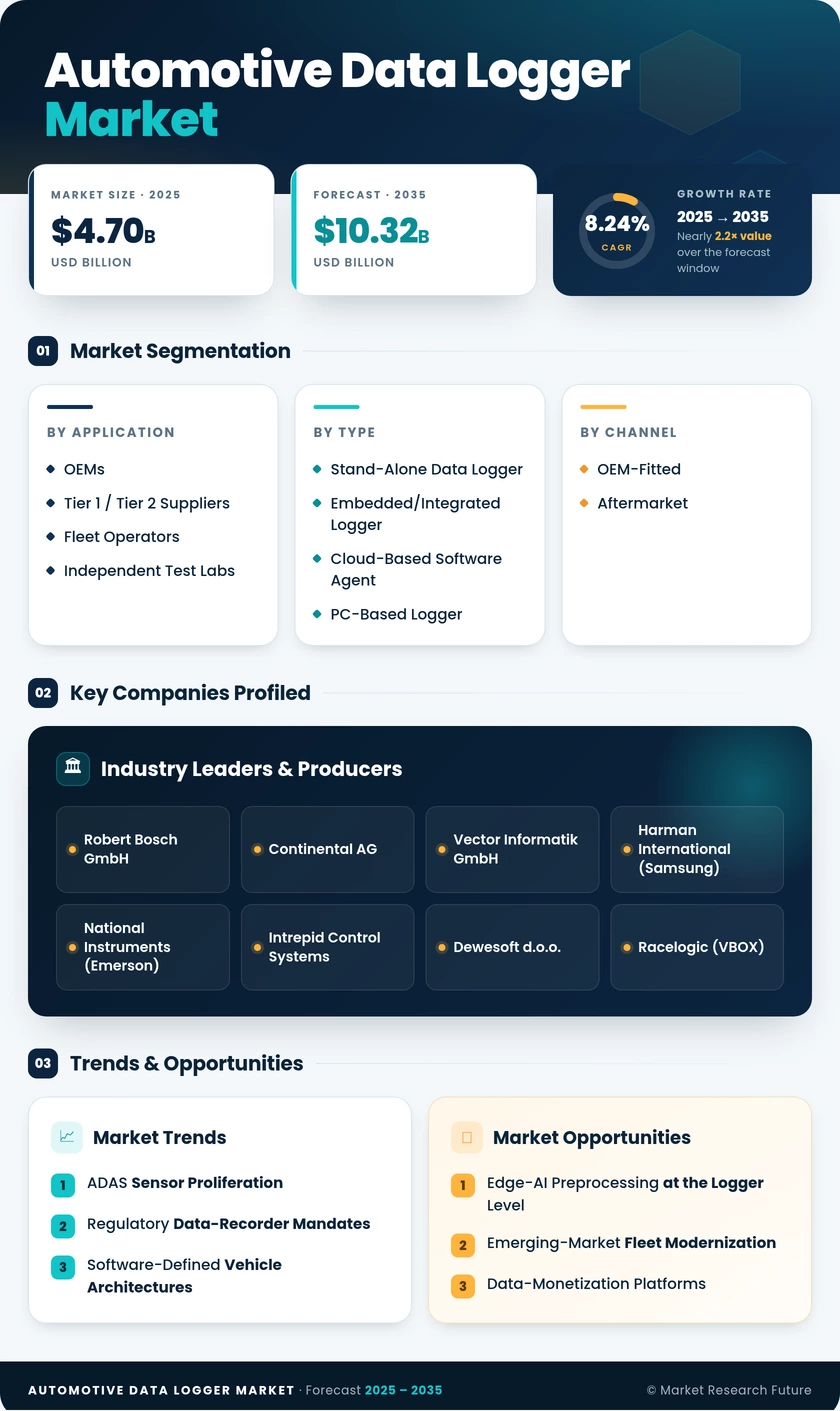
Automotive Data Logger Market (2025 - 2035)

ID: MRFR/AT/5213-CR 154 Pages Shubham Munde Last Updated: September 15, 2026
Automotive Data Logger Market Research Report By Application (ADAS, Autonomous Driving R&D, Powertrain Diagnostics, Vehicle Dynamics & Chassis, Fleet & Telematics), By Connection Type (USB, Automotive Ethernet, CAN / CAN FD, Wireless (Wi-Fi / Cellular), SD Card / PCMCIA), By Hardware Type (Stand-Alone Data Logger, Embedded/Integrated Logger, Cloud-Based Software Agent, PC-Based Logger), By Memory Capacity (Less Than 32 GB, 32–128 GB, 128–512 GB, Above 512 GB), By End User (OEMs, Tier 1 / Tier 2 Suppliers, Fleet Operators, Independent Test Labs), By Channel (OEM-Fitted, Aftermarket), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles), By Propulsion (ICE Vehicles, Battery Electric Vehicles, Hybrid Electric Vehicles) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035
Automotive Data Logger Market
Market Size
Forecast Period2025-2035
CAGR (2025-2035)8.24%
2025 Market SizeUSD 4.70 Billion
2035 Market SizeUSD 10.32 Billion
Key Players
Robert Bosch GmbH
Continental AG
Vector Informatik GmbH
Harman International
National Instruments
Intrepid Control Systems
Opportunities
  • Edge-AI Preprocessing at the Logger Level
  • Emerging-Market Fleet Modernization
  • Data-Monetization Platforms
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways
  3. 3 Market Dynamics |
    1. 3.1 Market Drivers Analysis | |
      1. 3.1.1 ADAS Sensor Proliferation and L2+ Mandate Expansion | |
      2. 3.1.2 EU/China/UNECE Event-Data-Recorder Mandates | |
      3. 3.1.3 Software-Defined Vehicle Architecture Transition | |
      4. 3.1.4 Fleet Digitalization and Usage-Based Insurance | |
      5. 3.1.5 Autonomous-Driving Validation Data Requirements | |
      6. 3.1.6 Cybersecurity Logging Compliance (UNECE R155/R156) | |
      7. 3.1.7 EV Powertrain Diagnostics and Battery Health Monitoring |
    2. 3.2 Market Restraints Analysis | |
      1. 3.2.1 Data Privacy and Sovereignty Regulations | |
      2. 3.2.2 High Per-Unit Cost of Multi-Channel Loggers | |
      3. 3.2.3 Cybersecurity Risk of Recorded Vehicle Data | |
      4. 3.2.4 Fragmented Communication-Protocol Landscape | |
      5. 3.2.5 Limited Aftermarket Awareness in Developing Regions |
    3. 3.3 Market Opportunity Analysis | |
      1. 3.3.1 Edge-AI Preprocessing at the Logger Level | |
      2. 3.3.2 Emerging-Market Fleet Modernization | |
      3. 3.3.3 Data-Monetization Platforms | |
      4. 3.3.4 EV Battery-Health Diagnostics | |
      5. 3.3.5 Cybersecurity Audit Logging
  4. 4 Global Automotive Data Logger Market Size & Forecast (2021–2035) |
    1. 4.1 Historical Market Size (2021–2025) |
    2. 4.2 Current & Forecast Market Size (2026–2035) |
    3. 4.3 Market Size by Revenue (USD Billion) |
    4. 4.4 Year-over-Year Growth Analysis
  5. 5 Segmentation Analysis |
    1. 5.1 By Application | |
      1. 5.1.1 ADAS | |
      2. 5.1.2 Autonomous Driving R&D | |
      3. 5.1.3 Powertrain Diagnostics | |
      4. 5.1.4 Vehicle Dynamics & Chassis | |
      5. 5.1.5 Fleet & Telematics |
    2. 5.2 By Connection Type | |
      1. 5.2.1 USB | |
      2. 5.2.2 Automotive Ethernet | |
      3. 5.2.3 CAN / CAN FD | |
      4. 5.2.4 Wireless (Wi-Fi / Cellular) | |
      5. 5.2.5 SD Card / PCMCIA |
    3. 5.3 By Hardware Type | |
      1. 5.3.1 Stand-Alone Data Logger | |
      2. 5.3.2 Embedded/Integrated Logger | |
      3. 5.3.3 Cloud-Based Software Agent | |
      4. 5.3.4 PC-Based Logger |
    4. 5.4 By Memory Capacity | |
      1. 5.4.1 Less Than 32 GB | |
      2. 5.4.2 32–128 GB | |
      3. 5.4.3 128–512 GB | |
      4. 5.4.4 Above 512 GB |
    5. 5.5 By End User | |
      1. 5.5.1 OEMs | |
      2. 5.5.2 Tier 1 / Tier 2 Suppliers | |
      3. 5.5.3 Fleet Operators | |
      4. 5.5.4 Independent Test Labs |
    6. 5.6 By Channel | |
      1. 5.6.1 OEM-Fitted | |
      2. 5.6.2 Aftermarket |
    7. 5.7 By Vehicle Type | |
      1. 5.7.1 Passenger Cars | |
      2. 5.7.2 Light Commercial Vehicles | |
      3. 5.7.3 Heavy Commercial Vehicles |
    8. 5.8 By Propulsion | |
      1. 5.8.1 ICE Vehicles | |
      2. 5.8.2 Battery Electric Vehicles | |
      3. 5.8.3 Hybrid Electric Vehicles
  6. 6 Regional Analysis |
    1. 6.1 North America | |
      1. 6.1.1 United States | |
      2. 6.1.2 Canada | |
      3. 6.1.3 Mexico |
    2. 6.2 Europe | |
      1. 6.2.1 Germany | |
      2. 6.2.2 United Kingdom | |
      3. 6.2.3 France | |
      4. 6.2.4 Italy | |
      5. 6.2.5 Spain | |
      6. 6.2.6 Nordic Countries | |
      7. 6.2.7 Russia | |
      8. 6.2.8 Rest of Europe |
    3. 6.3 Asia-Pacific | |
      1. 6.3.1 China | |
      2. 6.3.2 India | |
      3. 6.3.3 Japan | |
      4. 6.3.4 South Korea | |
      5. 6.3.5 ASEAN | |
      6. 6.3.6 Rest of Asia-Pacific |
    4. 6.4 South America | |
      1. 6.4.1 Brazil | |
      2. 6.4.2 Argentina | |
      3. 6.4.3 Rest of South America |
    5. 6.5 Middle East & Africa | |
      1. 6.5.1 Saudi Arabia | |
      2. 6.5.2 UAE | |
      3. 6.5.3 South Africa | |
      4. 6.5.4 Egypt | |
      5. 6.5.5 Rest of MEA
  7. 7 Competitive Landscape |
    1. 7.1 Market Share Analysis (2025) |
    2. 7.2 Competitive Benchmarking Matrix |
    3. 7.3 Company Profiles | |
      1. 7.3.1 Robert Bosch GmbH | |
      2. 7.3.2 Continental AG | |
      3. 7.3.3 Vector Informatik GmbH | |
      4. 7.3.4 Harman International (Samsung) | |
      5. 7.3.5 National Instruments (Emerson) | |
      6. 7.3.6 Intrepid Control Systems | |
      7. 7.3.7 Dewesoft d.o.o. | |
      8. 7.3.8 Racelogic (VBOX) | |
      9. 7.3.9 HEM Data Corporation | |
      10. 7.3.10 IPETRONIK GmbH (Magna)
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) |
    1. 8.1 Autonomous-Vehicle Validation at Scale |
    2. 8.2 Platform Economics and Data-as-a-Service |
    3. 8.3 Electrification and Battery-Lifecycle Intelligence |
    4. 8.4 Cybersecurity and ESG-Driven Data Governance
  9. 9 Recent Developments & News
  10. 10 Frequently Asked Questions (FAQs)
  11. 11 Report Scope & Methodology |
    1. 11.1 Study Period & Base Year |
    2. 11.2 Data Sources & Citations |
    3. 11.3 Abbreviations
  12. 12 LIST OF TABLES |
  13. TABLE 1 Global Automotive Data Logger Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  14. TABLE 2 Global Automotive Data Logger Market – Year-over-Year Growth Analysis, 2021–2035 |
  15. TABLE 3 Market Driver Impact Analysis, 2026–2035 |
  16. TABLE 4 Market Restraint Impact Analysis, 2026–2035 |
  17. TABLE 5 Global Automotive Data Logger Market Size, by Application, 2021–2035 (USD Billion) |
  18. TABLE 6 Global Automotive Data Logger Market Size, by Connection Type, 2021–2035 (USD Billion) |
  19. TABLE 7 Global Automotive Data Logger Market Size, by Hardware Type, 2021–2035 (USD Billion) |
  20. TABLE 8 Global Automotive Data Logger Market Size, by Memory Capacity, 2021–2035 (USD Billion) |
  21. TABLE 9 Global Automotive Data Logger Market Size, by End User, 2021–2035 (USD Billion) |
  22. TABLE 10 Global Automotive Data Logger Market Size, by Channel, 2021–2035 (USD Billion) |
  23. TABLE 11 Global Automotive Data Logger Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  24. TABLE 12 Global Automotive Data Logger Market Size, by Propulsion, 2021–2035 (USD Billion) |
  25. TABLE 13 Global Automotive Data Logger Market Size, by Region, 2021–2035 (USD Billion) |
  26. TABLE 14 Regional Summary — Automotive Data Logger Market, 2025 |
  27. TABLE 15 North America Automotive Data Logger Market Size, by Country, 2021–2035 (USD Billion) |
  28. TABLE 16 Europe Automotive Data Logger Market Size, by Country, 2021–2035 (USD Billion) |
  29. TABLE 17 Asia-Pacific Automotive Data Logger Market Size, by Country, 2021–2035 (USD Billion) |
  30. TABLE 18 South America Automotive Data Logger Market Size, by Country, 2021–2035 (USD Billion) |
  31. TABLE 19 Middle East & Africa Automotive Data Logger Market Size, by Country, 2021–2035 (USD Billion) |
  32. TABLE 20 Competitive Benchmarking Matrix — Automotive Data Logger Market, 2025 |
  33. TABLE 21 Company Profiles — Key Players, Automotive Data Logger Market |
  34. TABLE 22 Recent Developments & Strategic Announcements, 2023–2025 |
  35. TABLE 23 Report Scope & Methodology Summary |
  36. TABLE 24 Detailed Sources and Citations
  37. 13 LIST OF FIGURES |
  38. FIGURE 1 Market Dynamics Overview — Automotive Data Logger Market |
  39. FIGURE 2 Industry Value Chain Analysis |
  40. FIGURE 3 Porter's Five Forces Analysis — Automotive Data Logger Market |
  41. FIGURE 4 Global Automotive Data Logger Market Size Trend (USD Billion), 2021–2035 |
  42. FIGURE 5 Market Size by Application — Share Chart, 2025 |
  43. FIGURE 6 Market Size by Connection Type — Share Chart, 2025 |
  44. FIGURE 7 Market Size by Hardware Type — Share Chart, 2025 |
  45. FIGURE 8 Market Size by Memory Capacity — Share Chart, 2025 |
  46. FIGURE 9 Market Size by End User — Share Chart, 2025 |
  47. FIGURE 10 Market Size by Channel — Share Chart, 2025 |
  48. FIGURE 11 Market Size by Vehicle Type — Share Chart, 2025 |
  49. FIGURE 12 Market Size by Propulsion — Share Chart, 2025 |
  50. FIGURE 13 Regional Revenue Share — Automotive Data Logger Market, 2025 |
  51. FIGURE 14 North America Automotive Data Logger Market — Country Share, 2025 |
  52. FIGURE 15 Europe Automotive Data Logger Market — Country Share, 2025 |
  53. FIGURE 16 Asia-Pacific Automotive Data Logger Market — Country Share, 2025 |
  54. FIGURE 17 South America Automotive Data Logger Market — Country Share, 2025 |
  55. FIGURE 18 Middle East & Africa Automotive Data Logger Market — Country Share, 2025 |
  56. FIGURE 19 Competitive Landscape — Market Share Heatmap, 2025 |
  57. FIGURE 20 Strategic Group Mapping — Automotive Data Logger Market

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
ApplicationADAS; Autonomous Driving R&D; Powertrain Diagnostics; Vehicle Dynamics & Chassis; Fleet & TelematicsADASAutonomous Driving R&D
Connection TypeUSB; Automotive Ethernet; CAN / CAN FD; Wireless (Wi-Fi / Cellular); SD Card / PCMCIAUSBAutomotive Ethernet
Hardware TypeStand-Alone Data Logger; Embedded/Integrated Logger; Cloud-Based Software Agent; PC-Based LoggerStand-Alone Data LoggerCloud-Based Software Agent
Memory CapacityLess Than 32 GB; 32–128 GB; 128–512 GB; Above 512 GB32–128 GBAbove 512 GB
End UserOEMs; Tier 1 / Tier 2 Suppliers; Fleet Operators; Independent Test LabsOEMsFleet Operators
ChannelOEM-Fitted; AftermarketOEM-FittedAftermarket
Vehicle TypePassenger Cars; Light Commercial Vehicles; Heavy Commercial VehiclesPassenger CarsHeavy Commercial Vehicles
PropulsionICE Vehicles; Battery Electric Vehicles; Hybrid Electric VehiclesICE VehiclesBattery Electric Vehicles


Market Segmentation Overview

By Application

Sub-SegmentKey Trend
ADASEuro NCAP 2026 roadmap driving investment in multi-sensor validation logging.
Autonomous Driving R&DL3/L4 testing programs generating 10–20 TB per vehicle per day
Powertrain DiagnosticsEV battery-cell monitoring expanding logging scope beyond traditional engine parameters.
Vehicle Dynamics & ChassisHigh-g event capture and tire-performance modeling for performance vehicle programs
Fleet & TelematicsUsage-based insurance programs creating aftermarket retrofit demand


ADAS remains the largest application category as automakers embed L2+ features across mainstream vehicle lineups. Autonomous-driving R&D is gaining ground rapidly because every mile of AV testing produces massive sensor-fusion datasets that require high-fidelity, time-synchronized capture.

By Connection Type

Sub-SegmentKey Trend
USBPlug-and-play universality keeps USB as the default interface for portable loggers.
Automotive Ethernet10BASE-T1S and 100BASE-T1 adoption replacing CAN for high-bandwidth streams
CAN / CAN FDLegacy dominance sustained by billions of installed ECUs worldwide
Wireless (Wi-Fi / Cellular)OTA data offloading for connected-fleet and cloud-logger deployments
SD Card / PCMCIADeclining share as internal SSD and cloud alternatives scale


USB connectivity leads due to its universal compatibility across test benches and aftermarket devices. Automotive Ethernet is emerging as the next-generation standard, driven by the bandwidth demands of camera and LiDAR recording.

By Hardware Type

Sub-SegmentKey Trend
Stand-Alone Data LoggerPreferred for field testing, crash reconstruction, and portable deployment
Embedded/Integrated LoggerGrowing as OEMs embed logging into series-production telematics control units
Cloud-Based Software AgentLowest unit cost, scalable via containerized workloads on vehicle compute platforms
PC-Based LoggerDominant in laboratory high-channel-count measurement environments


Stand-alone loggers dominate today because they can be redeployed across multiple vehicles without modification. Cloud-based software agents are the fastest-growing category, reflecting the industry's pivot toward software-defined logging architectures.

By Memory Capacity

Sub-SegmentKey Trend
Less Than 32 GBSufficient for single-channel CAN logging and short-duration captures
32–128 GBSweet-spot tier for multi-channel ADAS validation recording sessions
128–512 GBExpanding with multi-camera and radar-fusion data requirements
Above 512 GBRequired for full-day autonomous-driving data collection campaigns


The 32–128 GB tier represents the mainstream capacity choice, balancing cost and recording duration for typical ADAS test cycles. Capacities above 512 GB are growing fastest as autonomous-driving programs generate ever-larger datasets.

By End User

Sub-SegmentKey Trend
OEMsEDR compliance and ADAS development create sustained volume demand
Tier 1 / Tier 2 SuppliersComponent-level calibration and validation testing requirements
Fleet OperatorsInsurance incentives and predictive-maintenance ROI driving aftermarket adoption
Independent Test LabsThird-party homologation services expanding in Asia-Pacific


OEMs remain the dominant end-user category, driven by regulatory EDR mandates and in-house ADAS validation needs. Fleet operators represent the fastest-growing user segment as telematics and insurance incentives lower the payback period for aftermarket logger investments.

By Channel

Sub-SegmentKey Trend
OEM-FittedFactory-installed EDRs and ADAS loggers increasingly standard on new vehicles
AftermarketRetrofit demand driven by fleet operators and usage-based insurance programs


OEM-fitted solutions command the majority share because regulatory mandates require factory-level integration. The aftermarket channel is growing faster as fleet operators and individual vehicle owners seek retrofit logging solutions.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsLargest segment by volume due to ADAS penetration across mass-market models
Light Commercial VehiclesFleet telematics and last-mile delivery optimization driving adoption
Heavy Commercial VehiclesTachograph integration and long-haul fleet compliance generating demand


Passenger cars dominate by volume, reflecting the broad rollout of L2+ ADAS across all price segments. Heavy commercial vehicles represent a high-value niche where logging supports regulatory tachograph compliance and predictive maintenance.

By Propulsion

Sub-SegmentKey Trend
ICE VehiclesLargest installed base; emissions-diagnostic logging sustains demand
Battery Electric VehiclesBattery-management-system data logging creating new functional requirements
Hybrid Electric VehiclesDual-powertrain complexity increasing logging channel count


ICE vehicles maintain the largest share due to their dominant global fleet composition. Battery electric vehicles are the fastest-growing propulsion segment as OEMs integrate battery-health logging alongside traditional ADAS and chassis recording.


 

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.