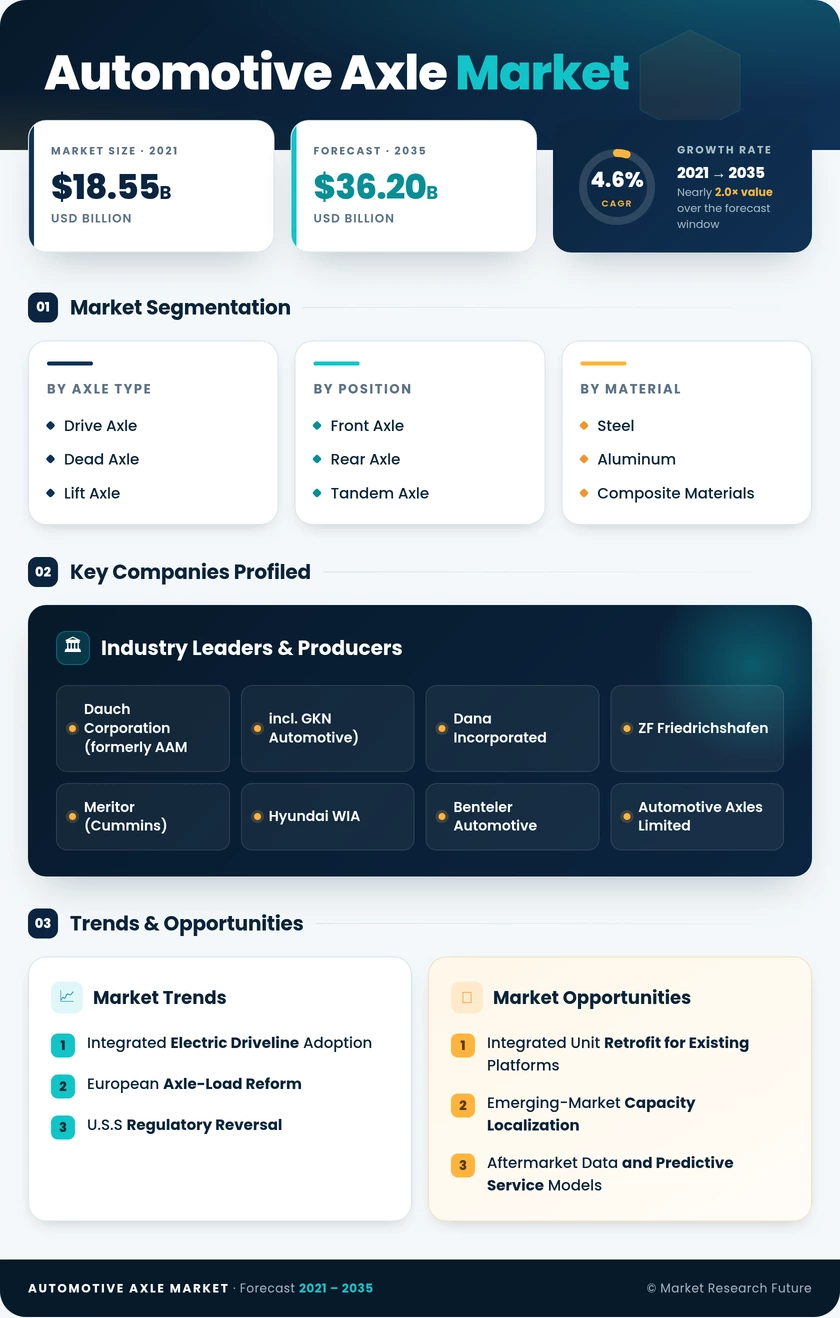
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| Axle Type | Drive Axle, Dead Axle, Lift Axle | Drive Axle | Lift Axle |
| Position | Front Axle, Rear Axle, Tandem Axle | Rear Axle | Tandem Axle |
| Material | Steel, Aluminum, Composite Materials | Steel | Composite Materials |
| Vehicle Type | Passenger Cars, Commercial Vehicles | Passenger Cars | Commercial Vehicles |
| Propulsion Type | ICE, Hybrid, Battery Electric | ICE | Battery Electric |
| Sales Channel | OEM, Aftermarket | OEM | Aftermarket |
| Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific | Middle East & Africa |
Market Segmentation Overview
By Axle Type
| Sub-Segment | Key Trend |
| Drive Axle | Electrification substitutes within the category; e-Beam units preserve share while changing content mix. |
| Dead Axle | Stable demand tied to trailer and load-bearing applications; limited technology disruption |
| Lift Axle | Fastest growth as vocational fleets pursue payload flexibility under revised weight rules. |
Axle type is the dimension where electrification is least visible in the share data and most visible in the engineering. A drive axle remains a drive axle whether it houses a differential or a motor, which is why the category holds position while its bill of materials transforms underneath.
By Position
| Sub-Segment | Key Trend |
| Front Axle | Steering integration complexity rising with all-wheel-drive electric platforms. |
| Rear Axle | Highest content value; primary location for integrated motor packaging |
| Tandem Axle | Specification decisions increasingly shaped by European six-axle weight differentiation. |
Rear positions carry the most value because they house the torque-generating hardware in both conventional and electric layouts. Tandem configurations are moving from engineering default to active commercial choice as regulators tie weight allowances to axle count.
By Material
| Sub-Segment | Key Trend |
| Steel | Retains dominance on cost and established forging supply base |
| Aluminum | Growth tied to unsprung mass reduction in premium passenger platforms |
| Composite Materials | Payload recovery against battery mass drives adoption; tooling cost is the gate. |
By Vehicle Type
| Sub-Segment | Key Trend |
| Passenger Cars | SUV and crossover mix sustains content-per-vehicle above sedan-era levels |
| Commercial Vehicles | Duty-cycle economics reward driveline efficiency more directly than retail purchase does |
Commercial buyers evaluate an axle as a total-cost line item, which makes them more willing to pay for efficiency than retail purchasers who never see the component priced separately.
By Propulsion Type
| Sub-Segment | Key Trend |
| ICE | Installed platform base sustains volume well past the electrification inflection. |
| Hybrid | Transitional architectures require dual-capability axle families. |
| Battery Electric | Integrated motor-inverter-gearing units reshape supplier capability requirements. |
Propulsion is the dimension that determines which suppliers survive the decade. Integrated units demand competencies — inverter integration, thermal management, NVH validation for motor whine — that forging-heritage producers must acquire or partner for.
By Sales Channel
| Sub-Segment | Key Trend |
| OEM | Program awards increasingly favour suppliers quoting across all propulsion types. |
| Aftermarket | Expanding global vehicle parc sustains growth independent of new-vehicle cycles. |
Aftermarket demand decouples from new-vehicle sales because the installed base keeps growing even in plateauing markets. Axle ratio gear differential replacement, bearing service and half-shaft renewal generate steady volume across a parc that ages rather than shrinks.
By Geography
| Sub-Segment | Key Trend |
| North America | Federal GHG repeal shifts evaluation from compliance to total cost of ownership. |
| Europe | Weights and Dimensions revision directly shapes axle rating specifications. |
| Asia-Pacific | Volume assembly plus export machining base; integration capability developed on Chinese timelines |
| South America | Deep aftermarket pool relative to OEM fitment; longer replacement cycles |
| Middle East & Africa | Greenfield capacity additions serve as hedge against chokepoint concentration. |
Regional divergence is the defining feature of the forecast period. Europe legislates toward zero-emission configurations while North America removes its federal framework entirely, forcing global suppliers to maintain dual specification families through at least 2030.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA