Assisted Reproductive Technology Market (2026 - 2035)

Assisted Reproductive Technology Market Research Report: Size, Share, Trend Analysis By Procedure Type (In Vitro Fertilization, Intracytoplasmic Sperm Injection, Frozen Embryo Transfer, Egg Donation, Sperm Donation), By End Users (Fertility Clinics, Hospitals, Home Care), By Technology (Cryopreservation, Preimplantation Genetic Diagnosis, Assisted Hatching), By Product Type (Reagents, Consumables, Equipment) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2025 To 2035
ID: MRFR/HC/4898-HCR 200 Pages Rahul Gotadki, Vikita Thakur Last Updated: September 15, 2026
Assisted Reproductive Technology Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.4%
2025 Market SizeUSD 32.60 Billion
2035 Market SizeUSD 73.04 Billion
Key Players
CooperSurgical
Vitrolife Group
Merck KGaA
Ferring Pharmaceuticals
Thermo Fisher Scientific
Kitazato Corporation
Opportunities
  • Fertility Preservation as a Standalone Franchise
  • Reimbursement Whitespace Across Emerging Asia and Latin America
  • AI-Assisted Selection and Outcome Data Monetisation

Assisted Reproductive Technology Market Summary

The Assisted Reproductive Technology (ART) Market closed 2025 at USD 32.60 billion and is projected to grow to USD 73.04 billion by 2035, expanding at a compound annual growth rate (CAGR) of 8.4% between 2026 and 2035. Market value is expected to reach USD 35.34 billion in 2026 as the first year of the forecast period. This growth is being driven primarily by expanding public insurance reimbursement in China and a global reframing of infertility as essential rather than elective care, alongside a broader clinical shift toward higher-efficiency embryo culture and selection technologies.

China's National Healthcare Security Administration extended provincial insurance reimbursement to 17 assisted conception items beginning in Beijing in July 2023, a policy that has since been replicated across more than 20 provinces. This reimbursement expansion has significantly widened patient access to fertility treatment across China. In parallel, the World Health Organization's (WHO) 2023 estimate that roughly one in six adults experiences infertility at some point reframed the category from elective to essential care, strengthening the case for insurance coverage and public health investment worldwide.

Clinical practice is also reshaping where revenue is generated within the ART Market. Vitrification, blastocyst culture, and elective freeze-all cycles have largely replaced slow-freeze protocols and fresh-transfer-first approaches. At the same time, time-lapse incubators and AI-scored morphokinetics have replaced manual embryo grading. Merck KGaA and Ferring have jointly committed more than USD 400 million to fertility research and development and manufacturing capacity between 2023 and 2025.

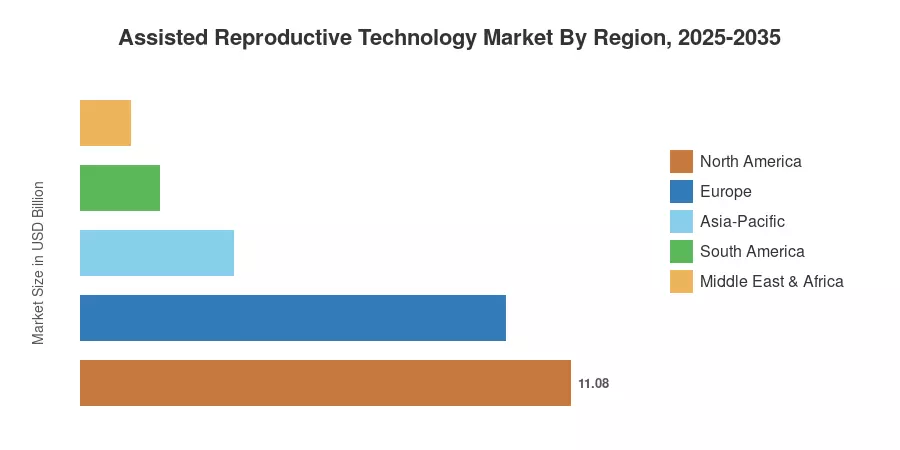
By region, North America holds the largest share of the ART Market, at 34.0% of revenue, backed by growth in employer-sponsored fertility benefits. Asia-Pacific is the fastest-growing region, with a projected CAGR of 10.6%, driven by expanding state reimbursement. Europe holds the second-largest share, at 29.5%, with Spain's donor framework supporting the region's highest cross-border patient caseload. Over the next decade, market leadership is expected to belong to whoever succeeds in industrializing laboratory-scale embryo processing.


Key Report Takeaways

• By Technology

  • In-Vitro Fertilization, including ICSI, commands a 62.4% revenue share of the Assisted Reproductive Technology Market in 2025
  • Cryopreservation and gamete banking are the fastest-expanding technology line at 11.2% CAGR through 2035
  • Frozen embryo replacement cycles generated USD 6.85 billion in 2025

• By Sector

  • Dedicated fertility clinics account for 58.6% of end-user revenue
  • Hospital and surgical-centre channels contributed USD 8.32 billion in 2025
  • Cryobanks post the steepest end-user growth at 12.3% CAGR

• By Geography

  • North America leads the Assisted Reproductive Technology Market with a 34.0% share.
  • Asia-Pacific advances at 10.6% CAGR, the fastest of any region
  • Middle East & Africa reached USD 1.14 billion in 2025


Market Size and Forecast (2021–2035)

Sizing clinic-level cycle volumes from national registries. Vendor revenue triangulation across capital equipment & consumables. Payer reimbursement data: historical years reconcile to cycle volume counts in the registry data of the CDC, HFEA, ESHRE and ANZARD. Forecast years apply cycle-volume increase against blended per-cycle realization in the Assisted Reproductive Technology Market [1][2][3][7].
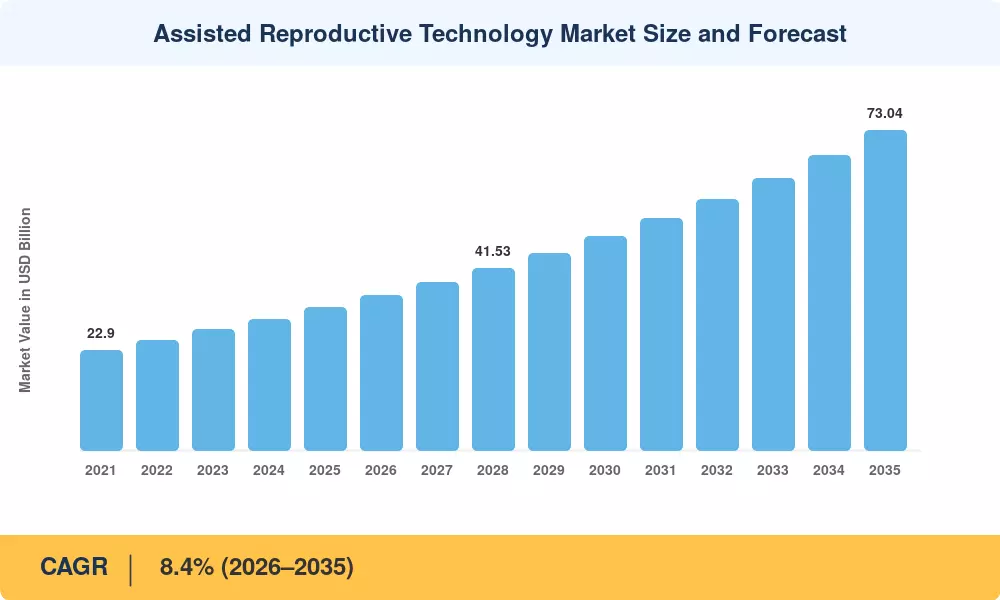
Assisted Reproductive Technology Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising infertility prevalence and delayed parenthood 1.9 Global Long-term (≥4 yr)
Employer benefits and insurance coverage mandates 1.5 North America, Europe Medium-term (2–4 yr)
State reimbursement rollouts in Asia 1.2 Asia-Pacific Medium-term (2–4 yr)
Vitrification and freeze-all protocol adoption 1.1 Global Medium-term (2–4 yr)
Clinic network consolidation and private capital 1.0 North America, Europe Short-term (≤2 yr)
AI embryo assessment and lab automation 0.8 North America, Europe Long-term (≥4 yr)
Cross-border reproductive care flows 0.6 Europe, Middle East Short-term (≤2 yr)


Demographic Pressure Is the Base Load

Age at first birth keeps climbing across OECD economies, and biology has not adjusted. OECD data place mean maternal age at first birth above 29 years in most member states, with Italy, Spain and Korea exceeding 31 [19]. The WHO's 2023 synthesis put lifetime infertility prevalence near 17.5%, with little variation between high- and low-income settings [4]. Demand is therefore structural rather than cyclical.

Coverage Turns Demand Into Cycles

Payer economics decide whether intent becomes a booked cycle. Kaiser Family Foundation's 2024 employer survey found that 47% of US firms with 200 or more workers cover in-vitro fertilization, up sharply from 2020 [25]. Israel's state-funded model, covering treatment to two live births, sustains the world's highest per-capita cycle rate [21]. Coverage design, not clinical capability, is the binding constraint in most geographies.

The Laboratory Becomes the Product

Vitrification survival rates above 95% made freeze-all viable, and freeze-all made single-embryo transfer defensible. HFEA reported that frozen cycles overtook fresh cycles in the UK during 2022 [3]. Vitrolife and CooperSurgical have both repositioned around media, time-lapse systems and electronic witnessing rather than one-off capital sales [10][11]. Consumables now travel with every cycle, which is why laboratory spend compounds faster than clinic count.

Capital Reshapes Clinic Networks

Private equity and strategic buyers have consolidated fragmented single-site practices into multi-country platforms. Nordic Capital's acquisition of Care Fertility in 2023 and KKR's ownership of IVIRMA Global illustrate the scale ambition [24]. Consolidated groups negotiate better consumable pricing, standardise protocols and publish comparable outcome data, which in turn accelerates payer contracting.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High out-of-pocket cost per cycle -1.4 Global Long-term (≥4 yr)
Fragmented donor, surrogacy and consent law -0.9 Global Medium-term (2–4 yr)
Embryologist and clinical specialist shortage -0.8 Global Long-term (≥4 yr)
Ethical, religious and legal contestation -0.6 North America, MEA Short-term (≤2 yr)
Outcome variability and cumulative-success scrutiny -0.5 Europe, North America Medium-term (2–4 yr)


Price Still Gates Access

A single US cycle typically runs USD 15,000–25,000 including medication, and most patients need more than one. CDC surveillance shows live-birth rates per intended retrieval falling below 30% for patients aged 38–40 [1]. Where employer coverage is absent, conversion from consultation to treatment collapses, which is why penetration in the Assisted Reproductive Technology Market remains under 5% of clinically infertile couples in most countries.

Legal Whiplash Chills Investment

Alabama's February 2024 Supreme Court ruling treating cryopreserved embryos as children paused services at several clinics until the legislature passed immunity legislation weeks later [17]. India's Assisted Reproductive Technology (Regulation) Act and its 2023 rules tightened donor compensation, age limits and registry obligations, forcing smaller clinics to exit [5]. Legal discontinuity raises the cost of capital for multi-state operators.

Talent, Not Equipment, Is Scarce

Embryology training pipelines have not scaled with cycle volume. ESHRE has flagged persistent shortages of certified senior embryologists across several European systems, with recruitment cycles measured in quarters [2]. Automation helps at the margin, but witnessing, biopsy and vitrification remain manually intensive, capping how quickly any network can add throughput.


Assisted Reproductive Technology Market Opportunities

Fertility Preservation as a Standalone Franchise

Oncofertility referrals and elective preservation have decoupled from infertility treatment altogether. Egg freezing technology now anchors employer benefit tiers in the US and is increasingly bundled into private insurance in Japan and Singapore. Preservation converts a one-time procedure into a decade of storage revenue, and cryobanks already grow faster than any other end-user channel.

Reimbursement Whitespace Across Emerging Asia and Latin America

India, Indonesia, Vietnam and Brazil combine large affected populations with negligible public funding. Brazil's public network performs only a fraction of national demand, leaving private clinics to serve middle-income patients at price points well below Western norms. Operators that engineer a sub-USD 3,000 cycle will define the next volume tier.

AI-Assisted Selection and Outcome Data Monetisation

Time-lapse imaging generates millions of annotated embryo images per large network. Groups that pool this data can license predictive models, benchmark clinics and sell outcome analytics back to payers — a business model closer to software than to medical devices. Regulatory clarity on clinical decision-support classification will determine how fast this monetises.

Cross-Border Care Corridors

Spain, Czechia, Greece and the UAE have built donor-programme reputations that draw patients from restrictive jurisdictions. Gulf states are investing in accredited centres to retain outbound spend and attract regional inflows, a meaningful share gain opportunity within the Assisted Reproductive Technology Market.

Male-Factor and At-Home Diagnostics

Male factor contributes to roughly half of cases yet receives a fraction of diagnostic spend. Home semen analysis, sperm-selection microfluidics and andrology-focused clinic services represent an under-built adjacency that pulls patients into the funnel earlier.


Assisted Reproductive Technology Market Future Outlook

Algorithmic Embryology Becomes Routine

By 2030, most high-volume laboratories will run continuous-culture time-lapse systems with algorithmic ranking as a first-pass triage. Vendors already position deep-learning scoring as decision support rather than diagnosis, keeping regulatory exposure manageable under EU IVDR classification [16]. Expect outcome benchmarking to become a competitive weapon in the Assisted Reproductive Technology Market, with networks publishing cumulative live-birth rates per retrieval rather than per transfer.

Platform Economics Reach the Clinic

Consolidated groups will increasingly monetise the layer above the clinic: scheduling, financing, pharmacy, storage and benefits administration. Progyny's model demonstrates that intermediation can capture margin without owning laboratories [14]. Smaller independents will either join a platform or specialise.

Storage Liability Becomes a Balance-Sheet Item

Cryostorage inventories compound with every freeze-all cycle. Networks now hold millions of stored gametes and embryos, creating multi-decade custodial obligations, consent-renewal burdens and tank-monitoring capital requirements. Insurers have begun pricing this exposure separately, and regulators in the UK have already extended statutory storage limits to 55 years [18].

Equity and Access Enter the Scorecard

Public funders increasingly tie support to access metrics rather than volume. The WHO's inclusion of infertility care within universal health coverage discourse signals a decade in which the Assisted Reproductive Technology Market is judged on who gets treated, not only on how many cycles are sold [4]. Affordability engineering will separate winners from incumbents.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 34.0% share Employer benefits, network roll-ups, lab automation
Europe USD 9.62 Billion Cross-border donor programmes, single-embryo transfer
Asia-Pacific 10.6% CAGR State reimbursement, capacity build-out
South America 5.5% share Private-pay affordability models
Middle East & Africa USD 1.14 Billion Accredited centre build-out, medical tourism
Total USD 32.60 Billion —

Regional performance in the Assisted Reproductive Technology Market tracks payer policy far more closely than it tracks disease burden.


North America

Country Metric Key Driver
United States 86.5% share of region Employer coverage expansion [25]
Canada 8.1% CAGR Provincial funding in Ontario and Quebec [19]
Mexico USD 0.42 Billion Cross-border patient inflow [22]


Employer benefits carry the region. Coverage among large US employers has widened steadily, and specialised benefit managers such as Progyny now sit between payers and clinic networks, steering volume toward contracted centres of excellence [14]. The Assisted Reproductive Technology Market in the United States remains the highest-realisation geography globally, though legal uncertainty at state level introduces episodic disruption [17].

Europe

Country Metric Key Driver
Spain 19.4% share of region Donor gamete framework, inbound patients [2]
United Kingdom USD 1.71 Billion Frozen-cycle shift, private-pay growth [3]
Germany 7.4% CAGR Statutory co-funding reform [2]
France 13.6% share of region Extended eligibility since 2021 [22]
Italy USD 0.88 Billion Public-sector cycle funding [2]
Rest of Europe 8.0% CAGR Nordic and CEE capacity growth [2]


Regulatory divergence defines Europe. Spain's permissive donor rules and Czechia's price positioning have created durable inbound corridors. At the same time, France's 2021 extension of funded treatment to single women and same-sex couples produced a step change in registry volumes [22]. Single-embryo transfer is now standard practice across most Nordic systems, lifting per-patient cycle counts even as multiple-birth rates fall [2].

Asia-Pacific

Country Metric Key Driver
China 41.2% share of region Provincial insurance inclusion
India 12.8% CAGR Regulated clinic formalisation [5]
Japan USD 1.78 Billion National insurance coverage since 2022
Australia 9.2% share of region Medicare rebates, listed clinic groups [7][23]
South Korea 9.7% CAGR Municipal subsidy programmes [19]
Rest of Asia-Pacific USD 0.71 Billion Southeast Asian capacity expansion [19]


Policy did the heavy lifting here. Japan's April 2022 decision to bring standard treatment under national health insurance immediately expanded the eligible population, and China's provincial reimbursement rollout has done the same at far greater scale . Growth in the Assisted Reproductive Technology Market across Asia-Pacific is therefore capacity-constrained rather than demand-constrained, which favours equipment vendors and turnkey laboratory builders.

South America

Country Metric Key Driver
Brazil 58.3% share of region Private clinic network scale [19]
Argentina USD 0.31 Billion Mandatory coverage law [19]
Rest of South America 9.4% CAGR Colombia and Chile expansion [19]


Argentina's national law mandating coverage remains the region's most progressive framework, though inflation has eroded real reimbursement. Brazil's market runs almost entirely on private payment, with clinics competing on package pricing and success-rate transparency.

Middle East & Africa

Country Metric Key Driver
United Arab Emirates 27.6% share of region Medical tourism, mandatory insurance [22]
Saudi Arabia 11.8% CAGR Vision 2030 healthcare investment [19]
Israel USD 0.24 Billion State-funded treatment to two live births [21]
South Africa 8.4% share of region Regional referral hub status [19]
Rest of MEA USD 0.19 Billion Nascent private capacity [19]


Gulf investment is the story. Sovereign-backed hospital groups are building accredited laboratories to capture spend that previously left the region. At the same time, Israel's fully funded model continues to produce the highest cycles-per-capita figure worldwide [21].


Assisted Reproductive Technology Market By Region, 2025-2035

Assisted Reproductive Technology Market Segmentation

Segment structure in the Assisted Reproductive Technology Market reflects a decisive shift from fresh, donor-light cycles toward frozen, preservation-heavy workflows.

By Technology

Segment Metric (2025) Primary Demand Driver
In-Vitro Fertilization (incl. ICSI) 62.4% share Male-factor and unexplained infertility volume
Frozen Embryo Replacement USD 6.85 Billion Freeze-all protocol adoption
Artificial Insemination (IUI) 9.4% share First-line, low-cost pathway
Cryopreservation & Gamete Banking 11.2% CAGR Elective and oncofertility preservation
Others (PGT, GIFT/ZIFT, retrieval) 3.1% share Genetic screening uptake


In-vitro fertilization anchors the Assisted Reproductive Technology Market because it absorbs the highest-acuity caseload and carries the richest consumable basket — media, dishes, micromanipulation tools, incubator time and witnessing. Frozen embryo replacement is the structural share gainer: once vitrification survival exceeded 95%, clinics could separate stimulation from transfer, improving endometrial receptivity and reducing hyperstimulation risk [11]. That single protocol change converted a one-transfer cycle into a multi-transfer asset.

By Procedure Type

Segment Metric (2025) Primary Demand Driver
Fresh Non-Donor 44.8% share Standard first-cycle pathway
Frozen Non-Donor USD 11.15 Billion Freeze-all and sibling-transfer cycles
Fresh Donor 9.6% CAGR Advanced maternal age caseload
Frozen Donor 8.6% share Donor bank inventory availability


Fresh non-donor still leads the Assisted Reproductive Technology Market on volume, but its share erodes each year. Frozen non-donor procedures grow faster because every stimulated cycle now produces stored embryos that generate subsequent transfers without repeat retrieval — better for patients, and better for lifetime revenue per patient.

By End User

Segment Metric (2025) Primary Demand Driver
Fertility Clinics 58.6% share Specialised, high-throughput laboratories
Hospitals & Surgical Centres USD 8.32 Billion Integrated obstetrics and oncology referral
Cryobanks 12.3% CAGR Long-duration storage contracts
Research & Academic Institutes 4.7% share Protocol development and training


Standalone clinics dominate the Assisted Reproductive Technology Market because throughput drives laboratory quality, and quality drives referral. Cryobanks are the compounding line: storage revenue is annuity-like, churns slowly and requires little incremental clinical labour once tanks are commissioned.

By Offering

Segment Metric (2025) Primary Demand Driver
Reagents, Media & Consumables 41.5% share Per-cycle recurring consumption
Instruments & Equipment USD 9.16 Billion Incubator and micromanipulation refresh
Accessories & Disposables 9.8% CAGR Single-use safety requirements
Software, Witnessing & Data Systems 6.5% share Traceability and error-prevention mandates


Consumables outgrow capital equipment because they scale with cycles rather than with clinic count. Software remains small but strategically weighted — electronic witnessing is becoming a de facto accreditation expectation across European laboratories [16].


Competitive Benchmarking

Concentration is modest and divided. On the supply side, vendors are somewhat consolidated with an estimated HHI of around 950 and a top-five share of nearly 46% of product revenue; on the clinic side, services remain fragmented with the largest network accounting for less than 6% of global cycles. In the Assisted Reproductive Technology Market, the market segmentation leads to product manufacturers competing on installed-base lock-in and clinical evidence, and service operators competing on result transparency and payer contracts.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
CooperSurgical (Cooper Companies) ~11–14% Media, incubators, witnessing, genetic testing Broadest end-to-end laboratory portfolio [10]
Vitrolife Group ~9–12% Culture media, time-lapse systems, PGT Evidence-led premium lab standard [11]
Merck KGaA ~8–11% Gonadotropins, fertility hormone portfolio Pharma anchor with clinic decision-support tools [9]
Ferring Pharmaceuticals ~6–9% Stimulation and luteal support therapeutics Deep reproductive medicine specialisation [13]
Thermo Fisher Scientific ~4–6% Reagents, cryogenic storage, lab instrumentation Scale supplier with cross-lab reach [12]
Kitazato Corporation ~3–5% Vitrification kits and devices Category leader in cryopreservation protocols
Esco Medical ~2–4% Benchtop incubators, workstations Cost-efficient laboratory build-out partner
Hamilton Thorne ~2–3% Lasers, imaging, sperm analysis Precision micromanipulation niche
IVIRMA Global ~2–3% Clinic network, research programmes Largest multinational clinic platform
Monash IVF Group ~1–2% Clinic network, diagnostics Asia-Pacific listed operator [23]


Recent News & Developments

  • China National Healthcare Security Administration (July 2023): Beijing became the first municipality to reimburse 16 assisted conception procedures, triggering a nationwide provincial rollout that materially widened the funded patient pool .
  • Nordic Capital / Care Fertility (October 2023): Acquisition of one of Europe's largest clinic groups signalled continued private-capital appetite for multi-site fertility platforms [24].
  • Alabama Supreme Court (February 2024): A ruling classifying cryopreserved embryos as children suspended services at several clinics; state immunity legislation restored operations within three weeks [17].
  • Vitrolife Group (May 2024): Expanded its time-lapse and genetic testing portfolio integration, tightening the link between imaging data and embryo selection workflows [11].
  • CooperSurgical (September 2024): Broadened its electronic witnessing and traceability offering in response to European laboratory accreditation expectations [10].
  • Merck KGaA (March 2025): Announced additional fertility manufacturing and digital decision-support investment aimed at standardising stimulation protocols across networks [9].
  • Ferring Pharmaceuticals (June 2025): Extended reproductive medicine partnerships across Asia-Pacific to support reimbursed-cycle demand in Japan and China [13].
  • Monash IVF Group (August 2025): Reported cycle volume growth across Australian and Southeast Asian operations, reinforcing regional consolidation trends [23].


Assisted Reproductive Technology Market Report Scope

Parameter Detail
Market Scope Global assisted conception products, laboratory systems, consumables and clinical services
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 8.4% (2026–2035)
Market Size Checkpoints USD 32.60 Billion (2025); USD 35.34 Billion (2026); USD 73.04 Billion (2035)
Fastest Growing Segments Cryobanks (end user); Cryopreservation & gamete banking (technology); Asia-Pacific (region)
Companies Profiled CooperSurgical, Vitrolife, Merck KGaA, Ferring, Thermo Fisher, Kitazato, Esco Medical, Hamilton Thorne, IVIRMA Global, Monash IVF
Valuation Currency USD, constant 2025 prices

FAQs

What due diligence should an investor run before backing a clinic network in the Assisted Reproductive Technology Market?
Verify cumulative live-birth rate per intended retrieval, not per transfer — the latter flatters outcomes. Then audit cryostorage consent records and tank monitoring, since custodial liability is the most commonly under-reserved item [3].
How should a hospital procurement team evaluate incubator platforms?
Price the consumable stream over seven years, not the capital cost. Closed benchtop systems with proprietary media lock in recurring spend, so quantify switching cost before signing [11].
Does the Assisted Reproductive Technology Market face meaningful reimbursement clawback risk?
Yes, where funding is tied to outcome thresholds. Systems that fund by cycle rather than by result are increasingly reviewing performance-linked conditions, which can retroactively affect clinic revenue recognition [19].
What integration problems arise when networks merge laboratories?
Media brands, incubator settings and witnessing systems rarely match across sites, so outcome data becomes non-comparable. Harmonisation typically takes twelve to eighteen months before consolidated reporting is credible [2].
Which emerging use case is most underestimated in the Assisted Reproductive Technology Market?
Oncofertility referral pathways. Coordinated preservation before chemotherapy remains inconsistently offered, yet it creates long-duration storage relationships and strong institutional referral loyalty [4].
How do IVF embryo transfer decisions differ under single-embryo transfer mandates?
Clinics transfer one blastocyst and bank the remainder, which lowers multiple-birth complications and raises subsequent frozen cycle volume. Reported per-transfer success falls while cumulative success improves [3].
What regulatory nuance most often surprises new entrants?
Donor anonymity rules differ sharply by jurisdiction and are not portable. Gametes legally sourced in one country may be unusable in another, which constrains cross-border inventory strategies [18].      
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author Co-Author Profile Vikita Thakur LinkedIn Senior Research Analyst
She holds an experience of about 5+ years in market research and business consulting projects for sectors such as life sciences, medical devices, and healthcare IT. She possesses a robust background in data analysis, market estimation, competitive intelligence, pipeline analysis market trend identification, and consumer behavior insights. Her expertise lies in technical Sales support, client interaction and project management, designing and implementing market research studies, conducting competitive analysis, and synthesizing complex data into actionable recommendations that drive business growth.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical journals, clinical publications, and authoritative health organizations. Key sources included the US Food and Drug Administration (FDA) [Center for Devices and Radiological Health for embryology lab equipment, Center for Drug Evaluation and Research for fertility pharmaceuticals], European Medicines Agency (EMA) [Committee for Medicinal Products for Human Use fertility treatment guidelines], Human Fertilisation and Embryology Authority (HFEA) [UK ART statistics and clinic performance data], Centers for Disease Control and Prevention (CDC) [National ART Surveillance System success rates], World Health Organization (WHO) [Global infertility prevalence statistics], European Society of Human Reproduction and Embryology (ESHRE) [European IVF monitoring consortium data], American Society for Reproductive Medicine (ASRM), Society for Assisted Reproductive Technology (SART) [Clinic outcomes and practice guidelines], International Federation of Fertility Societies (IFFS), National Institutes of Health (NIH)/PubMed, Human Reproduction journal, Fertility and Sterility journal, China National Medical Products Administration (NMPA), Pharmaceuticals and Medical Devices Agency (PMDA) Japan, Therapeutic Goods Administration (TGA) Australia, and national health ministries from key markets [India ICMR, Brazil ANVISA, GCC health authorities]. These sources collected procedure statistics, regulatory approval data, clinical success rate studies, demographic infertility trends, and market landscape analysis for IVF, intracytoplasmic sperm injection (ICSI), intrauterine insemination (IUI), frozen embryo replacement, and gamete/embryo cryopreservation technologies.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. CEOs, VPs of R&D, regulatory affairs chiefs, and commercial directors from ART device manufacturers, fertility pharmaceutical companies, and IVF media suppliers comprised supply-side sources. The demand-side sources included procurement leads from fertility clinics, hospital reproductive medicine departments, and specialized ART facilities, as well as reproductive endocrinologists, IVF laboratory directors, fertility clinic medical directors, and cryobank operations managers. Primary research has confirmed the product pipeline timelines for AI-integrated embryo assessment systems, obtained insights on clinical adoption patterns, pricing strategies per IVF cycle, and reimbursement dynamics for fertility preservation, and validated market segmentation across fresh vs. frozen cycles, donor vs. non-donor procedures, and equipment categories.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and procedure volume analysis. The methodology included:

Identification of 50+ key manufacturers and service providers across North America, Europe, Asia-Pacific, Latin America, and Middle East

Product mapping across instruments & equipment [incubators, micromanipulators, cryosystems, time-lapse imaging], reagents & media [culture media, sperm processing], software & AI solutions [embryo selection algorithms, clinic management], and clinical services [IVF, ICSI, IUI, fertility preservation]

Analysis of reported and modeled annual revenues specific to ART portfolios, including IVF cycle volumes and average selling prices by country

Coverage of manufacturers and large clinic networks representing 70-75% of global market share in 2024

Extrapolation using bottom-up [procedure volume × ASP by country/region, segmented by fresh non-donor, frozen donor, fertility preservation cycles] and top-down [manufacturer revenue validation, service provider network analysis] approaches to derive segment-specific valuations for equipment, consumables, and clinical services

CDC National ART Surveillance System (US cycle statistics)

ESHRE European IVF Monitoring (EIM) Consortium

HFEA Annual Register (UK clinic data)

ASRM/SART National Summary Report

WHO Global Infertility Guidelines (2023)

FDA 510(k) Clearance Database [embryo culture media, time-lapse systems]

EMA Human Medicines Database [fertility drug approvals]

National reimbursement databases [NHS, CMS, Japanese Ministry of Health]

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















