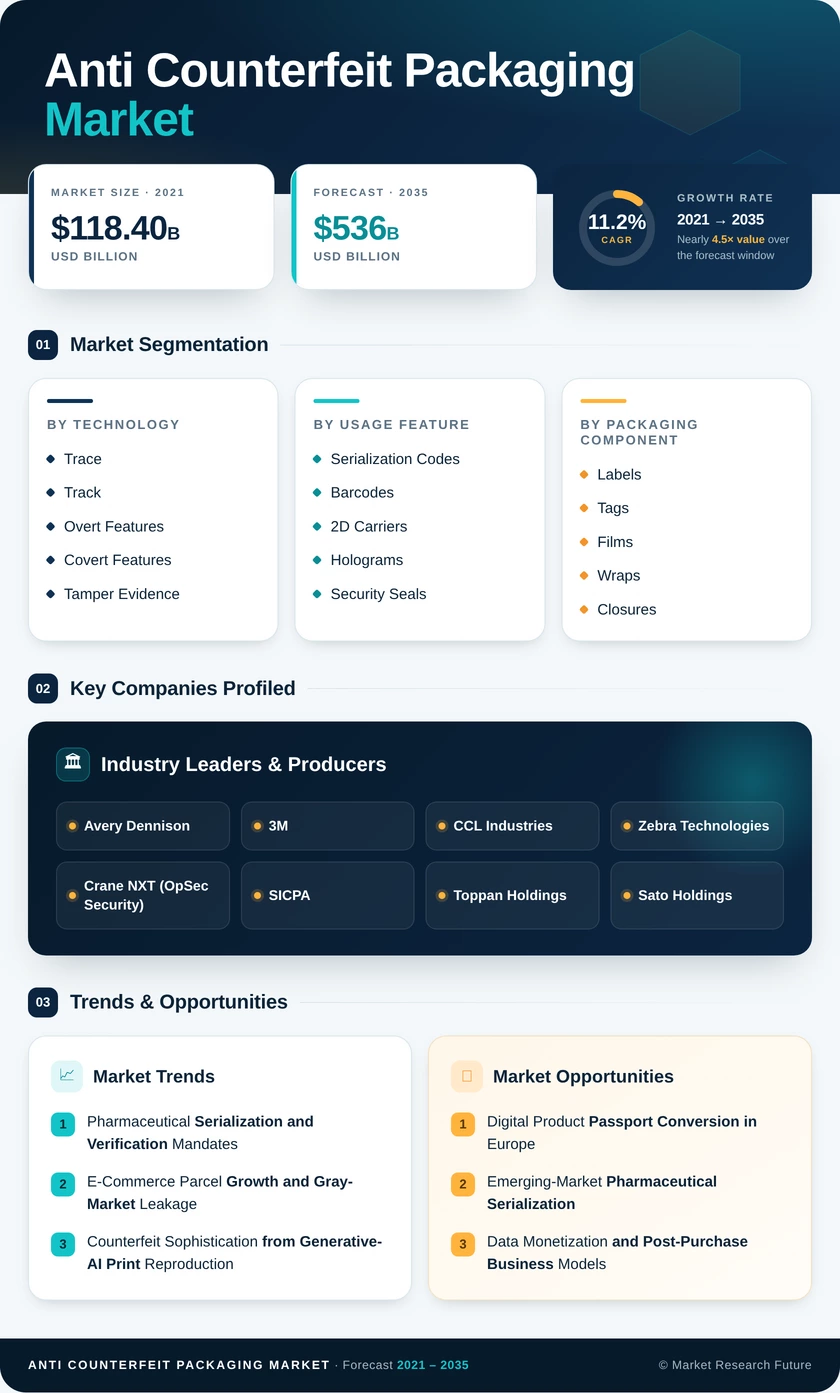
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Technology | Trace and Track; Overt Features; Covert Features; Tamper Evidence; Forensic Markers | Trace and Track | Forensic Markers |
| By Usage Feature | Serialization Codes; Barcodes and 2D Carriers; Holograms; Security Seals; RFID and NFC Tags | Serialization Codes | RFID and NFC Tags |
| By Packaging Component | Labels and Tags; Films and Wraps; Closures and Seals; Cartons and Boxes; Security Inks and Coatings | Labels and Tags | Security Inks and Coatings |
| By Packaging Format | Bottles; Flexible Packs; Blisters and Clamshells; Cartons; Cans | Bottles | Flexible Packs |
| By End-User Sector | Healthcare and Pharmaceuticals; Food and Beverage; Consumer Electronics; Apparel and Luxury Goods; Automotive Components; Others | Healthcare and Pharmaceuticals | Consumer Electronics |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Technology
| Sub-Segment | Key Trend |
| Trace and Track | Serialization repositories shift from compliance archives to operational analytics platforms |
| Overt Features | Refresh cycles shorten as reproduction quality improves, pushing devices toward layered designs |
| Covert Features | Nano-pigment and spectral taggants displace single-mechanism inks in regulated categories |
| Tamper Evidence | Reverse-logistics and returns fraud extend demand beyond regulated distribution |
| Forensic Markers | Laboratory-verifiable chemistry expands into automotive and semiconductor aftermarkets |
Technology mix is migrating from what a shopper can see toward what a machine can verify. Trace and Track retains the largest revenue base because statutory obligations renew annually, but incremental budget increasingly funds covert and forensic layers that survive replication attempts. Vendors that pair chemistry with detection software capture disproportionate value.
By Usage Feature
| Sub-Segment | Key Trend |
| Serialization Codes | Statutory unique identifiers become the default carrier across regulated sectors |
| Barcodes and 2D Carriers | Retail transition to data-rich two-dimensional carriers accelerates ahead of 2027 |
| Holograms | Value shifts from deterrence alone to hybrid designs combining visible and covert layers |
| Security Seals | Specification extends from primary packs to e-commerce shipper cartons |
| RFID and NFC Tags | Inlay cost decline unlocks item-level deployment beyond apparel into food and logistics |
Feature selection increasingly follows the scanning infrastructure already present at point of sale or intake. Serialization Codes dominate where regulators dictate the format, while RFID and NFC Tags win where inventory accuracy and authentication share one business case. Convergence of the two is the defining commercial trend of the forecast window.
By Packaging Component
| Sub-Segment | Key Trend |
| Labels and Tags | Remain the default retrofit carrier for new mandates across every format |
| Films and Wraps | Bundle integrity requirements grow with multipack e-commerce fulfilment |
| Closures and Seals | First-opening indication becomes standard specification in liquids and pharmaceuticals |
| Cartons and Boxes | Aggregation hierarchy printing expands with case and pallet-level reporting |
| Security Inks and Coatings | Fastest-growing component as covert chemistry attracts incremental budget |
Component choice is driven largely by how quickly a solution can be deployed onto existing lines. Labels and Tags lead because they require no tooling redesign, whereas Security Inks and Coatings grow fastest as brand owners accept ink-system qualification in exchange for features that resist replication.
By Packaging Format
| Sub-Segment | Key Trend |
| Bottles | Neck bands and induction seals remain standard across pharmaceuticals and spirits |
| Flexible Packs | E-commerce fulfilment merges the shipping pack with the saleable unit |
| Blisters and Clamshells | Unit-dose formats support serialization and tamper indication without added components |
| Cartons | Serve as the aggregation layer linking item, case, and pallet identity |
| Cans | Excise verification and beverage authenticity drive selective adoption |
Format demand follows where the counterfeit risk physically materializes. Bottles retain leadership on volume in regulated liquids, while Flexible Packs grow fastest because direct-to-consumer shipping exposes the primary pack to the full length of the fulfilment chain rather than to controlled retail distribution.
By End-User Sector
| Sub-Segment | Key Trend |
| Healthcare and Pharmaceuticals | Serialization statutes create recurring, non-discretionary spend |
| Food and Beverage | Origin labelling and recall traceability rules widen the addressable base |
| Consumer Electronics | Accessory and battery counterfeiting drives the fastest sector growth |
| Apparel and Luxury Goods | Resale authentication creates demand extending past first sale |
| Automotive Components | Aftermarket parts safety and warranty exposure justify forensic verification |
| Others | Agrochemicals, cosmetics, and industrial consumables adopt selectively |
Sector adoption correlates with the consequence of failure rather than the value of the goods. Healthcare and Pharmaceuticals lead because falsified medicines carry patient-safety liability, while Consumer Electronics accelerates fastest as counterfeit power components generate recalls and reputational damage far exceeding their retail price.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA