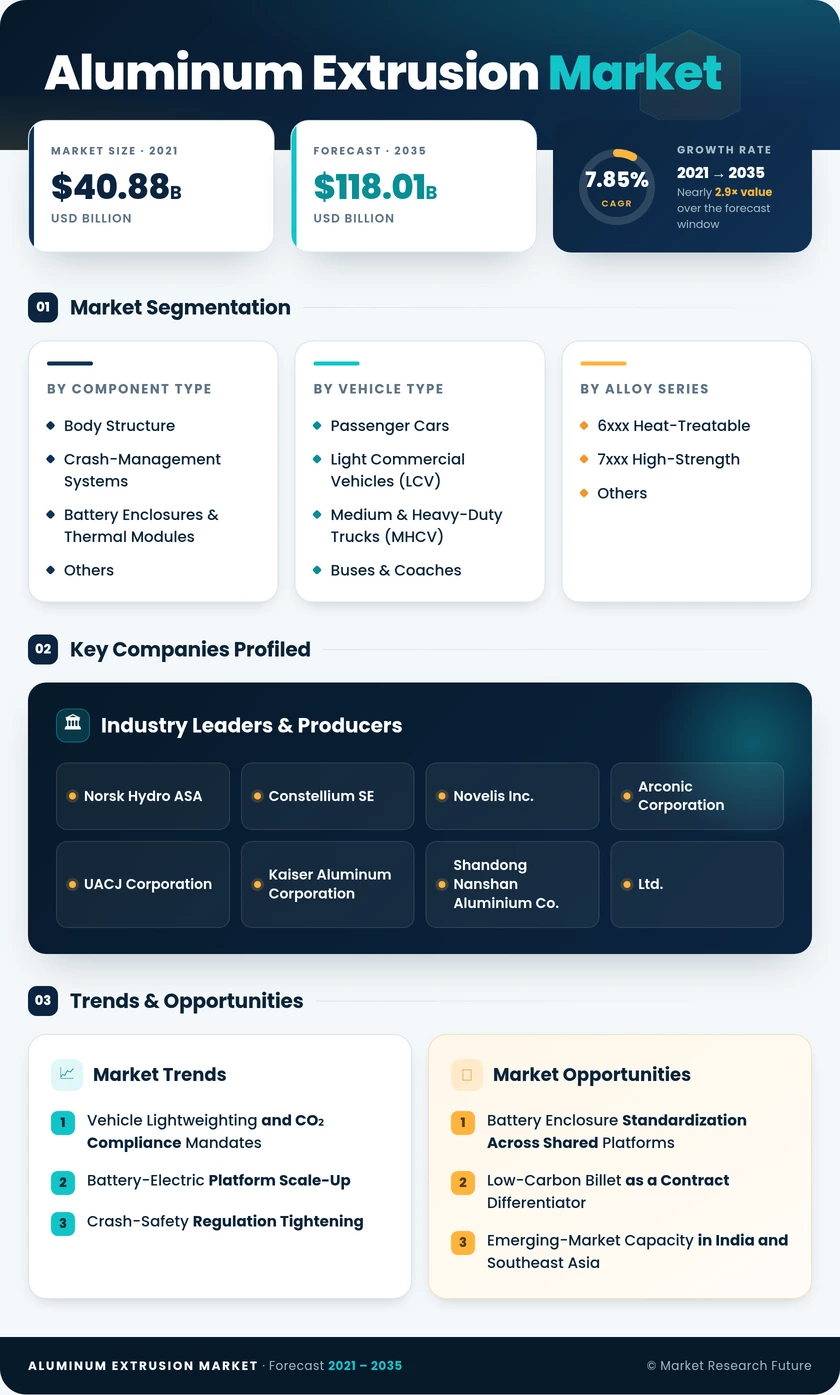
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Component Type | Body Structure; Crash-Management Systems; Battery Enclosures & Thermal Modules; Others | Body Structure (35.56% share, 2025) | Battery Enclosures & Thermal Modules (9.28% CAGR, 2026–2035) |
| By Vehicle Type | Passenger Cars; Light Commercial Vehicles (LCV); Medium & Heavy-Duty Trucks (MHCV); Buses & Coaches | Passenger Cars (49.24% share, 2025) | Passenger Cars (9.29% CAGR, 2026–2035) |
| By Alloy Series | 6xxx Heat-Treatable; 7xxx High-Strength; Others | 6xxx Heat-Treatable (59.57% share, 2025) | 7xxx High-Strength (9.35% CAGR, 2026–2035) |
| By Press Capacity | Less than or equal to 15 MN; 16 to 25 MN; 26 to 35 MN; More than 35 MN | 16 to 25 MN (35.54% share, 2025) | More than 35 MN (9.33% CAGR, 2026–2035) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific (37.52% share) | Asia-Pacific (9.32% CAGR) |
Market Segmentation Overview
By Component Type
| Sub-Segment | Key Trend |
|---|---|
| Body Structure | Multi-material body-in-white designs replace welded steel rails with hollow sections |
| Crash-Management Systems | Multi-cell crash boxes tuned to updated side and far-side impact protocols |
| Battery Enclosures & Thermal Modules | Cell-to-pack layouts drive sealed perimeter frames with integrated cooling channels |
| Others | Roof systems, seat frames and powertrain mounts adopt lighter sections incrementally |
Body Structure leads this dimension on substitution economics: rocker and longitudinal rail sections convert cleanly from steel at 35–40% lower mass with equivalent crash performance, so OEMs specify them first on every new architecture. Battery Enclosures & Thermal Modules grow fastest because the content is additive rather than substitutional — a combustion platform has no equivalent part — and corrosion resistance plus dimensional stability make extruded perimeters the default choice for sealed packs. Crash-Management Systems track regulation rather than vehicle volume, which keeps their value resilient even in flat build years.
By Vehicle Type
| Sub-Segment | Key Trend |
|---|---|
| Passenger Cars | Platform scale spreads die and press tooling cost across high unit volumes |
| Light Commercial Vehicles (LCV) | Extruded roof bows and floor rails offset battery mass to protect payload |
| Medium & Heavy-Duty Trucks (MHCV) | Day-cab structures adopted selectively; frame rails remain steel for torsion |
| Buses & Coaches | Already alloy-intensive; incremental gains come from higher recycled content |
Passenger Cars both dominate and grow fastest here, a combination that reflects how tightly battery-electric penetration and platform volume reinforce one another — tooling amortized over a million units makes extruded structures cheaper per vehicle than on any other body style. Light Commercial Vehicles sit second and are the more cost-sensitive buyer, adopting sections only where payload recovery pays back directly. Medium & Heavy-Duty Trucks remain the slowest mover because operators discount up-front capital against long duty cycles and frame torsional requirements still favour steel.
By Alloy Series
| Sub-Segment | Key Trend |
|---|---|
| 6xxx Heat-Treatable | Workhorse grades balancing extrudability, corrosion resistance and post-age strength |
| 7xxx High-Strength | Thin-wall load paths in performance chassis and battery-protection frames |
| Others | 5xxx and specialty grades serving thermal, formed and non-structural applications |
6xxx Heat-Treatable grades hold the commanding position because they run at commercially viable press speeds through complex hollow dies and still reach structural properties after ageing — the combination no competing family matches at volume. 7xxx High-Strength grades expand fastest as crash rules tighten and designers need more strength in less section, particularly around battery intrusion zones. Their constraint is metallurgical rather than commercial: slower extrusion speeds and stress-corrosion sensitivity confine them to high-load nodes instead of whole body structures.
By Press Capacity
| Sub-Segment | Key Trend |
|---|---|
| Less than or equal to 15 MN | High-throughput small sections, brackets and thermal tubing |
| 16 to 25 MN | Versatile medium-to-large profiles across body, trim and powertrain parts |
| 26 to 35 MN | Wide body-side and sill sections for mid-size and full-size platforms |
| More than 35 MN | Single-piece battery housings and heavy-duty structural sections |
The 16 to 25 MN band leads because it covers the section sizes most current platforms specify while keeping conversion cost per kilogram competitive, making it the practical default for Tier-1 suppliers. Presses rated More than 35 MN grow fastest for a purely physical reason: wide single-piece battery trays and thick-wall heavy-duty sections cannot be produced below that tonnage, and only a limited number of such frames exist globally. That scarcity, combined with 30–40 month equipment lead times, means platform awards increasingly follow whoever committed capital first rather than whoever quotes lowest.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA