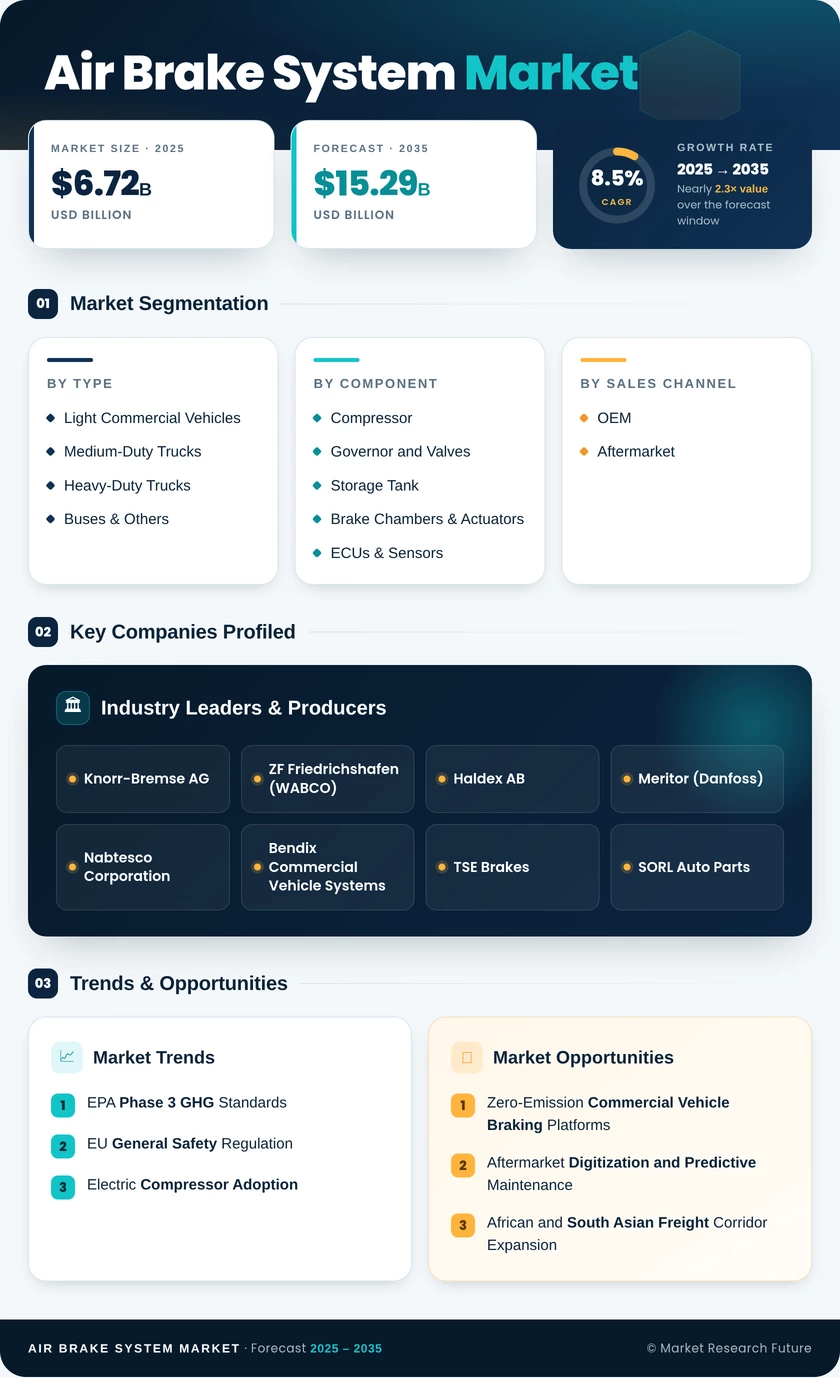
SEGMENTATION QUICK REFERENCE
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Brake Type | Drum Air Brake, Disc Air Brake, Hybrid Drum-Disc Systems, Electropneumatic Solutions | Drum Air Brake | Hybrid Drum-Disc Systems |
| By Vehicle Type | Light Commercial Vehicles, Medium-Duty Trucks, Heavy-Duty Trucks, Buses & Others | Light Commercial Vehicles | Heavy-Duty Trucks |
| By Component | Compressor, Governor and Valves, Storage Tank, Brake Chambers & Actuators, ECUs & Sensors | Compressor | ECUs & Sensors |
| By Sales Channel | OEM, Aftermarket | OEM | Aftermarket |
| By Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific | Africa |
MARKET SEGMENTATION OVERVIEW
By Brake Type
| Sub-Segment | Key Trend |
| Drum Air Brake | Sustained dominance in cost-sensitive markets; gradual share erosion to disc and hybrid configurations |
| Disc Air Brake | Regulatory-driven adoption on steer axles; growing OEM standardization in Europe and North America |
| Hybrid Drum-Disc Systems | Bridge architecture gaining mid-tier fleet traction; balances performance and lifecycle cost |
| Electropneumatic Solutions | Fastest technology-growth vector; essential for ADAS integration and ZEV brake-by-wire platforms |
Brake-type segmentation reflects a market in transition. Legacy drum architectures retain volume leadership through deep aftermarket ecosystems, while disc and electropneumatic platforms capture new-vehicle share as safety and emissions regulations tighten globally.
By Vehicle Type
| Sub-Segment | Key Trend |
| Light Commercial Vehicles | E-commerce-driven fleet expansion sustaining the broadest installed base |
| Medium-Duty Trucks | Urban distribution and vocational demand driving steady replacement cycles |
| Heavy-Duty Trucks | Highest content-per-vehicle growth driven by autonomous and ZEV platform investments |
| Buses & Others | Public-transit electrification programs boosting disc-brake and electronic-braking adoption |
Vehicle-type dynamics are shaped by the divergence between volume (LCV) and value (heavy-duty). Regulatory and technology investments concentrate on heavy-duty platforms, driving higher per-unit braking-system content even as LCVs dominate unit counts.
By Component
| Sub-Segment | Key Trend |
| Compressor | Transition from engine-driven to electric units supporting ZEV and fuel-cell powertrains |
| Governor and Valves | Increasing electronic integration for precision pressure management |
| Storage Tank | Lightweight composite materials displacing steel to reduce vehicle curb weight |
| Brake Chambers & Actuators | Spring brake chamber upgrades for higher-torque disc-brake applications |
| ECUs & Sensors | Fastest-growing component; essential for ADAS, AEB, and autonomous braking architectures |
Component segmentation highlights the shift in value from mechanical to electronic content. Compressors remain the largest single component category, but ECUs and sensors are growing at nearly double the market-average rate as electronic braking becomes standard.
By Sales Channel
| Sub-Segment | Key Trend |
| OEM | Platform redesigns for EPA Phase 3 and EU GSR compliance driving procurement volumes |
| Aftermarket | Aging fleet profiles and electronic retrofit demand accelerating channel growth |
Sales-channel dynamics reflect the tension between new-vehicle regulatory cycles (favoring OEM) and fleet aging trends (favoring aftermarket). The aftermarket's faster growth rate signals increasing maintenance complexity and electronic-component replacement frequency in the installed base.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA