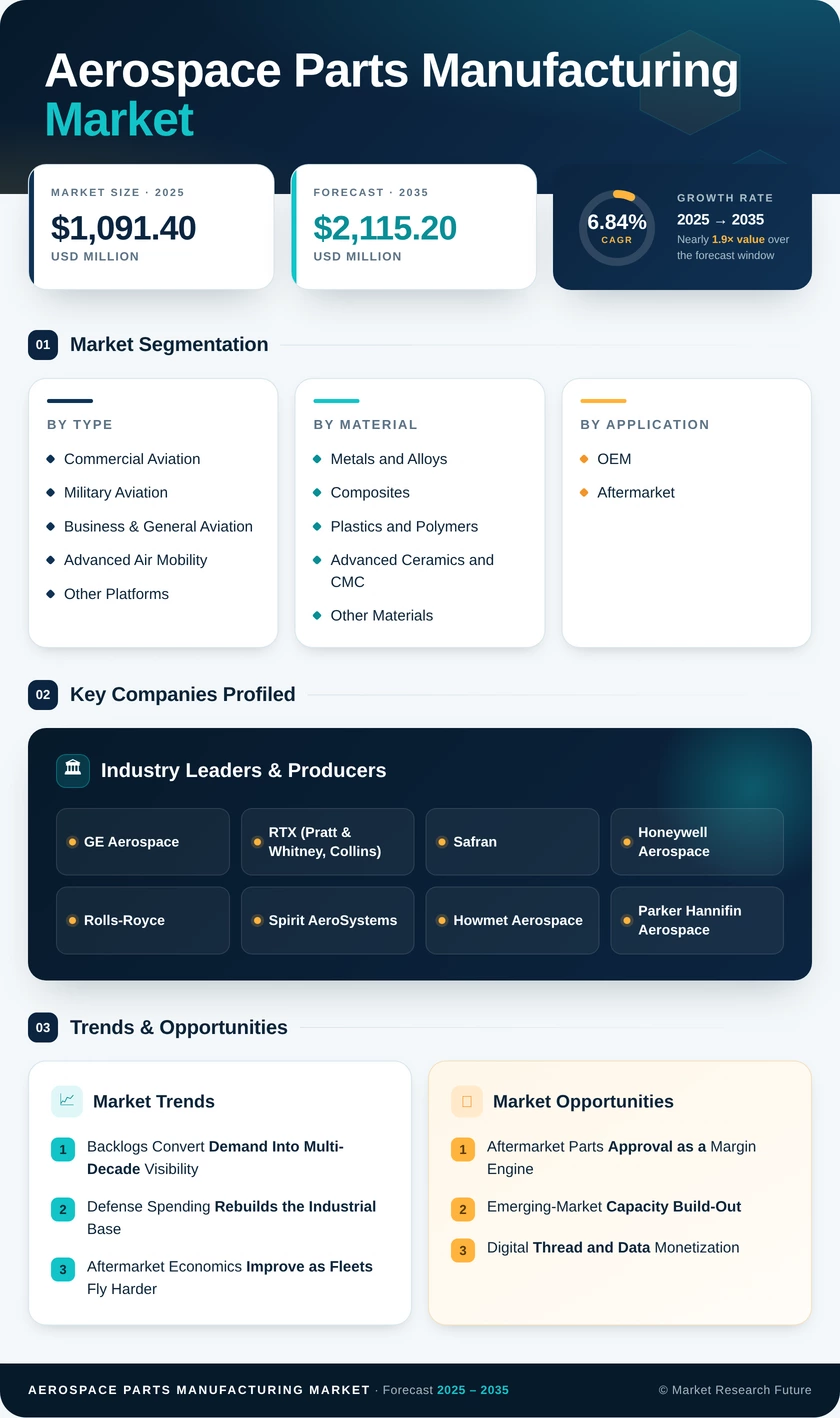
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product Type | Engines; Aerostructures; Cabin Interiors; Avionics; Insulation Components; Other Components | Engines | Insulation Components |
| By Material | Metals and Alloys; Composites; Plastics and Polymers; Advanced Ceramics and CMC; Other Materials | Metals and Alloys | Advanced Ceramics and CMC |
| By Aircraft Type | Commercial Aviation; Military Aviation; Business & General Aviation; Advanced Air Mobility; Other Platforms | Commercial Aviation | Advanced Air Mobility |
| By End User | OEM; Aftermarket | OEM | Aftermarket |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
| Engines | Shop-visit intervals compress as utilization rises, lifting demand for life-limited hot-section hardware |
| Aerostructures | Work-package consolidation follows fuselage reintegration by both major airframers |
| Cabin Interiors | Premium-cabin retrofit cycles shorten to roughly seven years on long-haul fleets |
| Avionics | Connectivity and navigation upgrade mandates drive retrofit alongside line-fit demand |
| Insulation Components | Tighter acoustic and thermal specifications expand content per aircraft |
| Other Components | Actuation and landing systems benefit from electrification of secondary power |
Product-type value is unusually concentrated. Propulsion alone accounts for close to two of every five dollars, and because engine hardware carries mandatory replacement intervals, that share proves more durable across downturns than structures or interiors.
By Material
| Sub-Segment | Key Trend |
| Metals and Alloys | Titanium and nickel sourcing diversification remains the top supply priority |
| Composites | Automated fiber placement lowers cost per kilogram on large structures |
| Plastics and Polymers | Flammability and smoke-toxicity rules push toward higher-performance thermoplastics |
| Advanced Ceramics and CMC | Temperature capability above nickel limits unlocks efficiency gains in hot sections |
| Other Materials | Coatings and adhesives gain content as bonded assemblies replace fasteners |
Material choice increasingly determines supplier economics rather than machining skill alone. Firms that control qualified feedstock relationships hold pricing power that downstream fabricators simply cannot replicate.
By Aircraft Type
| Sub-Segment | Key Trend |
| Commercial Aviation | Backlogs exceeding a decade of output provide unusual forward visibility |
| Military Aviation | Sustained procurement growth restores idled forging and casting capacity |
| Business & General Aviation | Fractional and charter demand supports steady mid-size jet output |
| Advanced Air Mobility | Certification milestones convert prototype spend into serial part orders |
| Other Platforms | Rotorcraft and small launch vehicles add niche precision content |
Platform mix determines cyclicality more than any other variable. Suppliers balanced across civil and defense weathered the last downturn with roughly half the revenue volatility of commercial-only peers.
By End User
| Sub-Segment | Key Trend |
| OEM | Rate discipline under regulatory oversight caps near-term volume upside |
| Aftermarket | Aging narrowbody fleets extend spares demand well beyond original service assumptions |
New-build volume still sets the headline number, yet profitability sits downstream. Suppliers now treat original equipment pricing as an entry ticket to decades of higher-margin spares and repair revenue.
By Geography
| Sub-Segment | Key Trend |
| North America | Engine and defense concentration sustains the largest single-region position |
| Europe | Clean Aviation funding directs capital toward propulsion and hydrogen demonstrators |
| Asia-Pacific | Localization mandates accelerate tier-one capacity creation |
| South America | Embraer's programme ramp anchors regional supplier development |
| Middle East & Africa | Offset-driven industrialization builds maintenance and assembly capability |
Geographic rebalancing is underway but slow. Certification lock-in means production rarely relocates once qualified, so new regions capture growth through new programmes rather than by displacing incumbents.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA