Segmentation Quick Reference
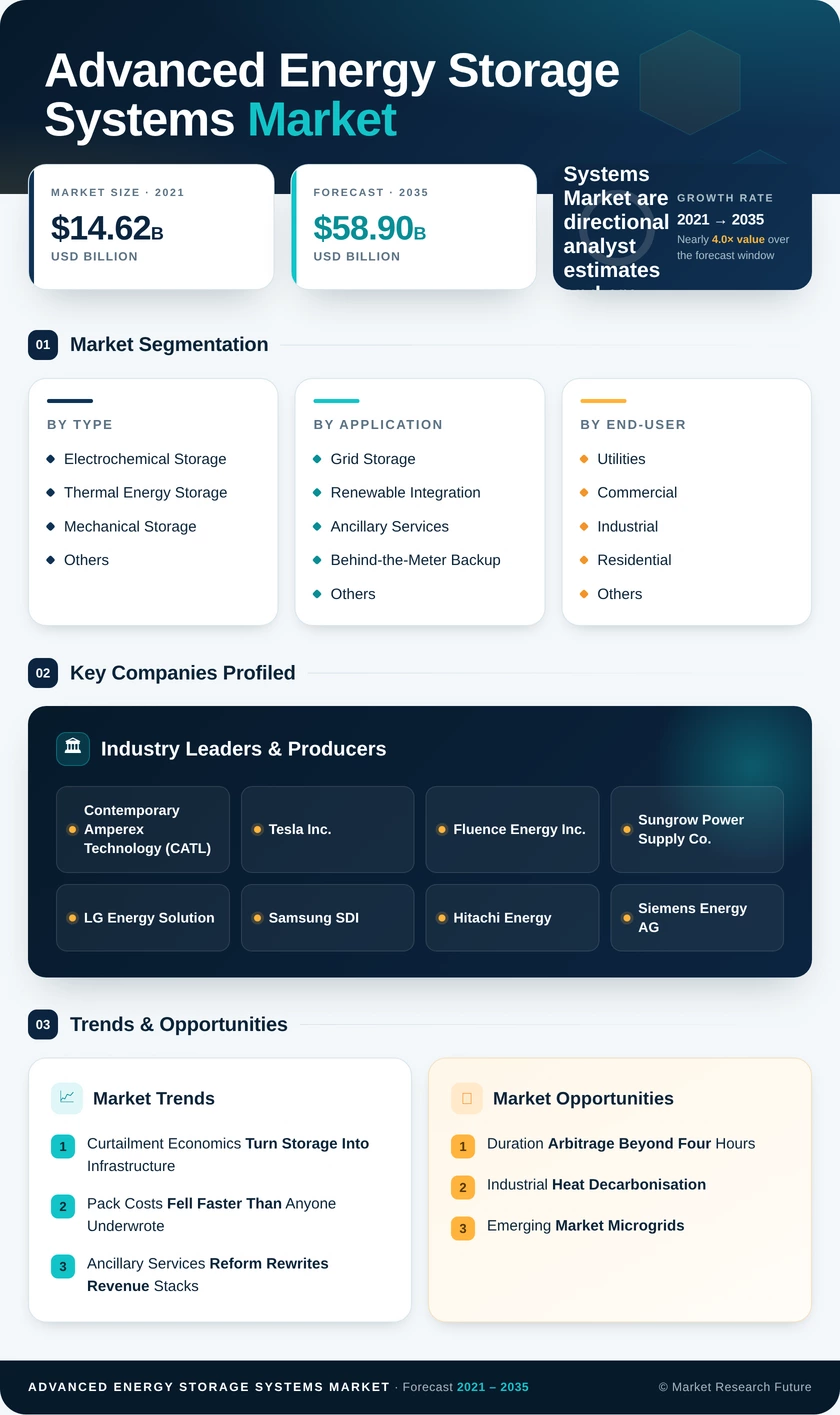
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Type | Electrochemical Storage; Thermal Energy Storage; Mechanical Storage; Others | Electrochemical Storage | Thermal Energy Storage |
| By Application | Grid Storage; Renewable Integration; Ancillary Services; Behind-the-Meter Backup; Others | Grid Storage | Renewable Integration |
| By End-User | Utilities; Commercial and Industrial; Residential; Others | Utilities | Commercial and Industrial |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific | North America |
Market Segmentation Overview
By Type
| Sub-Segment | Key Trend |
| Electrochemical Storage | Lithium iron phosphate displaces nickel-rich chemistries in stationary duty |
| Thermal Energy Storage | Electrified heat blocks target industrial process loads above 400°C |
| Mechanical Storage | Air-based and gravity architectures scale toward eight-hour discharge |
| Others | Hydrogen coupling and supercapacitor hybrids serve niche fast-response needs |
Type-level competition is shifting from energy density to cost per delivered cycle. Buyers with four-hour duty cycles will keep specifying electrochemical systems, while duration requirements beyond eight hours steadily open procurement to thermal and mechanical alternatives through the back half of the forecast.
By Application
| Sub-Segment | Key Trend |
| Grid Storage | Peaker replacement and resource adequacy contracting expand rapidly |
| Renewable Integration | Curtailment avoidance becomes a primary underwriting revenue line |
| Ancillary Services | Frequency product prices compress as capacity saturates regional markets |
| Behind-the-Meter Backup | Demand-charge arbitrage drives commercial rooftop pairing |
| Others | EV charging buffering and transmission deferral emerge as credible niches |
Application economics diverge by market maturity. Early-stage grids capture outsized ancillary revenue that erodes once a few hundred megawatts arrive, pushing later entrants toward capacity contracts and renewable firming where value scales with penetration rather than collapsing under it.
By End-User
| Sub-Segment | Key Trend |
| Utilities | Long-tenor procurement with heavy specification and bonding requirements |
| Commercial and Industrial | Uptime guarantees command price premiums over lowest-cost bids |
| Residential | Net-metering reform pushes households toward self-consumption storage |
| Others | Telecom, defence, and transport electrification create specialist demand |
Buyer sophistication varies more than buyer size. Utilities negotiate hardest on lifecycle cost and service obligations, whereas industrial and hyperscale customers will pay materially above index for guaranteed availability — a gap vendors increasingly exploit through differentiated service tiers.
By Region
| Sub-Segment | Key Trend |
| North America | Merchant revenue depth and tax-credit transferability accelerate build-out |
| Europe | Capacity auctions and grid-fee reform improve project bankability |
| Asia-Pacific | Vertical manufacturing integration sustains global cost leadership |
| South America | Hydro firming and mining microgrids anchor early demand |
| Middle East & Africa | Solar-plus-storage tenders scale from pilot to gigawatt-hour class |
Regional strategy should follow policy design rather than resource quality. Markets that have resolved grid-fee treatment, interconnection sequencing, and revenue stacking rules consistently convert pipelines into commissioned assets faster than markets with better sunshine but unsettled regulation.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA