Acaricides Market (2026 - 2035)

Acaricides Market Size, Share, Industry Trend & Analysis Research Report Information By Type (Organophosphates, Carbamates, Organochlorines, Pyrethrins, Pyrethroids, Other Types), By Application (Spray, Dipping, Hand Dressing, Other Applications), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) – Forecast Till 2035

Forecast Period
2026-2035
CAGR
5.4%
2025 Market Size
USD 414.10 Billion
2035 Market Size
USD 700.90 Billion
Agriculture ● Updated August 24, 2026 Report ID: MRFR/Agri/3829-HCR | Pages: 90 | Author: Snehal Singh, Pradeep Nandi

Acaricides Market Summary

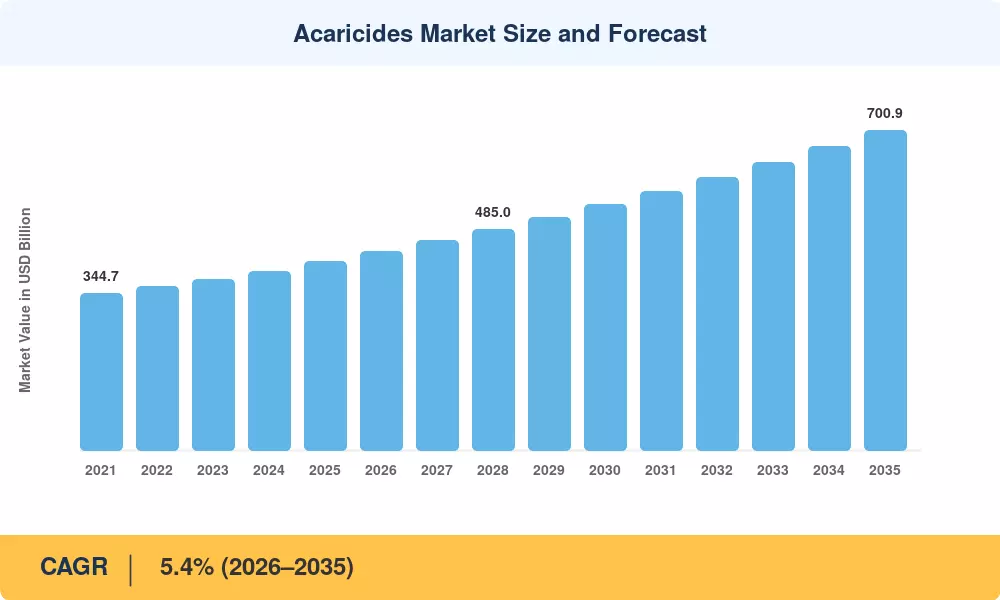
The global Acaricides Market was valued at USD 414.10 Billion in 2025 and is projected to grow from USD 436.50 Billion in 2026 to USD 700.90 Billion by 2035, registering a CAGR of 5.4% during the forecast period. This expansion is firmly anchored in rising global food demand driven by a world population set to exceed 9.7 billion by 2050, alongside tightening crop protection mandates from the FAO and national agriculture ministries. Governments in key agrarian economies are actively subsidizing pest management programs, making the Acaricides Market a focal point of agricultural policy investment.

The way pest control treatments are delivered to the field is changing in a subtle but significant way. Targeted pyrethroid and bio-rational chemistries are gradually replacing older broad-spectrum organochlorine formulations in accordance with Integrated Pest Management (IPM) frameworks supported by the European Food Safety Authority (EFSA) and the Environmental Protection Agency (EPA) [2]. For example, the EU's Farm to Fork Strategy aims to reduce chemical pesticide use by 50% by 2030, which would increase demand for next-generation acaricide formulations with better environmental profiles and resistance-management capabilities.

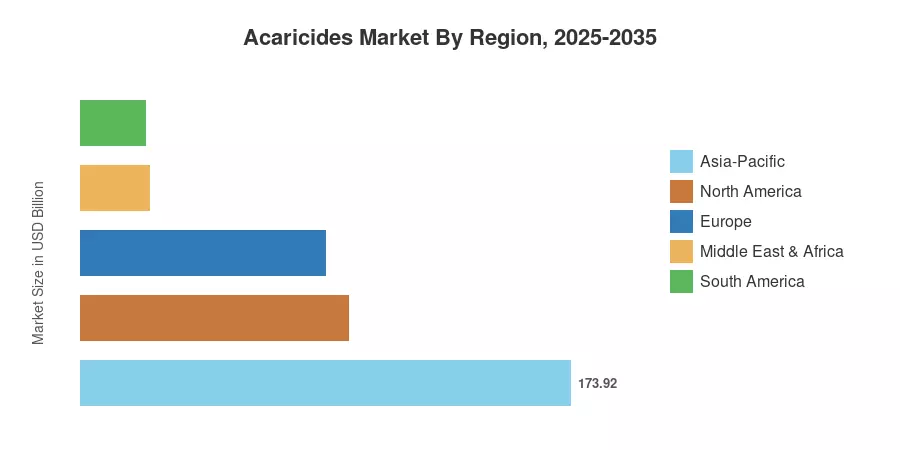
Driven by intensive agriculture in China and India, the Asia-Pacific region holds the greatest proportion of the acaricides market, at around 42%. With a CAGR of more than 6%, the region is also the fastest-growing. Due to strict maximum residue level (MRL) rules that force farmers to use premium formulations, Europe accounts for about 21% of the world's income base. Precision application technology and huge row-crop acreage continue to help North America, the second-largest market with a share of almost 23%. Innovation pipelines continue to be the most significant competitive difference through 2035 as resistance pressures increase internationally.


Key Report Takeaways

• By Type

  • Organophosphates accounted for an estimated 28% of the Acaricides Market in 2025, reflecting their broad efficacy across multiple mite species.
  • Pyrethroids are projected to register the fastest segment CAGR of 6.3% through 2035, fueled by lower mammalian toxicity and favorable regulatory profiles.
  • Carbamates contributed approximately USD 82 billion in 2025 revenue, supported by cost-effective formulations popular in South American agriculture.

• By Application

  • Spray application dominates the Acaricides Market with an estimated 52% revenue share, driven by compatibility with mechanized and drone-assisted delivery systems.
  • Dipping applications are growing at a notable 5.8% CAGR, particularly in livestock-intensive regions where tick management is critical.

• By Geography

  • Asia-Pacific leads global demand, holding approximately 42% of total revenue.
  • North America contributes roughly 23% of the Acaricides Market, supported by large-scale commercial farming operations.
  • South America is expanding at a CAGR of 5.6%, with Brazil driving the bulk of new demand.


Acaricides Market Size and Forecast (2021–2035)

Market Research Future employs a triangulated research methodology combining primary interviews with agrochemical manufacturers, distributor channel analysis, and crop acreage databases from the USDA and FAO to derive market estimates. Historical data (2021–2024) relies on verified revenue disclosures, while the forecast (2026–2035) uses a bottom-up segmental build validated against macroeconomic agricultural output indicators[3].
Acaricides Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising global food demand 1.3% Global Long-term (≥4 yr)
Acaricide resistance in mite populations 1.0% Asia-Pacific, South America Short-term (≤2 yr)
Government crop protection subsidies 0.8% Asia-Pacific, Africa Medium-term (2–4 yr)
Expansion of high-value horticulture 0.7% Europe, North America Medium-term (2–4 yr)
Climate change is extending pest seasons. 0.6% Global Long-term (≥4 yr)
Precision agriculture adoption 0.5% North America, Europe Medium-term (2–4 yr)
Livestock tick-borne disease prevalence 0.5% Africa, South America Short-term (≤2 yr)


Rising Global Food Demand

The FAO reports that plant pests destroy up to 40% of global crop yields annually, severely threatening food security. To feed a projected population of 9.7 billion by 2050, agricultural production must scale up. This immense pressure drives intensified crop protection, accelerating global acaricide consumption as farmers mitigate losses and maximize food output per hectare.


Resistance Emergence in Mite Populations

The rapid evolution of resistance in Tetranychus urticae alters crop management. Academic data indicates over 60% of surveyed mite populations show resistance to multiple core chemical classes. This biological pressure forces growers to continuously rotate active ingredients, accelerating the market shift toward premium, high-value novel formulations and driving overall market revenue growth per treated hectare.

Government Crop Protection Subsidies

Government financial subsidies significantly improve global agricultural input affordability. For example, India’s national budget allocated over 150 billion rupees toward comprehensive crop protection and input support schemes, effectively lowering procurement barriers for smallholder farmers. These state-backed initiatives stabilize market volume and drive the widespread, affordable adoption of specialized acaricides across rapidly growing, developing agricultural networks.


Climate-Driven Pest Season Extension

IPCC climate assessments highlight that a 1.5°C global temperature increase drastically alters pest dynamics, extending reproductive windows for mites by up to 30 days in temperate zones. This prolonged activity requires additional seasonal spray cycles. Consequently, per-acre chemical consumption rises significantly as shifting climate trends drive documented northward migrations of critical agricultural crop pest vectors.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Regulatory restrictions on chemical pesticides –0.9% Europe, North America Long-term (≥4 yr)
Environmental and pollinator safety concerns –0.6% Global Medium-term (2–4 yr)
High R&D costs for new active ingredients –0.5% Global Long-term (≥4 yr)
Availability of biological pest control alternatives –0.4% Europe, North America Medium-term (2–4 yr)
Counterfeit and substandard product infiltration –0.3% Asia-Pacific, Africa Short-term (≤2 yr)


Tightening Regulatory Frameworks

European Union authorities strictly enforce Regulation (EC) No 1107/2009, establishing rigid safety thresholds for synthetic chemical active substances. Meanwhile, the United States Environmental Protection Agency continuously implements updated Endangered Species Act compliance strategies. These overlapping federal frameworks enforce geographic buffer zones and localized usage restrictions, adding intense compliance pressure for chemical acaricide manufacturing and registrations.


Rising Biopesticide Competition

The United Nations Environment Programme documents growing integration of biological control agents within global integrated pest management frameworks. Utilizing predatory organisms and microbial strains like Beauveria bassiana, these biological alternatives actively absorb addressable market share in high-value greenhouse horticulture. State initiatives prioritizing organic practices amplify this competitive shift away from traditional, purely synthetic acaricides.


Counterfeit Product Infiltration

Data verified by the United Nations and international agricultural agencies reveals that illegal, unregistered, or counterfeit crop protection products constitute up to 25% of the market in specific developing regions. These substandard formulas undermine local agricultural productivity, accelerate chemical resistance, and strip hundreds of millions of dollars in legitimate revenue from authorized global crop protection companies.


Acaricides Market Opportunities

Next-Generation Resistance-Breaking Chemistries

Global crop security relies heavily on developing novel chemical formulations. Modern research pipelines focus intensely on introducing new active ingredients targeting mitochondrial complex processes to bypass multi-resistant pest strains. Agrochemical providers prioritizing these novel modes of action gain significant commercial leverage, driving target crop volume growth across highly vulnerable agricultural zones throughout South America and the Asia-Pacific.


Precision Application and Drone-Delivered Acaricides

The Food and Agriculture Organization highlights precision drone technologies as critical for sustainable intensification. Field evaluations validate that unmanned aerial vehicles optimize canopy penetration, reducing traditional pesticide consumption volumes by up to 40%. As national regulatory frameworks mature across developing agricultural economies, drone-delivered crop protection creates an expanded, tech-driven segment for specialized low-volume acaricide delivery.


Emerging Market Expansion in Sub-Saharan Africa

The United Nations notes that sub-Saharan Africa holds a significant share of the world’s remaining uncultivated arable land. As regional production climbs to meet local food security targets, accelerating cultivation triggers substantial pest pressure. This structural shift creates major long-term expansion avenues for crop protection companies through targeted packaging sizes and specialized local distribution networks.


Digital Pest Scouting and Data-Driven Application Timing

AI-powered pest scouting platforms that use satellite imagery and in-field sensors to predict mite outbreaks are enabling just-in-time acaricide application. Companies that integrate their product offerings with digital decision-support tools can build subscription-based recurring revenue streams, shifting the commercial model from volume-based sales to outcome-based crop protection services.

Livestock Acaricide Growth in Tick-Borne Disease Zones

The World Organisation for Animal Health states that vector-borne animal diseases cause severe productivity declines, accounting for a 20% loss in global livestock production. Ticks and related tick-borne diseases cost the livestock sector billions of dollars annually in mortality and reduced milk yields. This massive burden accelerates international adoption of dipping and pour-on livestock acaricides.


Acaricides Market Future Outlook

AI-Enabled Pest Prediction and Autonomous Application

The Food and Agriculture Organization highlights that plant pests cause up to $220 billion in annual global crop losses. To mitigate this damage, automated integrated pest management frameworks are deploying machine learning models. This shifts the acaricides market from calendar-based spraying to threshold-triggered applications, optimizing chemical efficiency and reducing total pesticide volume requirements by up to 30%.

Sustainability Reporting and ESG-Driven Reformulation

The Taskforce on Nature-related Financial Disclosures framework directly reshapes global corporate accountability, pushing institutional capital toward nature-positive outcomes. Publicly listed agrochemical manufacturers must formally assess and disclose localized ecological impacts. This regulatory evolution forces substantial investment into lower-persistence acaricide formulations and accelerated R&D pipelines for hybrid biological-chemical crop protection portfolios

.

Convergence of Chemical and Biological Pest Management

United Nations agricultural guidelines emphasize combining biological control agents with highly targeted chemical interventions to delay pest resistance. European greenhouse networks have successfully standardized this hybrid methodology. Over the next decade, improving the environmental shelf-life of predatory organisms will expand these integrated strategies into broad, open-field cultivation, redefining long-term commercial acaricide demand.


Supply Chain Regionalization and Active Ingredient Reshoring

Government reports confirm that India’s Production Linked Incentive scheme has catalyzed over 2.16 lakh crore rupees in manufacturing investments, driving massive chemical self-reliance. This extensive reshoring, paired with comparable Western supply chain mandates, accelerates regionalization across the agrochemical sector. Consequently, the acaricides market gains supply resilience, though regional intermediate production costs will be structured differently.


Acaricides Market Segmentation

By Type

Segment Key Metric Primary Demand Driver
Organophosphates ~28% revenue share Broad-spectrum efficacy, cost-effectiveness
Carbamates USD 82.00 Billion (2025) Favorable price-performance in tropical agriculture
Organochlorines CAGR ~3.1% Legacy use in developing markets, declining registrations
Pyrethrins ~7% revenue share Organic-certified crop programs
Pyrethroids CAGR ~6.3% Low mammalian toxicity, regulatory preference
Other Types ~9% revenue share Emerging bio-rational and novel MOA chemistries


Organophosphates remain the workhorse chemistry in the Acaricides Market, valued for their cost profile and effectiveness against a wide range of mite and tick species. They hold the largest type-level revenue share, though regulatory headwinds in the EU and North America are gradually eroding their registrations. In developing markets — particularly South Asia and sub-Saharan Africa — affordability keeps organophosphates central to farmer pest management programs.

Pyrethroids are emerging as the fastest-growing type segment, supported by toxicological profiles that meet increasingly stringent regulatory standards. Their knockdown speed and residual activity make them attractive for both crop and livestock applications. Several manufacturers are investing in microencapsulation technologies to extend pyrethroid field persistence and reduce environmental runoff, addressing one of the category's historical limitations [14].

By Application

Segment Key Metric Primary Demand Driver
Spray ~52% revenue share Compatibility with mechanized and aerial delivery
Dipping CAGR ~5.8% Livestock tick control in tropical regions
Hand Dressing ~10% revenue share Smallholder and homestead garden use
Other Applications CAGR ~4.6% Pour-on, dust, and fumigation methods


Spray application commands the majority of the Acaricides Market by application type, reflecting the dominance of field-crop usage where tractor-mounted, drone, or aerial sprayers deliver the most efficient coverage. The growth of drone-based spraying, particularly in China and India, is reinforcing spray dominance while improving precision and reducing operator exposure.

Dipping applications are posting above-average growth, driven by the need for effective tick management in cattle-rearing regions. In Brazil and East Africa, communal dip tanks remain a frontline defense against tick-borne livestock diseases, and international development programs continue to invest in expanding this infrastructure [12].


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
Asia-Pacific ~42% revenue share Smallholder access, resistance management and drone adoption
North America ~23% revenue share Precision agriculture, regulatory compliance, specialty crops
Europe ~21% revenue share MRL compliance, sustainable formulations, IPM integration
South America CAGR ~5.6% Soybean/citrus expansion, tick control for livestock
Middle East & Africa CAGR ~5.9% Arable land expansion, subsidy-driven adoption
Total USD 414.10 Billion (2025)

The Acaricides Market displays a distinct geographic hierarchy shaped by agricultural intensity, regulatory environments, and pest pressure. Asia-Pacific leads both in absolute size and growth velocity, while Europe and North America represent mature but innovation-driven segments.


North America

Country Key Metric Key Driver
United States ~72% of regional revenue Large-scale row-crop and specialty agriculture
Canada CAGR ~4.9% Canola and pulse crop mite management
Mexico ~8% of regional revenue Expanding avocado and berry cultivation


North American demand is driven by the sheer scale of US commercial farming, where spider mite infestations in corn, soybean, and cotton represent recurring treatment opportunities. The EPA's ongoing review of older organophosphate registrations is redirecting demand toward pyrethroid and newer chemistries, while precision variable-rate spraying adoption in the US Midwest is improving per-acre efficiency [7][11].

Europe

Country Key Metric Key Driver
Germany ~18% of regional revenue Integrated fruit and viticulture pest programs
United Kingdom CAGR ~4.7% Greenhouse horticulture expansion
France ~16% of regional revenue Wine grape and cereal crop protection
Italy ~13% of regional revenue Mediterranean horticulture under high pest pressure
Spain CAGR ~5.1% Citrus and olive mite management
Nordic Countries ~6% of regional revenue Protected greenhouse cultivation
Russia CAGR ~5.3% Expanding wheat and sunflower acreage
Rest of Europe ~14% of regional revenue Diversified agricultural demand


The European Acaricides Market is shaped by the world's most stringent pesticide regulations. EFSA's renewal process for active substance approvals has removed several legacy compounds from the market, pushing demand toward premium bio-rational and low-toxicity formulations. France's Ecophyto II+ plan and Germany's national action plan on sustainable pesticide use create both constraints and opportunities for innovative manufacturers [7][13].

Asia-Pacific

Country Key Metric Key Driver
China ~38% of regional revenue Intensive rice, vegetable, and tea cultivation
India CAGR ~6.8% Cotton and chili mite outbreaks, government subsidies
Japan ~12% of regional revenue High-value fruit and greenhouse production
South Korea CAGR ~5.4% Specialty crop diversification
ASEAN ~11% of regional revenue Palm oil, rubber, and tropical horticulture
Rest of Asia-Pacific CAGR ~5.7% Emerging agricultural intensification


Asia-Pacific dominates the Acaricides Market by both volume and value. China's Ministry of Agriculture reported that pest-related crop losses exceeded USD 14 billion in 2023, with mites accounting for a significant share in vegetable and tea plantations [8]. India's acaricide consumption is accelerating as Bt cotton acreage — highly susceptible to sucking pests — continues to expand across Maharashtra and Gujarat. Drone-based spraying adoption in China surpassed 200 million treated hectares cumulatively by 2024, amplifying delivery efficiency [11].

South America

Country Key Metric Key Driver
Brazil ~64% of regional revenue Soybean, citrus, and cattle tick management
Argentina CAGR ~5.2% Expanding grain and oilseed production
Rest of South America ~15% of regional revenue Diversified tropical agriculture


Brazil is the engine of South American demand, where the cattle tick (Rhipicephalus microplus) alone costs the livestock industry an estimated USD 3.2 billion annually in productivity losses [12]. Soybean rust management and citrus mite control in São Paulo state further reinforce Brazil's position as a critical growth geography for the Acaricides Market.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia ~18% of regional revenue Date palm and greenhouse vegetable protection
UAE CAGR ~5.5% Controlled-environment agriculture expansion
South Africa ~22% of regional revenue Citrus export crop protection standards
Egypt CAGR ~6.1% Cotton and vegetable pest management
Rest of MEA ~38% of regional revenue Livestock tick control across East Africa


The Middle East & Africa region exhibits the highest growth potential driven by two distinct dynamics: expanding arable cultivation and endemic livestock tick burdens. East African nations face persistent losses from tick-borne diseases, including East Coast Fever, creating sustained demand for dipping acaricide programs supported by international development agencies [12].


Acaricides Market By Region, 2025-2035

Competitive Benchmarking

The Acaricides Market exhibits a high concentration profile, with the top five companies accounting for an estimated 55–60% of global revenue. The competitive landscape is defined by large-scale integrated agrochemical corporations that leverage extensive R&D pipelines, global distribution networks, and regulatory expertise as barriers to entry. A moderately long tail of regional formulators and generic manufacturers serves price-sensitive segments, particularly in Asia and Africa[14].

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Bayer AG ~12–15% Envidor, Oberon, Movento Broad portfolio leader with strong resistance-management pipeline
BASF SE ~10–13% Nealta, Kumulus Innovation-driven; focus on novel MOA development
Syngenta Group ~9–12% Agri-Mek, Vertimec Global reach with strong presence in specialty crops
Corteva Agriscience ~7–10% Delegate, Entrust IPM-compatible solutions, growing biological integration
FMC Corporation ~6–9% Bifenthrin, Capture Cost-competitive pyrethroids for broadacre crops
Sumitomo Chemical ~5–7% Danitoл, Danitron Strong Asia-Pacific positioning, tick control specialization
UPL Limited ~4–6% Omite, Acramite Value-tier leader in emerging markets
Nufarm Limited ~3–5% Generic pyrethroid and organophosphate formulations Regional strength in Australia and Latin America
ADAMA Agricultural Solutions ~3–5% Off-patent formulations, mixtures Volume-driven strategy in price-sensitive segments
Nippon Soda Co., Ltd. ~2–4% Nissorun, Sanmite Specialty niche in horticultural acaricides


Recent News & Developments


  • CropChem- (October, 2025)--Launched Perseus Duo, Brazil's first dual-action acaricide combining Spirodiclofen and Abamectin to target red and false rust mites.
  • Sichuan Lomon Bio Technology- (June, 2026)--Launched BIMIE, the world's first fully registered microbial, bacterial-based bio-acaricide utilizing Bacillus velezensis LM-W2 against resistant mites.
  • Shandong Kangqiao Biotechnology- (December, 2025)--Unveiled Liluo (Bentioflumin 200g/l SC), their first self-developed, long-acting novel chemical acaricide to bypass existing mite resistance.


Acaricides Market Report Scope

Parameter Detail
Market Scope Global Acaricides Market covering chemical types, application methods, and five geographic regions
Study Period 2021–2035
CAGR 5.4% (2026–2035)
Market Size (2025) USD 414.10 Billion
Market Size (2035) USD 700.90 Billion
Fastest Growing Segment Pyrethroids (by type); Dipping (by application); Asia-Pacific (by region)
Companies Profiled Bayer AG, BASF SE, Syngenta Group, Corteva Agriscience, FMC Corporation, Sumitomo Chemical, UPL Limited, Nufarm Limited, ADAMA Agricultural Solutions, Nippon Soda Co., Ltd.
Valuation Currency USD Billion

FAQs

How do resistance management rotation programs affect acaricide purchasing patterns?
Growers rotating between chemical classes purchase a wider range of products per season, increasing per-farm spend by an estimated 15–20% compared to single-chemistry approaches [5]. This rotation mandate creates recurring demand across multiple product lines.
What shelf-life limitations should buyers consider when stocking acaricide inventory?
Most formulated acaricides maintain efficacy for two to three years under recommended storage conditions. Emulsifiable concentrates are more sensitive to temperature extremes than wettable powders or granules [14].
How do organic certification standards restrict acaricide options for growers?
Organic standards generally permit only pyrethrin-based and sulfur-based acaricides, excluding synthetic chemistries entirely [7]. This significantly narrows product choice and increases per-hectare treatment costs.
What role do adjuvant additives play in the field performance of acaricide sprays?
Proper adjuvant selection can improve leaf coverage and penetration by 25–40%, particularly on waxy or pubescent foliage [14]. Surfactants and sticker-spreaders are critical for maximizing active ingredient contact with target mites.
How does the Acaricides Market differ in regulatory burden between the EU and the US?
EU registration typically takes 7–10 years and requires zone-level evaluations, while US EPA registration averages 3–5 years [7][13]. Cost differentials can exceed USD 30 million per active ingredient registration.
What emerging biological alternatives could displace chemical acaricides in greenhouse production?
Predatory mites (Phytoseiulus persimilis, Amblyseius californicus) already manage 40–50% of greenhouse mite control in Northern Europe [15]. Chemical displacement remains limited to controlled environments for now.
How are rising raw material costs influencing the Acaricides Market pricing outlook?
Active ingredient prices rose 8–12% between 2022 and 2024 due to intermediary supply constraints from China [25]. Manufacturers are passing costs through selectively, compressing margins for generic formulators.    
Author
Author
Author Profile
Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.
Co-Author
Co-Author Profile
Pradeep Nandi LinkedIn Senior Research Analyst
I have a bachelor's degree in mechanical engineering and an MBA. I have more than two years of expertise in the retail, food, and beverage, chemical, and material industries, and hence have developed a sound cross-domain expertise. A firm believer in lifelong learning and sharing of knowledge. Having a proclivity for hatching ideas and trying to absorb as much information as possible in a short amount of time. Introducing corporates to the data and insight, which enables them to move from probability to possibility, has been my key areas of interest. 

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of agrochemical regulatory databases, peer-reviewed agricultural journals, toxicology publications, and authoritative food safety organizations. Key sources included the US Environmental Protection Agency (EPA) Pesticide Registration Database, European Food Safety Authority (EFSA) Pesticides Database, Food and Agriculture Organization (FAO) FAOSTAT and Pesticide Use Statistics, World Health Organization (WHO) Vector Control Guidelines, US Department of Agriculture (USDA) National Agricultural Statistics Service (NASS), Eurostat Agricultural Pesticide Sales Database, Codex Alimentarius Commission, National Pesticide Information Center (NPIC), Environmental Protection Agency Office of Pesticide Programs, European Commission DG SANTE Pesticides Database, and national agricultural ministry reports from Brazil (MAPA), India (Ministry of Agriculture), and China (MOA). Academic sources included National Center for Biotechnology Information (NCBI/PubMed) for resistance studies, Journal of Agricultural and Food Chemistry, Pesticide Biochemistry and Physiology, and Journal of Economic Entomology. Trade association data was gathered from CropLife International, European Crop Protection Association (ECPA), Agricultural & Food Chemistry Council, and national pest management alliance reports. These sources were used to collect pesticide usage statistics, regulatory approval timelines, resistance monitoring data, crop protection trends, and import/export trade analysis for organophosphate, carbamate, pyrethroid, organochlorine, and bio-based acaricide categories.


Primary Research

To gather both qualitative and quantitative information, the primary research process involved interviewing players from both the supply and demand sides. Executives from the supply side included crop protection division presidents, global pesticide and acaricide portfolio managers, VPs of agricultural research and development, heads of regulatory affairs (EPA/REACH registrations), commercial crop protection directors, technical sales directors, and product managers with expertise in biological and synthetic pesticides. The demand-side sources included people working in the fields of agronomy, crop protection, agricultural extension, livestock veterinary medicine, animal health procurement, distributors, agrochemical channel partners, and pest control advisors (PCAs) from regions that specialize in crops. The timeliness of product pipeline development, the accuracy of market segmentation across chemical classes, the adoption of application technologies, the dynamics of pricing by crop type, and the trends in integrated pest management (IPM) integration were all confirmed through primary research.

Primary Respondent Breakdown:

• By Designation: C-level Primaries (30%), Director Level (35%), Others (35%)

• By Region: North America (30%), Europe (32%), Asia-Pacific (25%), Rest of World (13%)


Market Size Estimation

Global market valuation was derived through agrochemical revenue mapping and application volume analysis. The methodology included:

• Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America

• Product mapping across organophosphates, carbamates, pyrethroids, organochlorines, bio-based microbial botanical extracts, and mineral-based acaricide categories

• Analysis of reported and modeled annual revenues specific to acaricide/mite-control portfolios within broader crop protection and animal health divisions

• Coverage of manufacturers representing 75-80% of global market share in 2024

• Extrapolation using bottom-up (hectares treated × application rate × ASP by crop type/country) and top-down (manufacturer revenue validation against agrochemical division reporting) approaches to derive segment-specific valuations for agricultural, veterinary, and industrial applications

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















