4K TV Market (2026 โ€“ 2035)

4K TV Market Size, Share and Research Report By Type (55 Inch, < 55 Inch, 65 Inch), By End-users (Household, Public), And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) โ€“ Industry Forecast Till 2035
ID: MRFR/SEM/2140-HCR 200 Pages Ankit Gupta Last Updated: October 27, 2026
4K TV Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.40%
2025 Market SizeUSD 290.62 Billion
2035 Market SizeUSD 593.43 Billion
Key Players
Samsung Electronics
LG Electronics
TCL Technology
Sony Corporation
Hisense Group
Xiaomi Corporation
Opportunities
  • Commercial and Hospitality Digital Signage
  • Emerging-Market Urbanization Wave
  • Smart-Home Hub Convergence

4K TV Market Summary

The global 4K TV Market reached an estimated USD 290.62 Billion in 2025, and Market Research Future projects this value to climb to USD 312.13 Billion in 2026 before expanding to USD 593.43 Billion by 2035 at a compound annual growth rate of 7.40% during the 2026โ€“2035 forecast period. Two forces anchor this trajectory: the rapid build-out of native ultra-high-definition content libraries by global streaming platforms, and an ongoing console upgrade cycle spearheaded by HDMI 2.1โ€“capable gaming hardware that compels households to replace aging displays. Government trade-in subsidy programs, particularly China's nationwide appliance refresh initiative allocating roughly USD 3.8 Billion through 2027, inject additional demand directly into the replacement funnel .

On the technology side, organic light-emitting diode panels are pushing into price bands that were exclusive to LCD backlighting just two years ago, driven by improved eighth-generation fabrication yields and the ramp-up of inkjet-printed OLED pilot lines. MiniLED backlighting now features in mid-range sets priced below USD 800 at the 55-inch class, compressing the value proposition gap with quantum-dot models. Industry-wide capital expenditure on advanced display fabrication exceeded USD 28 Billion in 2024, signaling a sustained commitment to next-generation panel architectures .

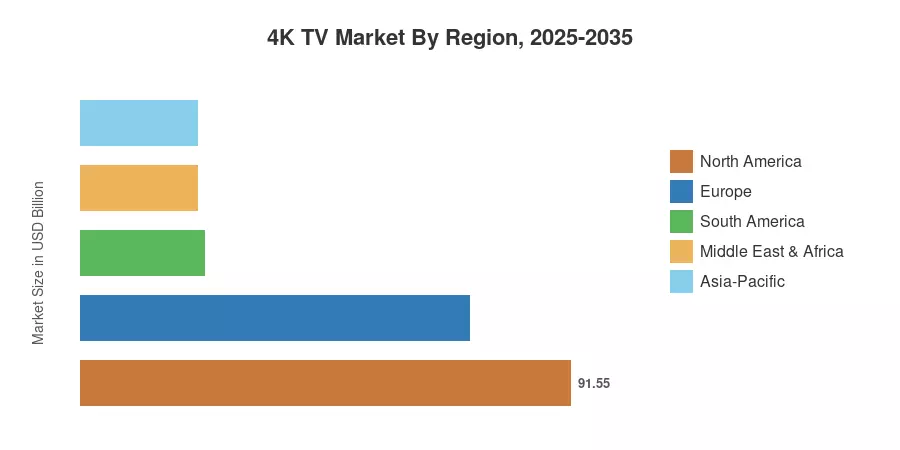
North America remained the dominant region in the 4K TV Market, holding an estimated 31.5% revenue share in 2024, buoyed by high average selling prices and robust smart-home integration trends. Asia-Pacific is the fastest-growing region with a projected CAGR of 7.50% through 2035, driven by surging household penetration in India, Southeast Asia, and continued premium-tier purchasing in Japan and South Korea. Europe trails as the second-largest region at approximately 25.0% share, underpinned by energy-labeling mandates that channel consumer spend toward efficient UHD panels. The decade ahead will likely reshape competitive hierarchies as Chinese manufacturers extend their reach into premium segments traditionally dominated by Korean brands.

ย 

Key Report Takeaways

โ€ข By Technology

  • OLED display technology commanded approximately 44.4% of the 4K TV Market share in 2024, reflecting growing consumer preference for contrast-rich, thin-form-factor panels.
  • Quantum Dot technology is forecast to register a 7.40% CAGR during 2026โ€“2035, driven by price-competitive wide-color-gamut sets entering the mass segment.

โ€ข By Screen Size & End User

  • The 40โ€“59 inch bracket accounted for roughly 43.3% of 4K TV Market revenue in 2024, remaining the sweet spot for mainstream living-room installations.
  • Residential buyers generated about 62.4% of the total 4K TV Market sales in 2024, while the commercial segment is positioned to expand at a 6.34% CAGR through 2035.

โ€ข By Region

  • North America contributed 31.5% of the 4K TV Market revenue in 2024, supported by premium pricing and early 8K-upscaling adoption.
  • Asia-Pacific leads the 4K TV Market growth outlook at a projected 7.50% CAGR, fueled by urbanization, rising disposable incomes, and aggressive OEM pricing strategies.

ย 

Market Size and Forecast (2021โ€“2035)

Market Research Future derives its sizing from a triangulated methodology that cross-references panel shipment data, retail sell-through tracking, OEM financial disclosures, and regional import/export databases. Historical figures reflect actual industry performance, while forecast values are modeled using the calibrated CAGR and adjusted for anticipated policy catalysts, panel-cost trajectories, and content-ecosystem expansion.
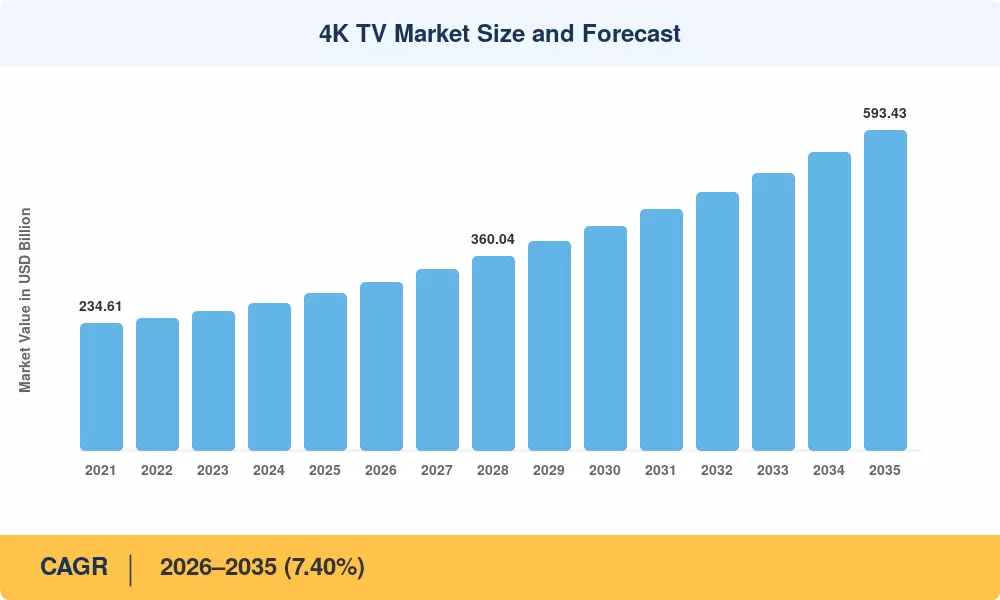
4K TV Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Streaming platform 4K content expansion +1.4% Global Short-term (โ‰ค2 yr)
Panel cost reduction via Gen-8.5 fabs +1.2% Asia-Pacific, Global Medium-term (2โ€“4 yr)
HDMI 2.1/2.2 gaming console cycle +0.9% North America, Europe Short-term (โ‰ค2 yr)
Government trade-in and subsidy programs +0.8% China, India Medium-term (2โ€“4 yr)
Commercial digital signage modernization +0.7% North America, Europe Long-term (โ‰ฅ4 yr)
Smart-home hub convergence +0.6% North America, Asia-Pacific Long-term (โ‰ฅ4 yr)
Rising emerging-market urbanization +0.5% South America, MEA Long-term (โ‰ฅ4 yr)

ย 

Streaming Content Libraries as a Demand Catalyst

Netflix, Amazon Prime Video, Disney+, and Apple TV+ collectively offered over 6,500 native 4K titles by mid-2025, up from approximately 3,800 in 2022 [5]. This expansion directly pressures households with legacy 1080p sets to upgrade, particularly as platform algorithms default to the highest-quality stream the display can accept. Live sports broadcasting in 4K โ€” highlighted by the 2024 Paris Olympics and the NFL's expanded 4K schedule โ€” has created time-sensitive purchase urgency that retailers capitalize on through seasonal promotional bundles. The 4K TV Market benefits disproportionately from this content flywheel because each new title added to a 4K library permanently raises the opportunity cost of keeping an older television.

Panel Cost Deflation and Manufacturing Scale

Chinese panel manufacturers, led by BOE, CSOT, and Tianma, have driven 55-inch UHD open-cell panel costs below USD 85 as of Q1 2025, roughly 40% lower than 2021 levels [7]. This cost trajectory owes much to Gen-8.5 and Gen-10.5 fab utilization rates exceeding 90%, alongside improved OLED deposition yields that cut material waste. For the 4K TV Market, declining panel costs translate directly into lower retail prices that unlock the next wave of first-time buyers in price-sensitive regions such as Southeast Asia, Latin America, and Sub-Saharan Africa.

Gaming Console Ecosystem Effects

Sony's PlayStation 5 Pro and Microsoft's next-generation Xbox โ€” both shipping with HDMI 2.1 output capable of 4K at 120 Hz โ€” have fundamentally reset consumer expectations for display performance [6]. Attach-rate data from the Consumer Technology Association indicates that roughly 68% of new console buyers purchase or plan to purchase a compatible 4K display within 12 months of console acquisition. This console-driven demand channel reinforces the 4K TV Market's growth trajectory because gaming households tend to favor larger screens and higher-tier panel technologies, pushing average selling prices upward.

Government Subsidy Programs

China's State Council extended its appliance trade-in program through 2027, earmarking approximately USD 3.8 Billion in subsidies that cover up to 20% of a new television's purchase price . India's BIS certification framework for UHD displays, combined with production-linked incentive schemes for domestic electronics manufacturing, is expected to lower retail prices by 8โ€“12% over the next three years [10]. These policy interventions materially accelerate replacement cycles in the two largest population markets, reinforcing the 4K TV Market's medium-term growth runway.

ย 

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Smartphone-first content consumption shift โˆ’0.7% Global Long-term (โ‰ฅ4 yr)
Extended TV replacement cycles (8+ years) โˆ’0.6% North America, Europe Long-term (โ‰ฅ4 yr)
Macroeconomic and inflationary headwinds โˆ’0.5% Global Short-term (โ‰ค2 yr)
Limited native 4K terrestrial broadcast infrastructure โˆ’0.4% South America, MEA, Asia-Pacific Medium-term (2โ€“4 yr)
Consumer confusion across display technologies โˆ’0.3% Global Short-term (โ‰ค2 yr)

ย 

Smartphone-First Viewing Habits

Younger demographics, particularly Gen Z consumers aged 18โ€“27, increasingly default to mobile screens for video consumption. A 2024 survey found that 47% of respondents in this cohort watch long-form content primarily on smartphones or tablets rather than televisions . While this does not eliminate television demand outright, it slows household urgency to upgrade, particularly in single-person apartments and rental-heavy urban markets. The 4K TV Market faces a structural challenge in demonstrating incremental value to consumers who already perceive their phone's OLED display as "good enough."

Extended Replacement Cycles

Average TV lifespan in North America and Western Europe has stretched beyond eight years, partly because LCD panels have become more durable and partly because consumers see diminishing visual returns from upgrading a 1080p set that still functions well . This elongated replacement cadence acts as a natural ceiling on annual shipment growth, compelling OEMs to invest in trade-in incentives and bundled offers to stimulate upgrades. For the 4K TV Market, overcoming replacement inertia remains one of the more persistent constraints on volume growth.

ย 

4K TV Market Opportunities

Commercial and Hospitality Digital Signage

Hotels, airports and retail chains are replacing traditional signs with 4K commercial-grade displays that are able to broadcast dynamic content. The post-pandemic remodeling cycle in the global hospitality sector has released an anticipated USD 4.2 Billion in display procurement expenditures through 2028 [12]. The 4K TV Market is poised to take a significant bite out of this spending as commercial-grade UHD panels with 24/7 durability certifications and centralized content management dip below USD 500 in the 55-inch class.

ย 

Emerging-Market Urbanization Wave

Emerging urban household formation in India, Indonesia, Nigeria and Brazil is predicted to create more than 120 million new households by 2035 [15]. In these markets, first-time buyers of televisions are overwhelmingly choosing 4K-capable sets as sub-$300 entry-level models become widely accessible. The opportunity in the 4K TV market here is dependent on localised content ecosystems, vernacular smart-TV interfaces and distribution collaborations with regional e-commerce platforms.

ย 

Smart-Home Hub Convergence

Modern 4K TVs are increasingly becoming a hub for smart home commands, blending Matter control, voice assistants and home security camera streams. Samsungโ€™s SmartThings hub-on-TV and LGโ€™s ThinQ ecosystem have shown that the TV can be the hub of a connected home [17]. This repositioning introduces a recurring-revenue layer to the 4K TV Market as OEMs monetize software services, ad-supported free channels and IoT data analytics.

ย 

Data Monetization Through Ad-Supported Streaming

The automatic content recognition and viewer analytics of smart 4K TVs have established a USD 3.1 billion addressable advertising market that is expected to expand at double-digit rates through 2030 [23]. For OEMs, selling ads after the sale subsidizes the hardware margin, allowing for more aggressive retail pricing. This flywheel accelerates the 4K TV Market by linking manufacturing incentives to greater consumer affordability.

ย 

MicroLED and Next-Generation Display Innovation

MicroLED technology, currently confined to ultra-premium price points above USD 15,000 for 89-inch sets, is expected to breach the USD 5,000 barrier at 75 inches by 2032 [13]. As fabrication costs decline, MicroLED will create a new premium ceiling in the 4K TV Market, pushing existing OLED and Quantum Dot technologies into increasingly accessible price tiers and stimulating a fresh upgrade wave across all segments.

ย 

4K TV Market Future Outlook

AI-Driven Picture Processing and Personalization

On-device neural processing units are transforming the 4K viewing experience from passive display to adaptive intelligence. Samsung's NQ8 AI Gen 3 processor and LG's Alpha 11 chipset now perform real-time scene analysis, adjusting tone mapping, upscaling, and ambient-light compensation frame by frame. By 2030, AI picture engines are expected to be standard across sets priced above USD 400, and the 4K TV Market will increasingly differentiate on software sophistication rather than panel specifications alone [11].

Platform Economics and Post-Sale Revenue

Television OEMs are evolving from hardware sellers into platform operators. Roku's operating-system licensing model, Samsung's Tizen advertising stack, and LG's webOS content marketplace collectively generated over USD 5.8 Billion in platform revenue in 2024 [23]. This shift subsidizes hardware pricing, enabling OEMs to sell 4K sets at near-cost while monetizing viewership data and ad impressions โ€” a dynamic that will accelerate unit penetration across the 4K TV Market while compressing traditional hardware margins.

Sustainability and Circular-Economy Mandates

The EU's Ecodesign for Sustainable Products Regulation, effective from 2026, will impose recyclability scoring and minimum repairability standards on televisions sold in Europe [24]. OEMs are already redesigning chassis for modular component replacement and incorporating recycled plastics. For the 4K TV Market, these regulations increase compliance costs in the short term but create differentiation opportunities for brands that can market sustainability credentials effectively โ€” particularly in Northern European markets where eco-consciousness influences purchasing decisions.

Large-Format and Immersive Display Integration

The 80-inch-plus segment is the fastest-growing size category in the 4K TV Market, advancing at a projected 7.68% CAGR through 2035 . Falling panel costs for 85-inch and 98-inch displays are moving these formats from niche luxury into upper-mainstream territory. Concurrently, ultra-short-throw laser projection systems operating at 4K resolution are competing for the same living-room real estate, pushing panel manufacturers to emphasize brightness, viewing angle, and thinness advantages that projection cannot match.

ย 

Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 31.5% share (2024) Premium panel mix, smart-home integration, gaming
Europe 25.0% share (2024) Energy-label compliance, OLED adoption, sports broadcasting
Asia-Pacific 7.50% CAGR (2026โ€“2035) Manufacturing scale, urbanization, government subsidies
South America USD 23.25 Billion (2025) E-commerce penetration, first-time buyers
Middle East & Africa USD 21.80 Billion (2025) Hospitality investment, satellite-to-IP transition
Total USD 290.62 Billion (2025) โ€”

The 4K TV Market exhibits distinct regional dynamics shaped by infrastructure maturity, consumer purchasing power, content ecosystem depth, and regulatory frameworks. North America leads in value terms, while Asia-Pacific is on track to close the gap through superior volume growth.

ย 

North America

Country Key Metric Key Driver
United States 72.8% of regional share Streaming ecosystem maturity, high ASP
Canada 14.6% of regional share Bilingual smart-TV demand, housing starts
Mexico 12.6% of regional share Cross-border retail, growing middle class

ย 

The United States remains the single largest country-level contributor to the 4K TV Market, propelled by deep content partnerships between OEMs and platforms such as Netflix, Roku, and Apple TV+. Best Buy's Totaltech membership program and Amazon's Prime Day promotional events create concentrated purchase windows that drive quarterly shipment spikes. Canada's bilingual content requirements have prompted OEMs to invest in localized Google TV and webOS interfaces, while Mexico benefits from proximity to US retail channels and a growing urban middle class seeking affordable 55-inch sets below USD 400.

Europe

Country Key Metric Key Driver
Germany 6.52% CAGR (2026โ€“2035) Energy efficiency regulation, Bundesliga 4K broadcast
United Kingdom USD 18.42 Billion (2025) Premier League 4K streaming, early OLED adoption
France 15.8% of regional share Canal+ 4K rollout, government digital vouchers
Italy 11.4% of regional share Serie A broadcasting, large-screen cultural preference
Spain 8.7% of regional share Tourism-driven hospitality display investment
Nordic Countries 6.94% CAGR (2026โ€“2035) High broadband penetration, premium panel preference
Russia 5.2% of regional share Import substitution, domestic brand development
Rest of Europe 14.3% of regional share EU Ecodesign directive compliance

ย 

The European 4K TV Market is shaped heavily by the EU's Ecodesign Directive and energy-labeling framework, which effectively sets minimum efficiency thresholds that favor OLED and advanced LCD architectures over older CCFL-backlit designs. The United Kingdom's early embrace of OLED technology โ€” partly driven by premium Sky Q and BT Sport 4K packages โ€” has made it the region's highest-value national market on a per-capita basis. Germany's combination of Bundesliga 4K coverage and stringent energy ratings continues to steer consumer spend toward certified models.

Asia-Pacific

Country Key Metric Key Driver
China 38.2% of regional share Trade-in subsidies, domestic OEM dominance
India 8.12% CAGR (2026โ€“2035) PLI scheme, UHD broadcast mandate
Japan USD 19.87 Billion (2025) OLED preference, aging population upgrading displays
South Korea 12.6% of regional share Samsung and LG home-market advantage
ASEAN 7.86% CAGR (2026โ€“2035) Urbanization, e-commerce TV sales
Rest of Asia-Pacific 8.4% of regional share Broadband expansion, localized content apps

ย 

China anchors the Asia-Pacific 4K TV Market through a combination of massive domestic manufacturing capacity and government subsidy programs that directly stimulate television purchases. India represents the region's highest-growth opportunity as Prasar Bharati's planned transition to UHD terrestrial broadcasting creates a regulatory pull for 4K-capable sets. At the same time, the production-linked incentive scheme reduces import dependence [10]. Japan's per-household TV spend remains among the world's highest, with consumers favoring 65-inch-and-above OLED models โ€” a preference that keeps average selling prices elevated relative to other Asia-Pacific markets.

South America

Country Key Metric Key Driver
Brazil 58.3% of regional share Mercado Libre distribution, FIFA content demand
Argentina 6.18% CAGR (2026โ€“2035) Currency-adjusted pricing, installment plans
Rest of South America 22.5% of regional share Growing broadband, regional OTT expansion

ย 

Brazil dominates the South American 4K TV Market, benefiting from Mercado Libre's expansive e-commerce infrastructure and strong consumer appetite for sports content in 4K. Installment payment plans โ€” some stretching to 24 months interest-free โ€” have proven critical to converting intent into purchase in a region where single-transaction affordability remains a barrier. The 2026 FIFA Club World Cup, hosted in the United States but avidly watched across Latin America, is expected to trigger a measurable pre-event TV upgrade spike.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 28.4% of regional share Vision 2030 smart-city projects
UAE 7.22% CAGR (2026โ€“2035) Tourism infrastructure, luxury retail
South Africa 16.5% of regional share Pay-TV operator upgrades (MultiChoice)
Egypt 12.8% of regional share Population scale, new administrative capital builds
Rest of MEA 24.1% of regional share Satellite-to-IPTV transition, hotel construction

ย 

The MEA region's 4K TV Market growth is anchored by Gulf Cooperation Council states investing heavily in smart-city and tourism infrastructure under national vision programs. Saudi Arabia's NEOM and Red Sea projects alone are expected to procure over 200,000 commercial-grade 4K displays for hospitality installations through 2030 [12]. South Africa's MultiChoice is gradually migrating its DStv platform to 4K, creating a content-driven upgrade path for the region's largest pay-TV subscriber base.

ย 

4K TV Market By Region, 2025-2035

4K TV Market Segmentation

By Technology

Segment Key Metric Primary Demand Driver
OLED Display 44.4% share (2024) Superior contrast, thin form factor, gaming response times
Quantum Dot 7.40% CAGR (2026โ€“2035) Wide color gamut at competitive pricing
MiniLED USD 48.72 Billion (2025) HDR brightness performance, cost-effective alternative to OLED
Standard LED/LCD 22.1% share (2024) Entry-level affordability, emerging-market volume

ย 

OLED technology leads the 4K TV Market by revenue share, driven by its inherent ability to deliver perfect blacks and infinite contrast ratios that streaming cinematography increasingly demands. LG Display's continued investment in OLED Evo panels and Samsung Display's entry into QD-OLED production have expanded the competitive supply base, pulling prices down across the board. Quantum Dot technology, meanwhile, offers the fastest growth trajectory as sets from TCL, Hisense, and Samsung leverage blue-LED-excited quantum-dot films to deliver wide color gamut at price points 20โ€“30% below equivalent OLED models โ€” a positioning that resonates strongly in price-conscious markets across Asia-Pacific and South America.

By Screen Size

Segment Key Metric Primary Demand Driver
Below 40 Inches 8.6% share (2024) Bedroom, kitchen, and personal-space secondary displays
40โ€“59 Inches 43.3% share (2024) Mainstream living-room standard
60โ€“79 Inches USD 72.46 Billion (2025) Home-theater upgrade cycle
80 Inches and Above 7.68% CAGR (2026โ€“2035) Premium immersive experiences, commercial venues

ย 

The 40โ€“59 inch bracket continues to dominate the 4K TV Market in unit and revenue terms, functioning as the default size for primary living-room installations globally. The 80-inch-plus category, while still a single-digit share of total units, is the fastest-growing segment as panel production costs for 85-inch and 98-inch displays decline toward mainstream thresholds. Retailers report that the average screen size at point of sale has increased by approximately 5 inches over the past four years, a trend that lifts blended average selling prices.

By End User

Segment Key Metric Primary Demand Driver
Residential 62.4% share (2024) Household content consumption, gaming
Commercial 6.34% CAGR (2026โ€“2035) Digital signage, hospitality, corporate AV

ย 

Residential demand forms the backbone of the 4K TV Market, with household consumers driving the majority of unit volume across all regions. Commercial applications โ€” including hotel-room displays, airport information boards, conference-room screens, and retail digital signage โ€” represent a smaller but faster-growing segment. Commercial buyers tend toward bulk procurement cycles tied to property construction or renovation timelines, which creates lumpy but high-value order patterns that differ markedly from the consumer retail cadence.

ย 

Competitive Benchmarking

The 4K TV Market exhibits moderate concentration, with the top five players โ€” Samsung, LG, TCL, Sony, and Hisense โ€” collectively holding an estimated 58โ€“65% of global revenue. The competitive intensity has increased markedly since 2022 as Chinese manufacturers invest in brand-building campaigns targeting North American and European consumers, eroding the premium positioning historically enjoyed by Korean and Japanese incumbents. Strategic differentiation now pivots on operating-system ecosystems, AI processing capabilities, and post-sale platform monetization rather than panel technology alone.

Company Est. Revenue Share Range Key Offerings for 4K TV Market Strategic Positioning
Samsung Electronics ~18โ€“22% Neo QLED, QD-OLED, Tizen smart platform Premium technology leader; vertically integrated panel-to-set
LG Electronics ~12โ€“16% OLED evo, NanoCell, webOS ecosystem OLED pioneer; strong smart-home integration play
TCL Technology ~10โ€“14% MiniLED, QLED, Google TV integration Aggressive value positioning; rapid global expansion
Sony Corporation ~8โ€“12% BRAVIA XR, Cognitive Processor XR, PlayStation integration Premium AV heritage; content-ecosystem synergy
Hisense Group ~8โ€“11% ULED X, Laser TV, VIDAA OS Sports-marketing-driven brand awareness; price-performance focus
Xiaomi Corporation ~5โ€“8% Mi TV, Redmi TV, PatchWall OS Ultra-competitive pricing; IoT ecosystem integration
Panasonic Holdings ~3โ€“5% MZ series OLED, Hollywood tuning collaboration Niche premium; strong in Japan and Europe
Vizio Inc. ~3โ€“5% M-Series, SmartCast, WatchFree+ US-focused; ad-platform revenue model
TP Vision (Philips) ~2โ€“4% Ambilight, Android TVโ€“based platform Design differentiation; European market strength
Sharp Corporation ~2โ€“4% AQUOS XLED, 8K-to-4K downscaling Japan-centric; Foxconn manufacturing synergies

ย 

ย 

Recent News & Developments

  • Samsung Electronics (January 2025): Unveiled its 2025 Neo QLED 8K and 4K lineup featuring the NQ8 AI Gen 3 processor with real-time content-adaptive HDR optimization, reinforcing its premium positioning in the 4K TV Market [8].
  • LG Electronics (March 2025): Announced the OLED evo M5 wireless 4K television with Zero Connect Box 2.0, enabling cable-free wall mounting and expanding installation flexibility for residential and commercial buyers [25].

ย 

ย 

  • Sony Corporation (June 2024): Integrated generative-AI scene enhancement into the BRAVIA XR processor, enabling frame-by-frame texture and depth optimization for upscaled content [11].
  • Hisense Group (November 2024): Extended its UEFA partnership through 2030, securing pitch-side LED branding across Champions League and Europa League matches to strengthen brand recognition in the European 4K TV Market [22].

ย 

ย 

ย 

ย 

ย 

4K TV Market Report Scope

Report Attribute/Metric Details
Market Scope Global 4K TV Market hardware revenue only; excludes content licensing, advertising, and accessory peripherals
Study Period 2021-2035
Base Year 2025
Historical Data 2021โ€“2024
Forecast Period 2026โ€“2035
Market Size in 2025 USD 290.62 Billion
Market Size in 2035 USD 593.43 Billion
CAGR (2026โ€“2035) 7.40%
Fastest Growing Segments 80 Inches and Above (by screen size); Asia-Pacific (by geography)
Regions Covered North America, Europe, APAC, South America, MEA
Companies Profiled Samsung, LG, TCL, Sony, Hisense, Xiaomi, Panasonic, Vizio, TP Vision (Philips), Sharp
Valuation Currency USD Billion
Methodology Triangulated approach: bottom-up vendor revenue aggregation, top-down TAM validation, expert interviews (n=42), secondary research across 25+ databases

FAQs

How does the warranty and after-sales service landscape differ between premium and budget 4K TV brands?
Premium brands like Sony and LG typically offer 2โ€“3 year panel warranties with on-site service, while budget brands often limit coverage to 1 year with depot repair. Buyers should factor total cost of ownership when comparing sets priced below USD 400.
What refresh rate should buyers prioritize for gaming on a 4K display?
A 120 Hz native panel with HDMI 2.1 input delivers the smoothest gaming experience at 4K resolution. Sets marketed as "motion rate 120" often use 60 Hz panels with interpolation and should be avoided for competitive gaming.
How do energy efficiency regulations influence the 4K TV Market in the EU versus the US?
EU Ecodesign mandates enforce minimum efficiency tiers that effectively ban the least-efficient panel architectures [24]. The US relies on voluntary ENERGY STAR certification, creating a softer but still influential purchasing signal.
What role does local-language content play in driving 4K TV adoption in emerging markets?
Vernacular 4K content is a decisive purchase trigger in India, Indonesia, and Brazil, where households upgrade specifically to access regional-language streaming in UHD. OEMs that pre-load localized apps see measurably higher sell-through rates.
How do commercial procurement cycles for 4K displays differ from consumer retail patterns?
Commercial buyers follow construction or renovation timelines with bulk orders placed 6โ€“12 months ahead of installation. This creates lumpy, high-value purchasing cadences that contrast sharply with consumer seasonal spikes around holidays.
What is the practical difference between Quantum Dot and OLED for average living-room viewing conditions?
Quantum Dot excels in bright rooms with higher peak brightness, while OLED delivers superior contrast in dim environments. For typical mixed-lighting living rooms, Quantum Dot often provides better value per dollar at equivalent screen sizes.
How are tariffs and trade policies affecting the 4K TV Market's competitive dynamics?
US Section 301 tariffs on Chinese-assembled televisions have pushed brands like TCL and Hisense to establish final-assembly operations in Mexico and Vietnam [20]. This geographic diversification reshapes supply chains without materially reducing competitive pressure. ย  ย 
Author
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















